$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
$CENX is a non-AI bottleneck https://t.co/L0PvNNH4HK
JPM taking $ACMR PT from $70 to $110 >105% order growth (memory likely more than half) > international markets expanding > ECP lead (#3 globally) > “Platform in the making” https://t.co/caRVrfHgSm
Bernstein China Semicap & WFE update: $101 bn in ‘28 > WFE ramp drives reacceleration of local WFE vendors > logic underestimated > memory revised up: CXMT, YM & JHICC easier to ramp clean rooms > local vendors take share from global vendors > ‘27-28 numbers go up $ACMR https://t.co/8qZFoulEau
UBS initiates $CENX conservatively: $60 at 4x EV/EBITDA > Oklahoma & shareholder return catalysts > best leverage to US MWP > Oklahoma and datacenter not priced in > 4x below normalized mid cycle https://t.co/MiKQD9rlFV
Timna on $CENX “early innings of broader FCF rebound.” “Hugely undervalued” at 1.5x their ‘27 EBITDA. $83 PT at 4x! Direction of numbers up, delta to street up, and lots of multiple rerate room imho https://t.co/8wkrmh5S83
GS on $ACMR beat and 2026 raise. PT $164 2027 numbers and memory contribution (CXMT matter more) imho https://t.co/XXKNyhL8Gg
“for the first time in over a decade, all Century assets should be operating at full capacity. I'm very proud to report today that our team has delivered” As expected, Q3 & Q4 will be when the real earnings power of $CENX is demonstrated. Still under-earning. Still bottleneck. https://t.co/Buw6H87Sed https://t.co/KyfyjMcJhq
$ACMR https://t.co/iEnipv5cD6
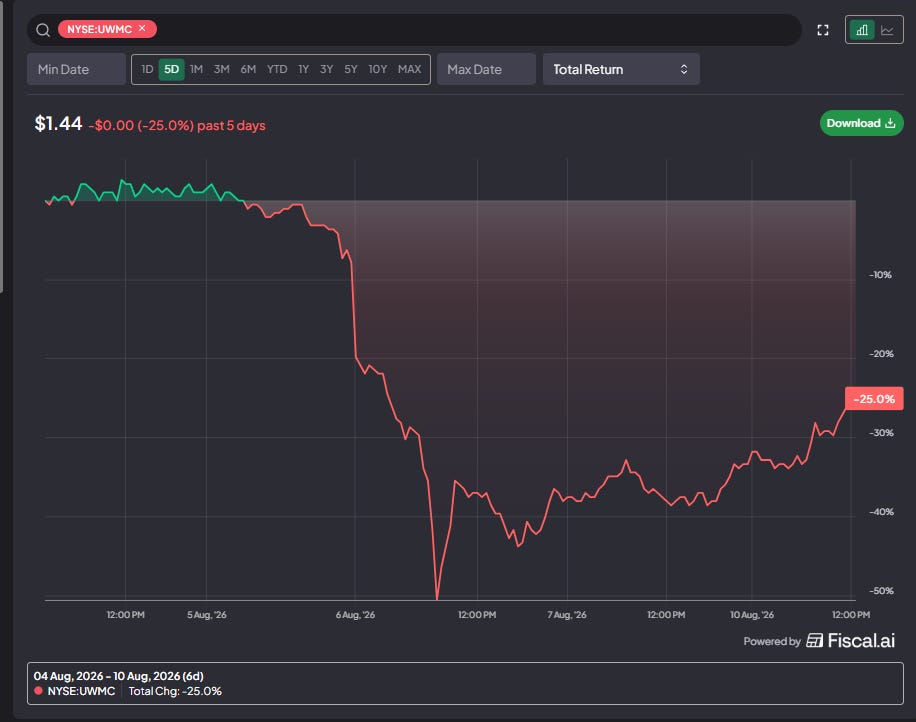
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…

Hims & Hers investor Paul Cerro is long again on lab and patient data driving retention and LTV, despite management concerns, GLP-1…

Pernas Research names Capstone Energy and Stabilis Solutions as AI data-center power beneficiaries, alongside Tenable, Upwork, Wise and…

Butler National Corporation is the subject of a stock pitch presented at the MS Microcaps Summer Virtual Conference.
Diversified Energy cut $233 million of debt in 1H26, repurchased $93 million of stock and sold $273 million of land and assets while…

Perimeter Solutions’ 2Q26 revenue rose 31%, while operating income fell 11% as USDA pricing and DLA delivery timing hurt Fire Safety; it…

Floor & Decor’s same-store sales improved to minus 2%, while $45 million of tariff refunds lifted second-quarter gross profit and operating…

Lionheart Holdings’ 41-cent CUBWW warrants hinge on a SPAC merger valuing KEO Energy’s Venezuelan PetroUrdaneta stake at $1 billion, versus…
Builders FirstSource reported Q2 2026 sales down 9% to $3.9 billion as weak housing demand and aggressive competitor pricing cut EBITDA…
 BCO · long
Brink’s $6.6 billion cash-and-stock acquisition of NCR Atleos underpins the long case, citing strategic and financial rationale.

LandBridge outlined $300 million in pore-space free cash flow within five years; its Permian data-center project remains proof of concept.

New Fortress Energy’s restructuring cancels its 12% 2029 notes for 94.3% of BrazilCo, $974 million of New NFE preferred and 25.8% of New…

Hallador’s 1 GW Merom plant could supply a proposed 1,000-acre Sullivan County data center, with local filings and Stantec references tying…

Theravance Biopharma began a strategic review after a failed Phase 3 trial.

Ategrity Specialty’s 30% premium growth, stable reserves and $50 million buyback target an undervalued, thinly traded specialty insurer.

Braemar Hotels & Resorts’ Four Seasons sale prompts updated views on HST.
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…

Vaca Muerta’s $36–45-per-barrel breakevens, Milei reforms and $17 billion infrastructure buildout underpin the bullish case for Vista…

A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.