Hippo Holdings ($HIPO): The Insurtech That Stopped Chasing Hype and Started Making Money
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier and MGA fee income.
$FUBO asymmetric @ $8.85
How is $PSTL trading at 16x FFO with rates rising? The valuation seems entirely detached from reality. If it was a big growth name I'd understand it somewhat, but they've raised the dividend 22.5% over the course of 6 years, really not so special. https://t.co/0NmNKFNBxd
Wow! $ALTO $GPRE https://t.co/Hj3xWMAbMH https://t.co/H0Giupx0ym
Lesaka CEO Ali Mazanderani has bought more than $10 million of stock while pursuing a $20 to $30 valuation case through targeted…
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
VersaBank's Q3 revenue rose 23% and adjusted net income 27%, while a 2.19% net interest margin and 19.15x forward earnings temper its 2027…
 Grassroots Trading
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
Pyxis Oncology's recent financing extends MICVO's runway to clinical milestones as the oncology candidate works to establish a safe,…
 Myriam Alvarez 2 clicks
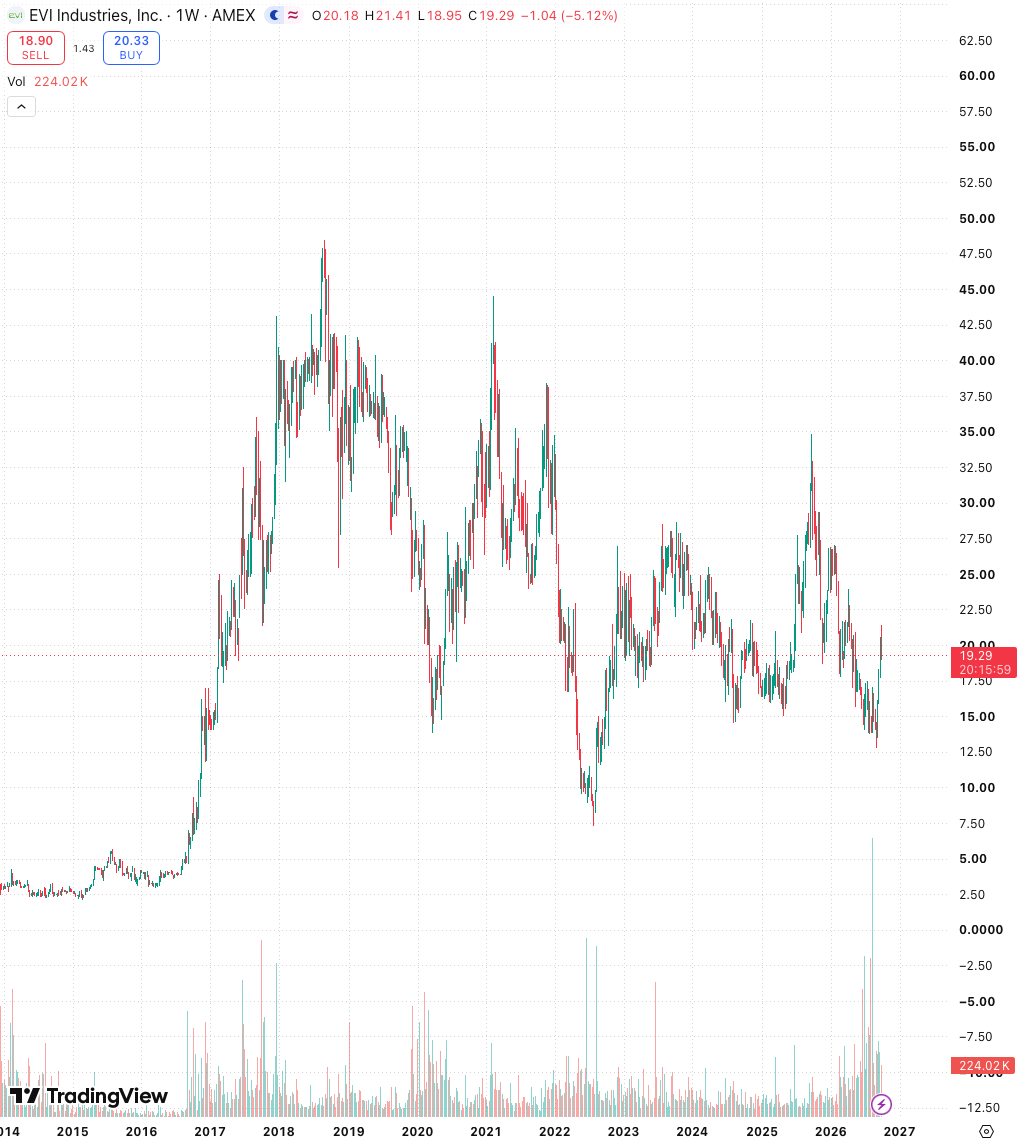
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
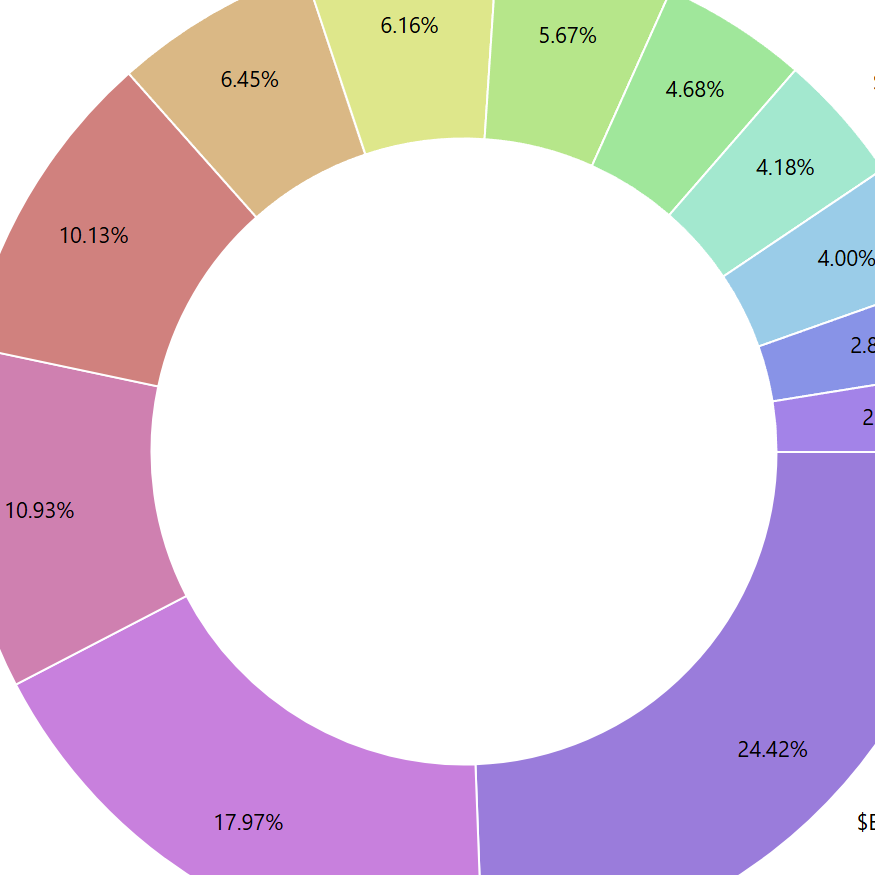
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Washington Trust Bancorp offers a 5.8% dividend yield, with C&I loan growth supporting ROE despite 40% commercial real estate loan…
 Sorrento Research
 BNTC · long
Benitec Biopharma's BB-301 gene therapy is in a Phase 1b/2a trial for an ultra-rare muscular dystrophy.
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
 Quad 7 Capital 2 clicks
Zentek shipped its first ZenGUARD air-filter order to a Canadian federal facility as its Albany graphite PEA confirmed a US$3.85 billion…
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
Riley Exploration Permian raised oil production guidance after a Q2 beat, targeting 30% growth while trading at 6.52 times forward earnings.
 The Supercycle Investor
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
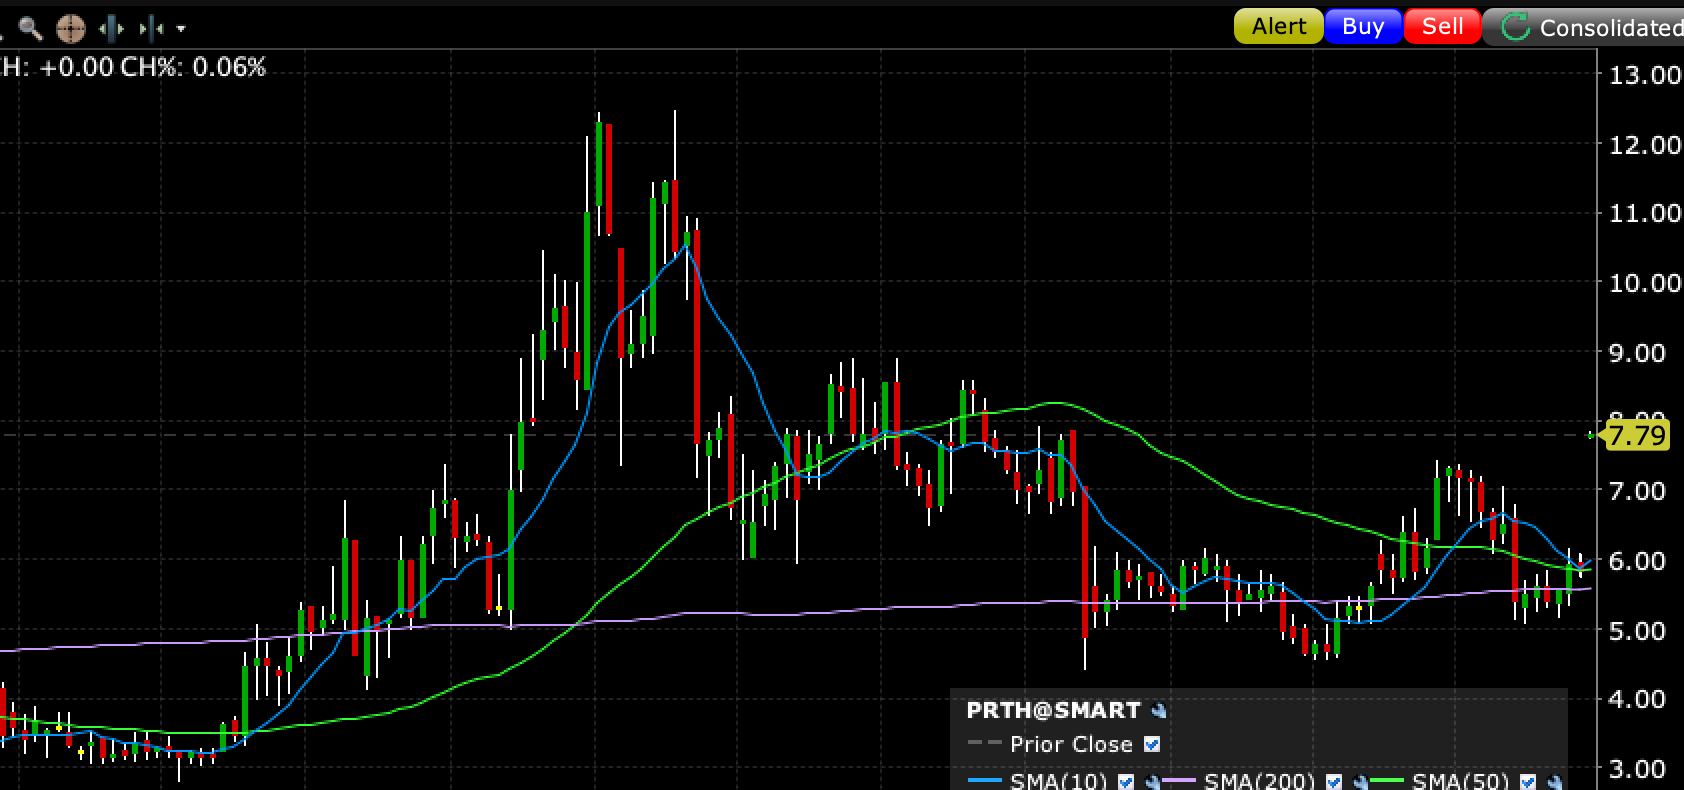
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.