You Understand Now, Why You Came This Way
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports fresh news.
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports fresh news.
@amuuhasuo $NN Curious how you get to 4 billion valuation. We own almost 14 MHz. I believe Grain is closer to 2 per pop since it is currently 5x5. 14 MHz is 4.5 billion pops. Times 2 is 9 billion or 45 per share.
$OC https://t.co/pA9b0mDR9D https://t.co/Mx02ZpE88d
@amuuhasuo That is beyond not likely. The way they indicate no would be to do nothing. Let’s face it, SpaceX buying Grain is great comp for $NN. Some days are good for shareholders, some days aren’t. This was a fantastic news day for NN. Throw stones on a bad day, today isn’t that day.
I wonder if Russia/Ukraine will come to some sort of agreement soon? 🤷♂️ $KYIV https://t.co/kkm1TDJbPf
@RealAssetsValue @hybridvigorish @thecontracap @barowsharo What just happened with $SNDA / $BKD?
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Golar LNG ordered a $2.45 billion fourth FLNG vessel, targeting 3.5MTPA of capacity and $400 million in annual EBITDA under a 20-year…
Maase, a $5B AI infrastructure company with sub-$50M annualized revenue and persistent losses, faces governance concerns over super-voting…
 Wolf Report
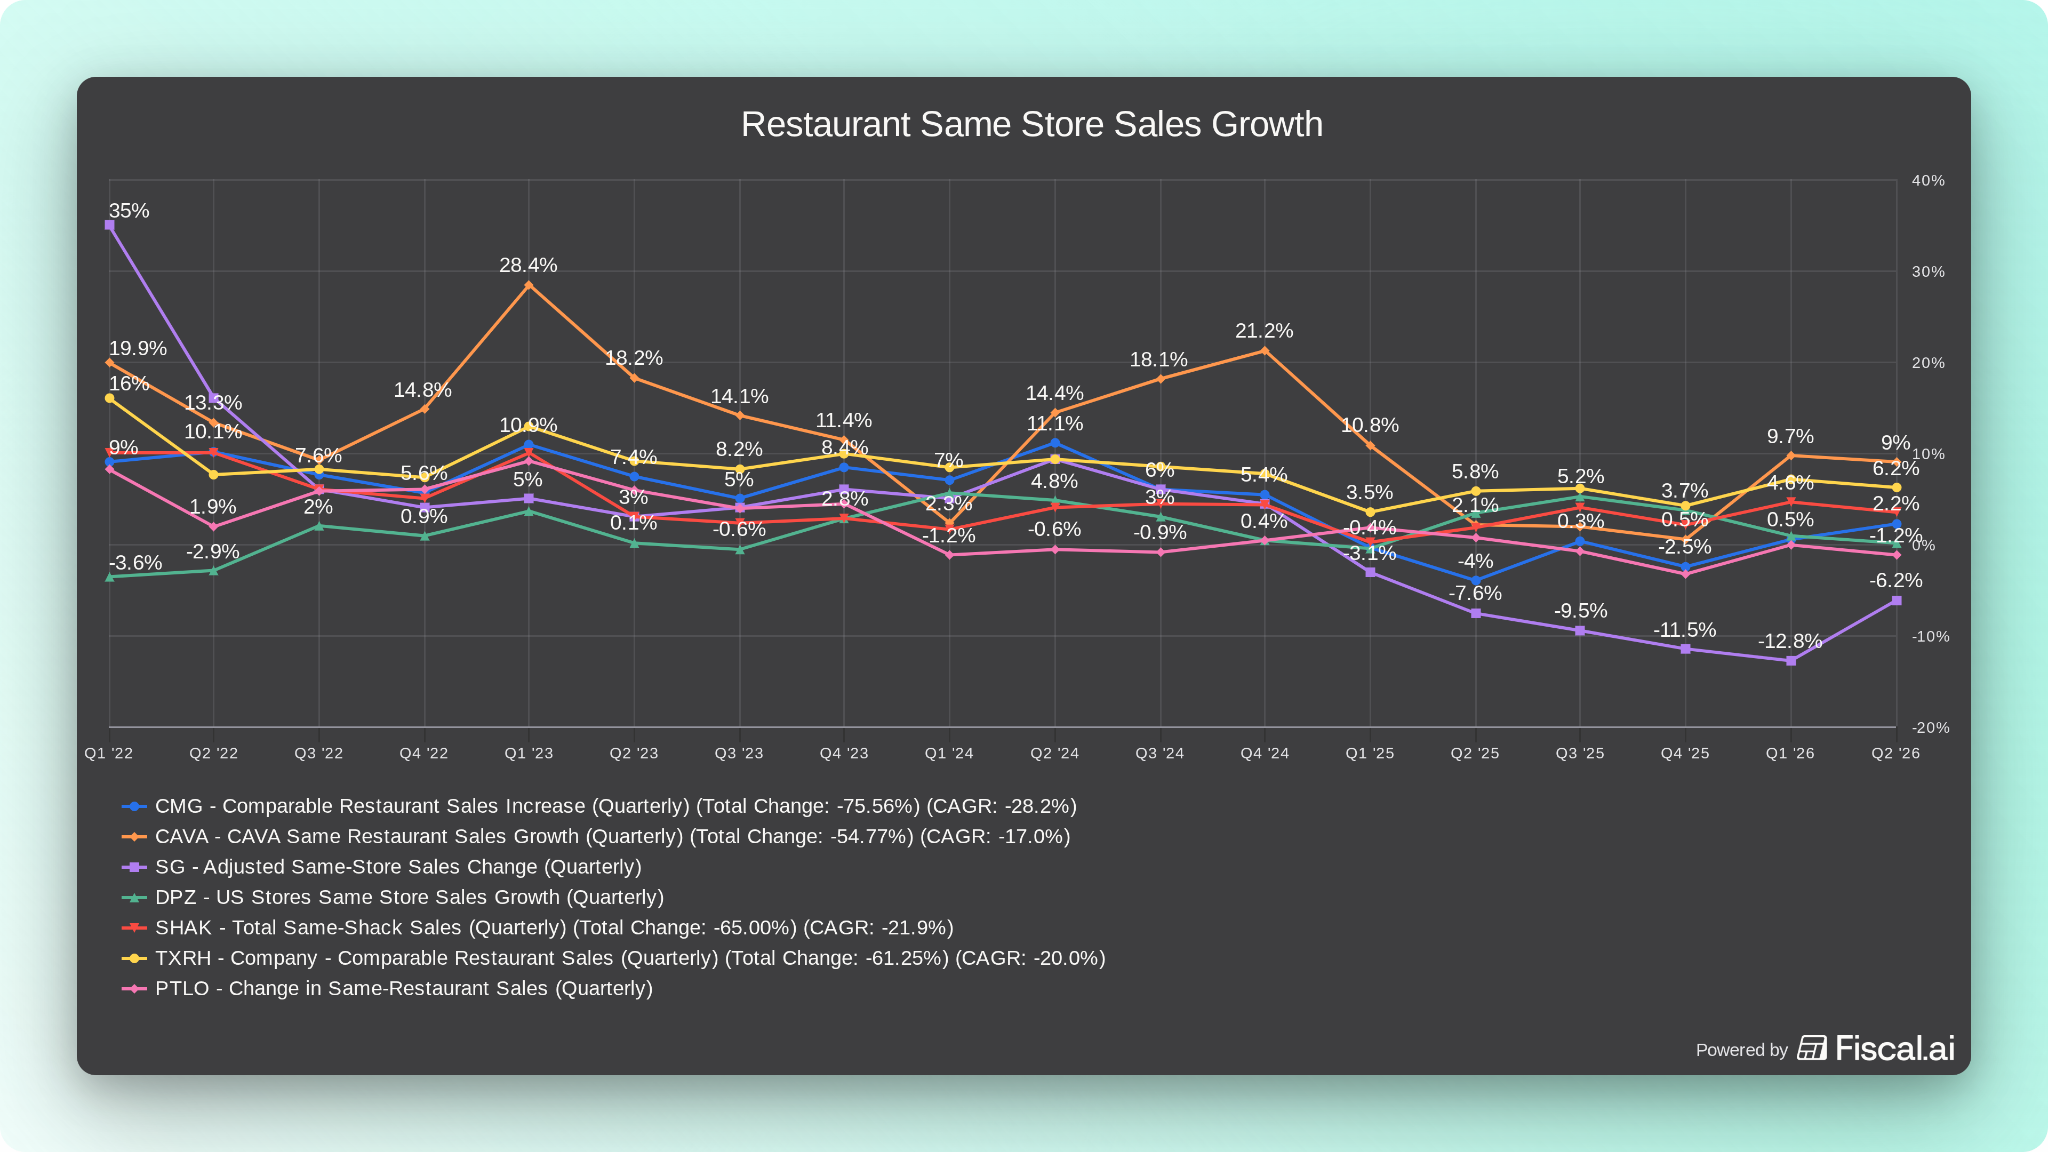
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
 Jordan Aquilina
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
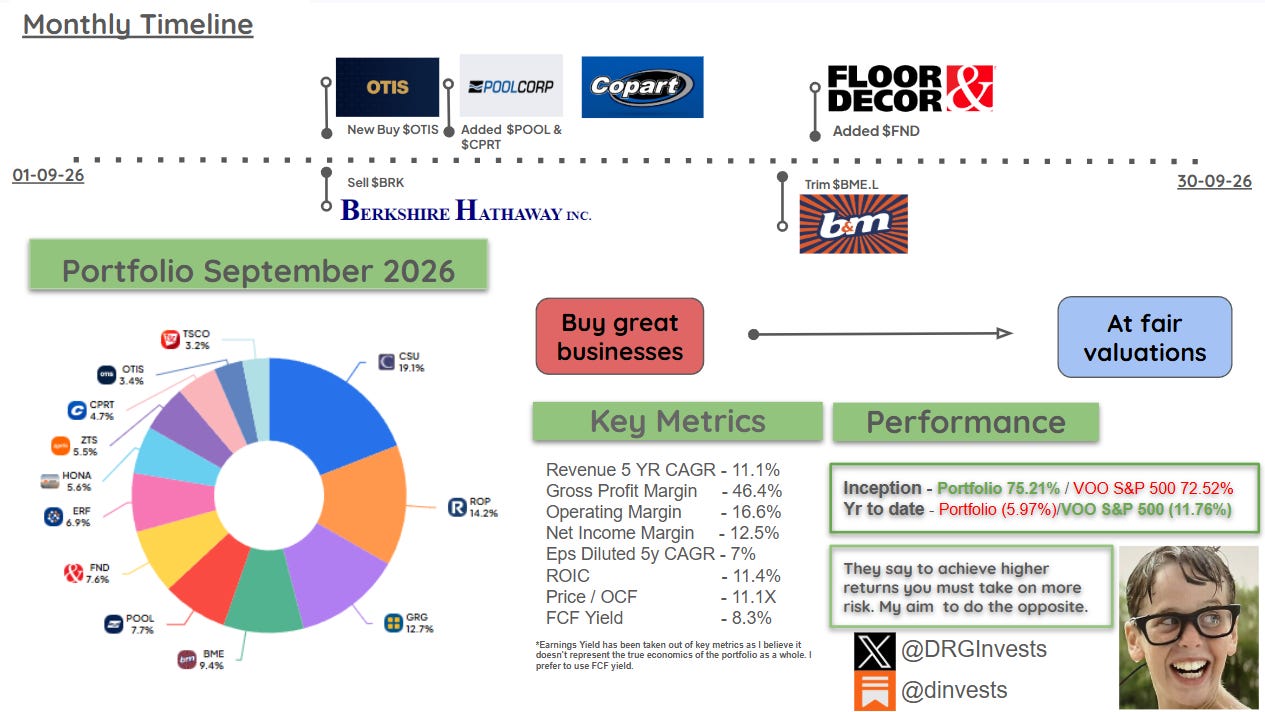
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
 NCNO · long
NCino is a commercial-lending system of record for banks and credit unions, trading at roughly 3x enterprise value to sales.
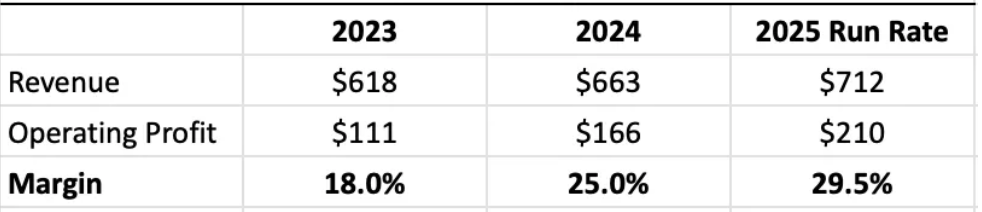
Pitney Bowes trades at an 18% FCF yield, with 25% operating margins, 30%-plus ROIC and plans to return free cash flow mostly through…
Alta Fox values NCR Atleos at $100 a share, citing ATM-as-a-Service growth, deleveraging and buybacks.
IMAX China, Hong Kong-listed 1970, is IMAX’s exclusive Greater China licensee, earning box-office-linked fees from premium large-format…
Envista, Danaher’s dental spin-off, is pitched as a de-risked long-term opportunity after U.S.
Upstart says longer repayment terms lifted Q1 debt-settlement acceptances 50%, but does not disclose delinquency changes or the number of…

Illumina appointed activist Keith Meister to its board as an SEC investigation into the Grail acquisition raises questions over 122.5…

Cinemark’s $200 million buyback anchors a review of theater cost structures, MCS and a completed Fairfax preferred-share special situation.
Phinia revised executive contracts to raise CEO severance to $5.25 million and guarantee full equity vesting in a sale after its spin-off…
Tenable faces CEO succession under difficult circumstances, putting its governance and leadership transition in focus.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.