What I’ve Been Up To
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
 Jordan Aquilina
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
 Quad 7 Capital 2 clicks
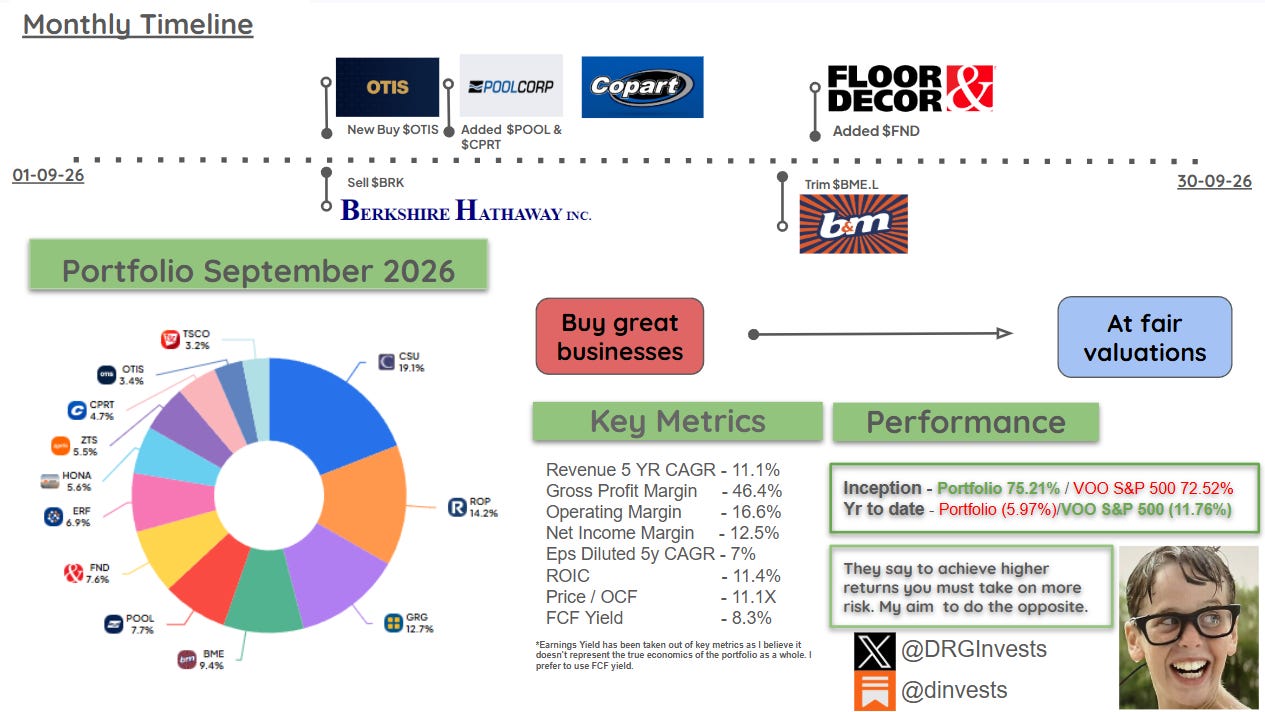
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
Geely’s ZEEKR nearly doubled first-half 2026 deliveries to 178,000, while Geely bought 30% of NIO’s battery-swapping unit to reduce…
 The Asian Investor 5 clicks
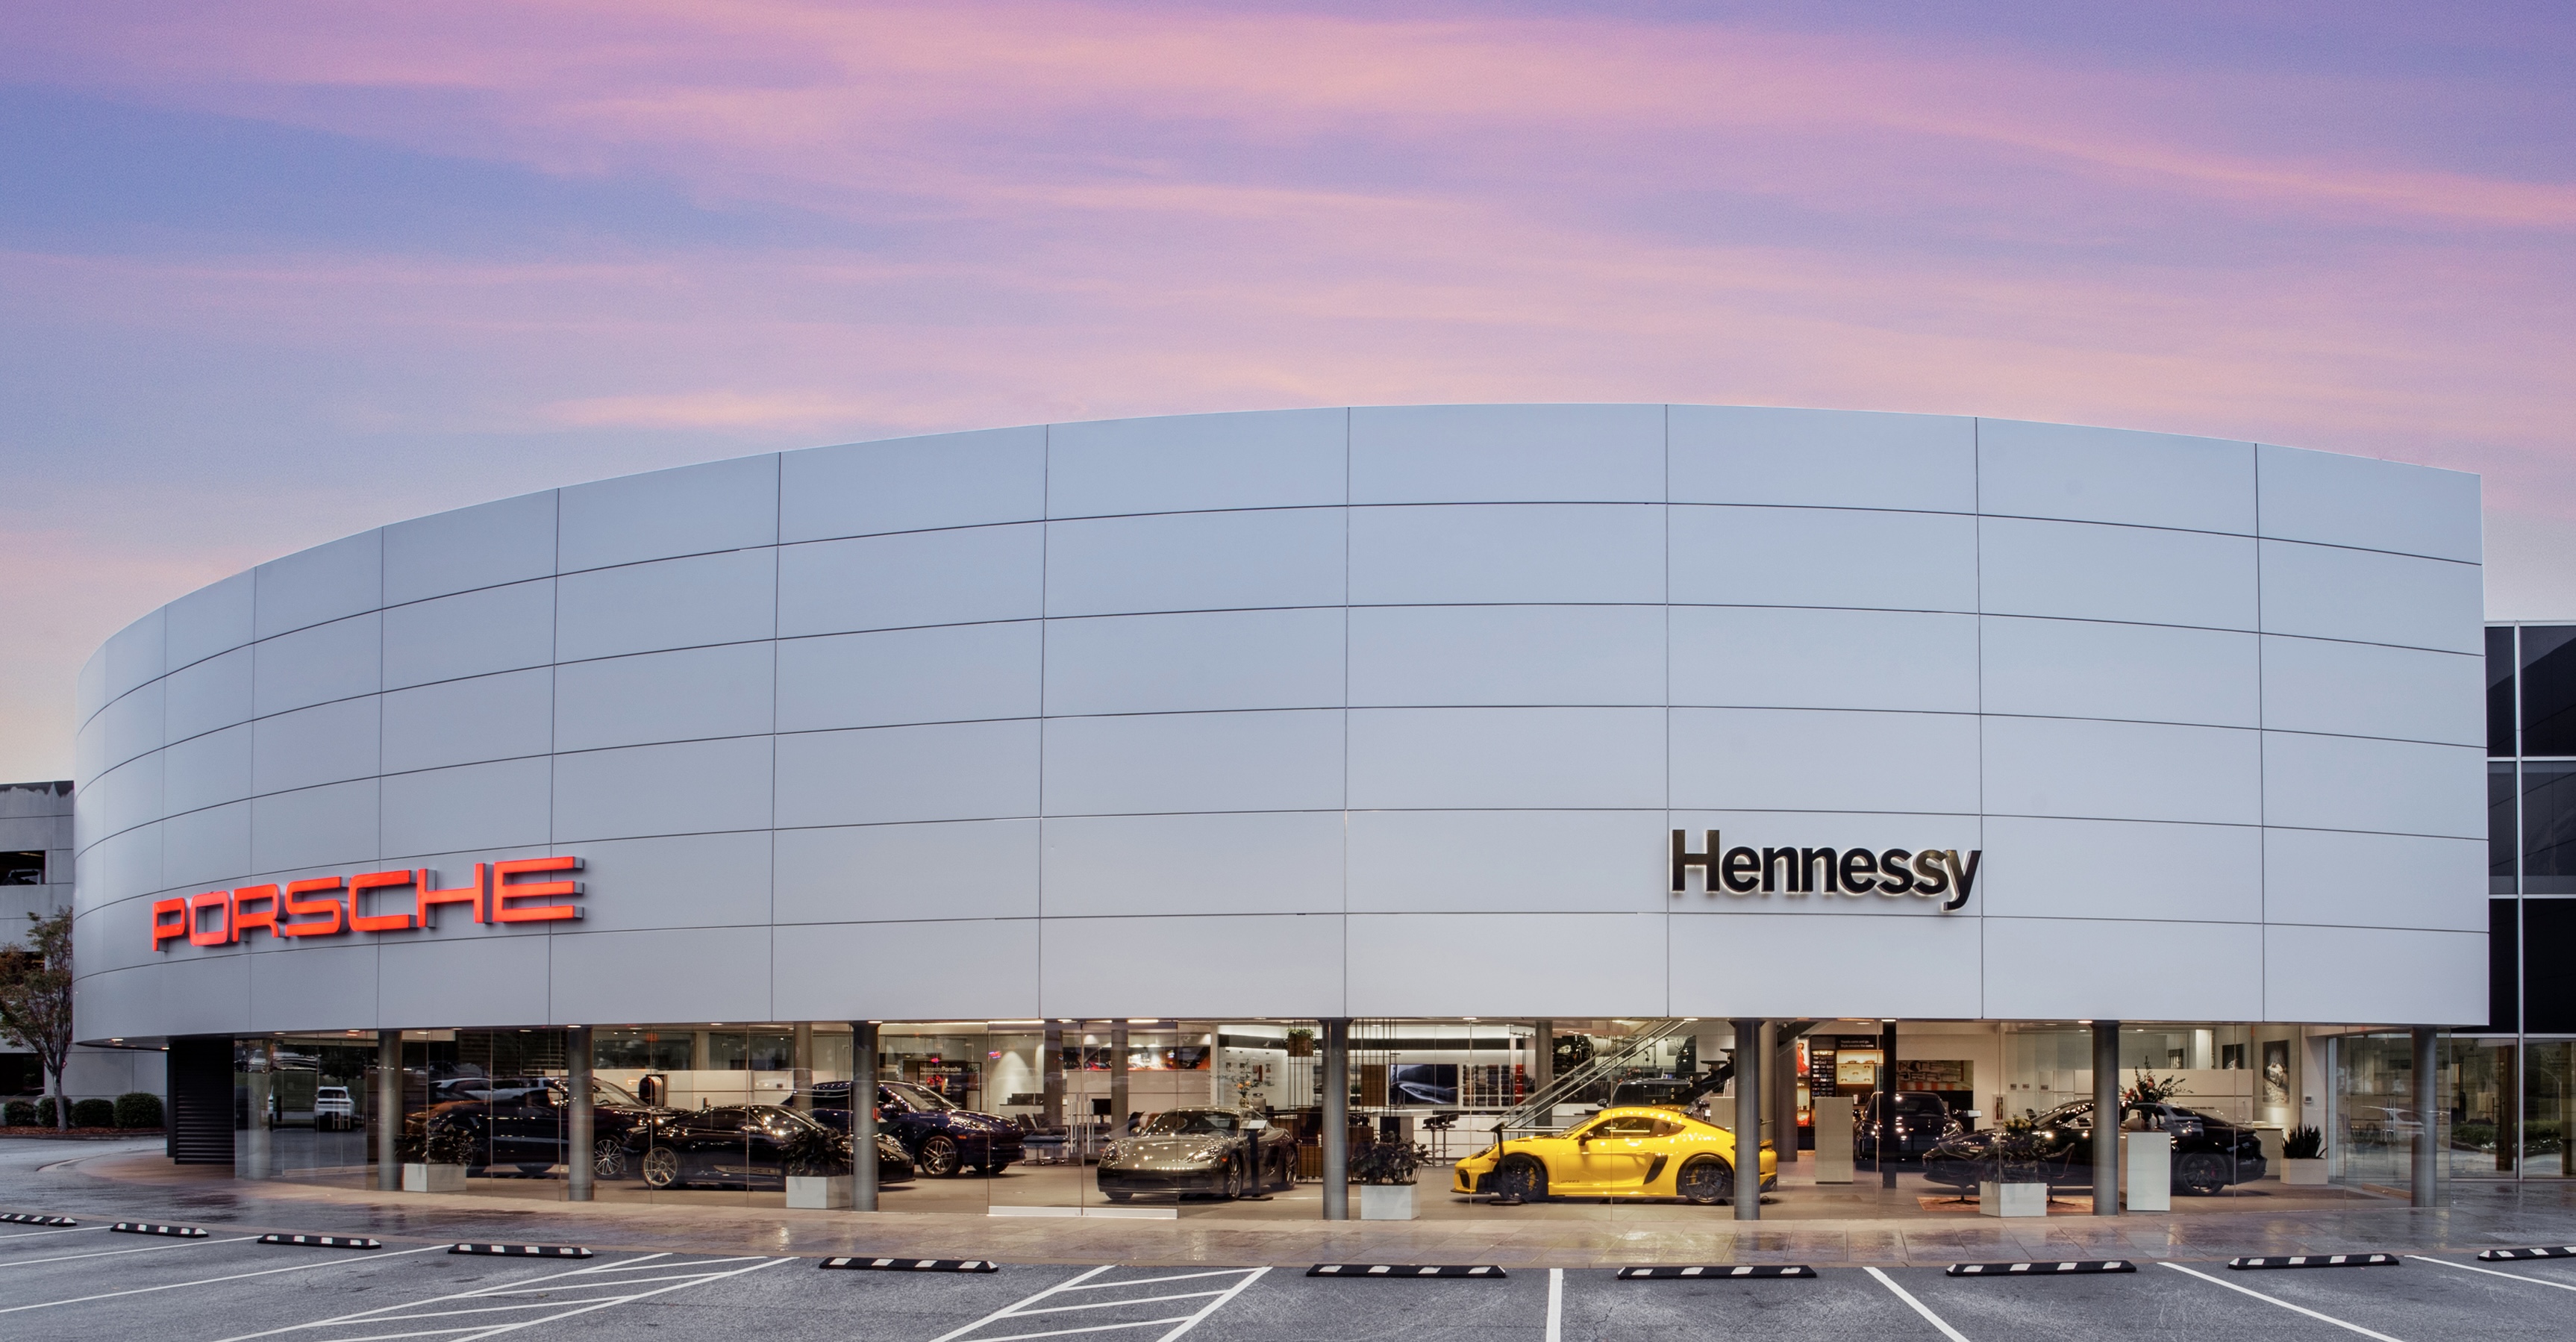
Group 1 paid $1 billion of goodwill for Hennessy’s 10 dealerships, a record $100 million per store, financed largely with $1.25 billion of…
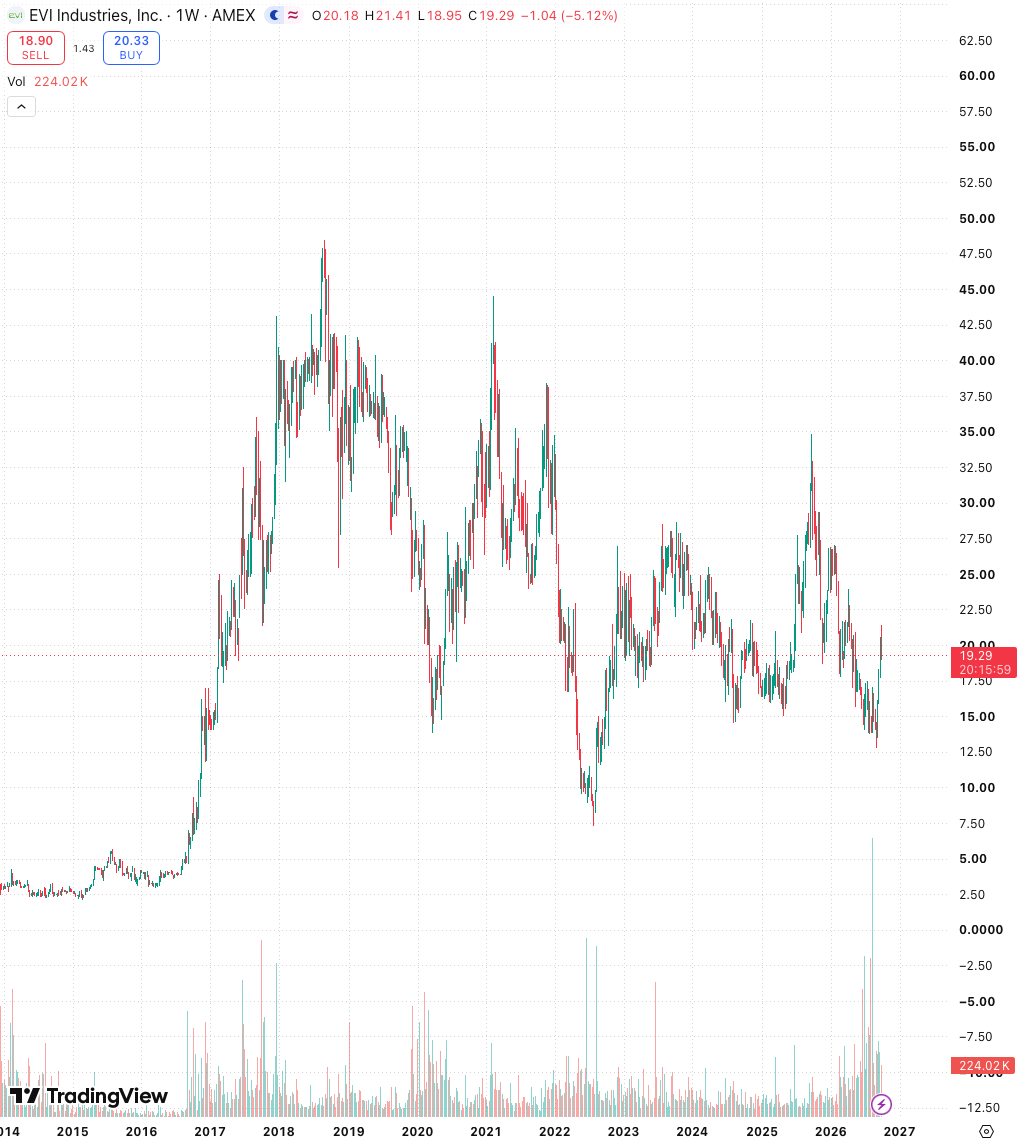
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
 ABG · long
Asbury Automotive Group's changed setup and underperformance versus other public dealers form the basis for a renewed long thesis.
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is…
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
Rocket Lab reported Q2 revenue up 62% to $234.1 million and backlog up 137% to $2.36 billion, while operating losses and cash burn…
AAR’s $1.8 billion acquisition of a 65% stake in MRO Holdings adds widebody aircraft maintenance and targets a 19% to 20% EBITDA margin by…
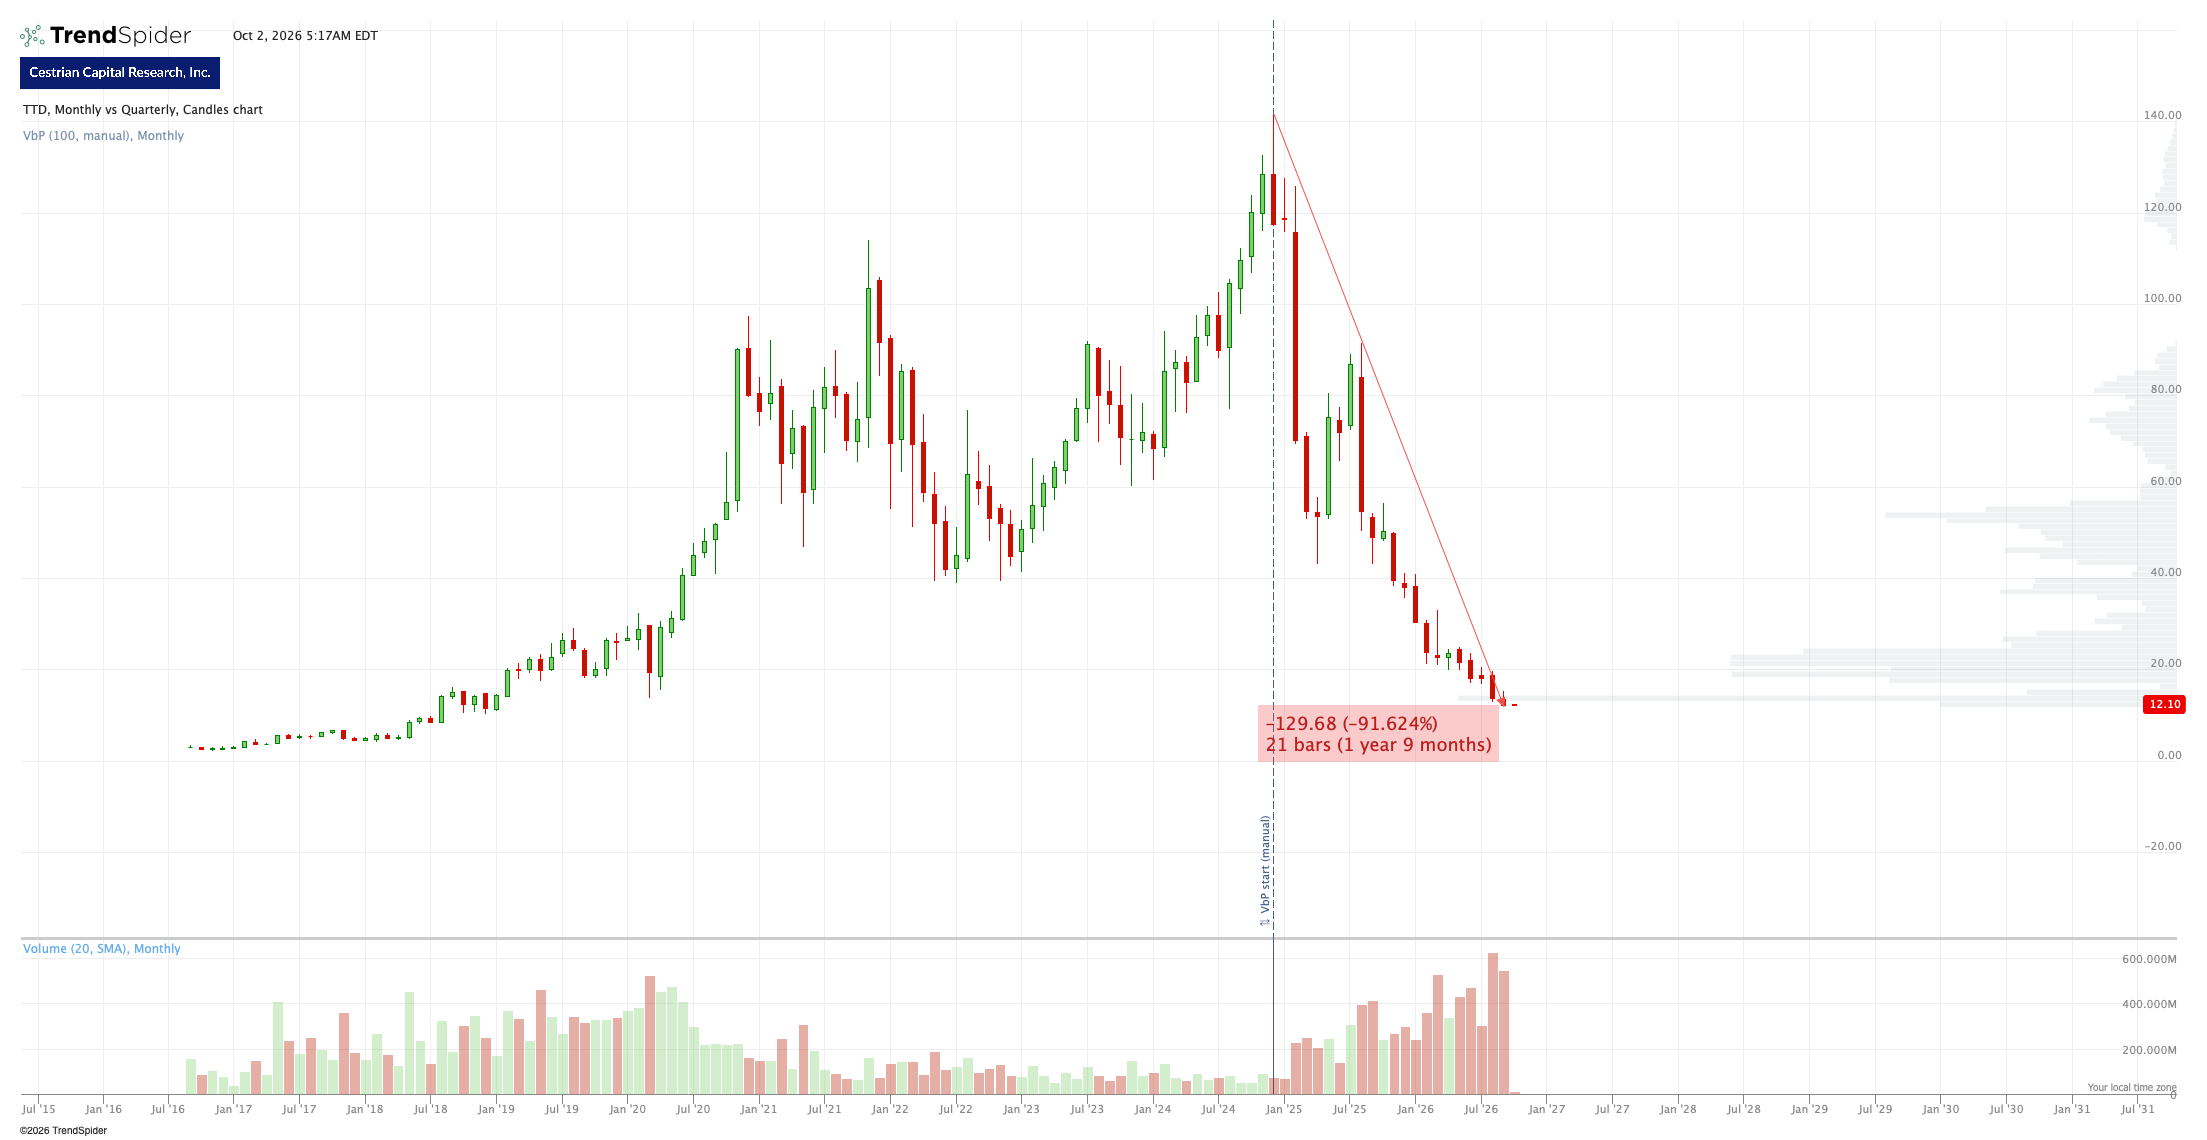
The Trade Desk's Q2 revenue grew 3% to $715 million as Q3 guidance called for a year-over-year decline; TTD has fallen over 90% from its…
Belden targets net leverage of 2.9x by 2027 from 3.9x, using RUCKUS's 65%+ gross margins and free cash flow to reduce debt.
 Lee Bailey
Crocs has $2 billion of buyback authorization, more than a third of its market cap, as North American sales stabilize and HeyDude drags on…

Turning Point Brands' FRE and Alp nicotine pouches aim to become a third C-store brand behind ZYN and Velo as PMTA rules limit new entrants.
Mattel rose 19% on takeover speculation, but a potential $20-per-share bid, margin pressure and CEO transition leave its standalone…
 Seeking Profits
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.