
$TPB: can Turning Point Brands be the third player in nicotine pouches? | Saberpoint Capital
Turning Point Brands' FRE and Alp nicotine pouches aim to become a third C-store brand behind ZYN and Velo as PMTA rules limit new entrants.
Turning Point Brands' FRE and Alp nicotine pouches aim to become a third C-store brand behind ZYN and Velo as PMTA rules limit new entrants.
$EVC crashing as I’m only up 310% now. My wife is seriously pissed the heck off.
KB Home Cuts Margin Outlook as Housing Conditions Worsen $KBH https://t.co/OA4utledZC
$FUN Activist Jana Partners Urges Six Flags to Explore Sale https://t.co/ifMKt79541
Pearson, CarMax, Talen Energy, KBR and Apollo Commercial Real Estate lead a 33-company survey of activist campaigns, buybacks, M&A and…
Ladder Capital trades below book value with high yield, but faces margin pressure and office-loan exposure despite diversified funding and…
 Albert Anthony
Group 1’s 19% ownership cap, tied to automaker franchise agreements, frames Conifer’s 1.9 million-share stake and potential buyback-driven…
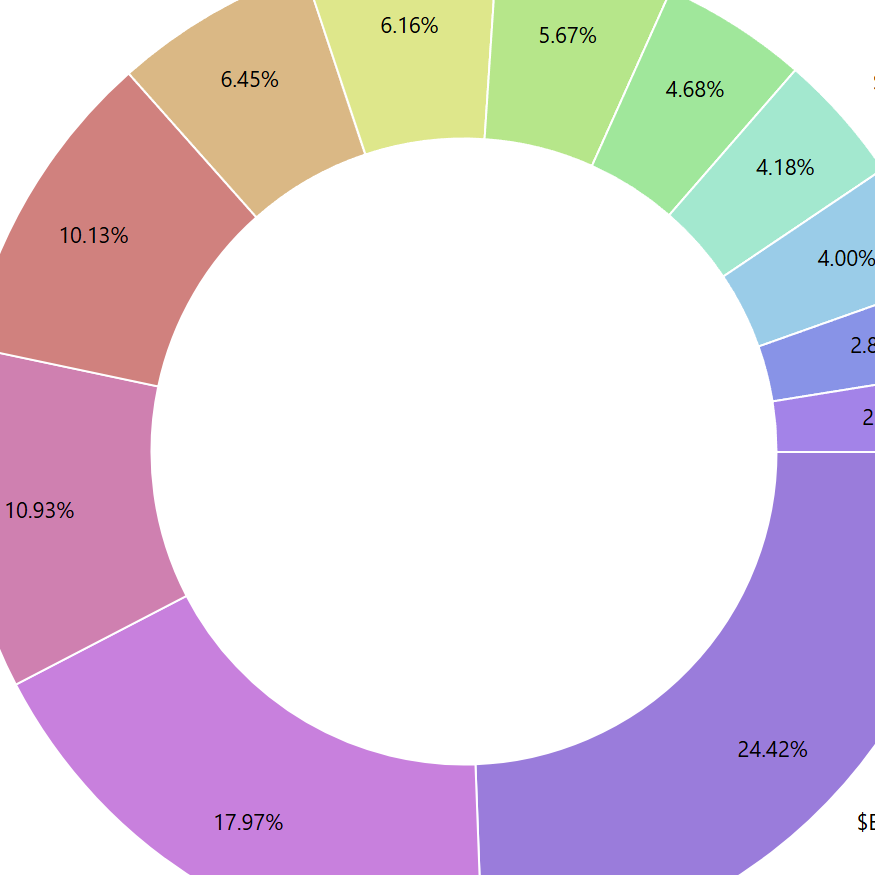
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Irrational Analysis reports 51.55% outperformance versus a semiconductor ETF, adding Credo for SerDes and QMCO for AI-driven tape storage…
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
Vicor, Rayonier, Accenture and nine other lesser-covered stocks make up Seeking Alpha’s Undercovered Dozen.
 The Undercovered Dozen 4 clicks
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Sezzle reports subscribers up 76.4%, transactions up 32% and quarterly GMV up 38%, with expanding margins supporting improved profitability…
 The J Thesis
Research Roundup covers AAON's data-center cooling ramp, Knife River's margin recovery, ChronoScale's Microsoft-backed neocloud buildout…
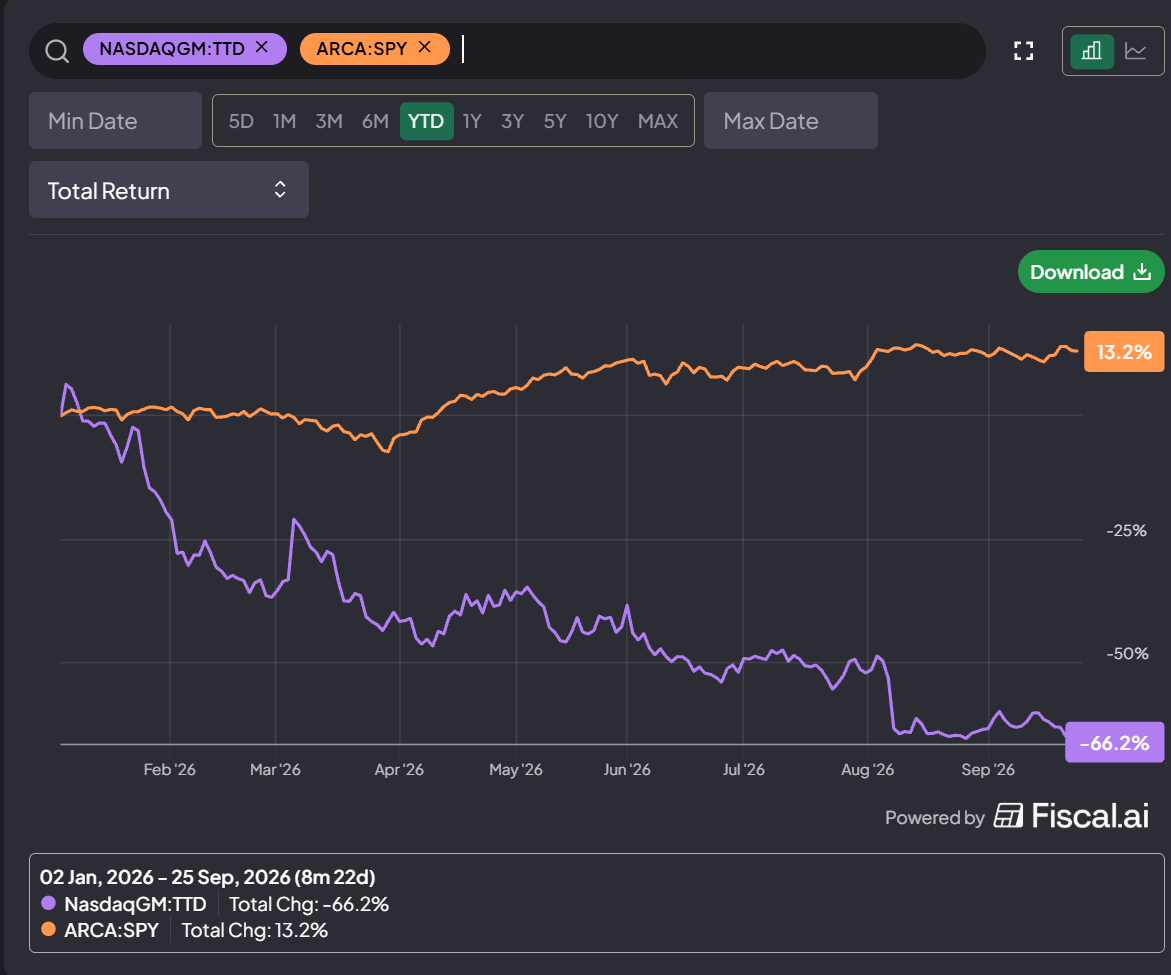
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
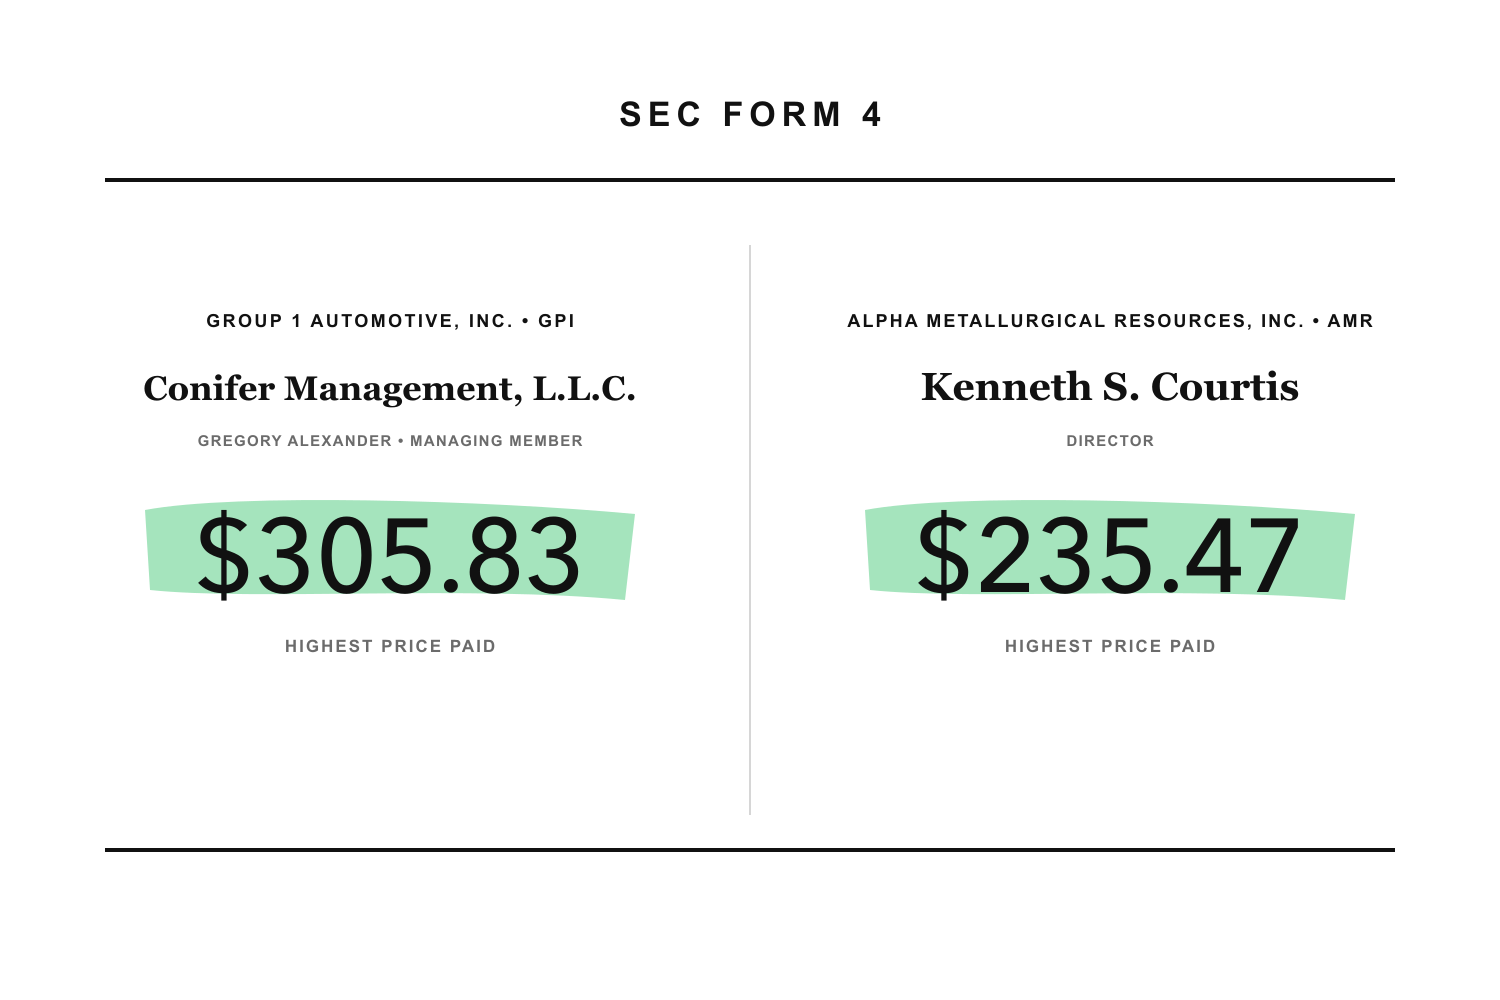
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.
Applied Optoelectronics targets $1.1 billion in 2026 revenue as 800G and 1.6T data-center demand drives capacity expansion, despite…
 Infinity Curve 2 clicks
Gentherm’s Oct. 1 Reverse Morris Trust with Modine adds commercial and off-highway operations, leaving THRM at 7.4x pro forma EBITDA with…
QuantumScape faces a 2029 PowerCo plant delay, reduced partner commitments and no revenue, with a scenario-weighted $2.12 per-share…
 Bears of Wall Street
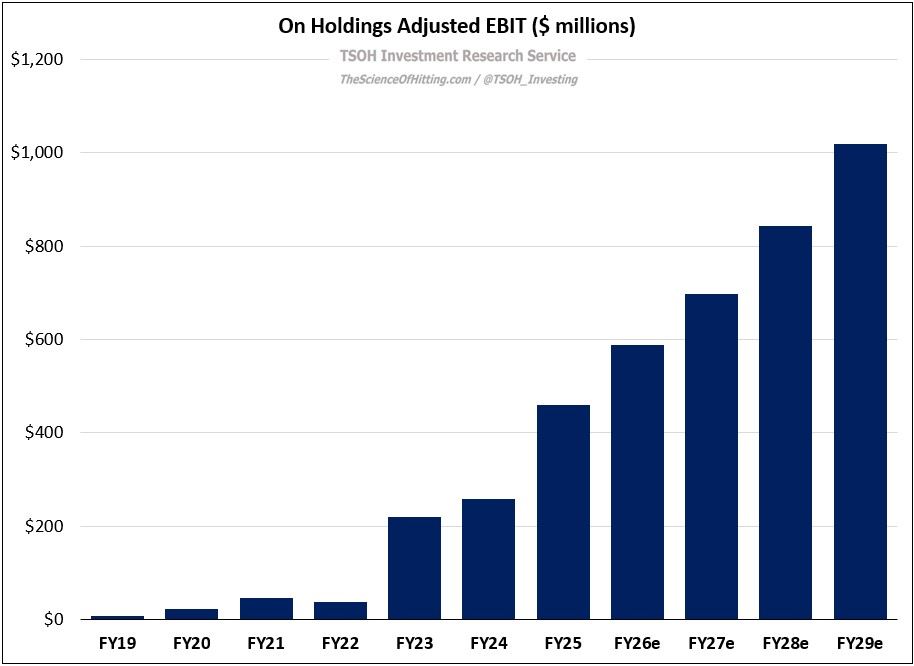
On Holdings targets premium growth through 2029, using LightSpray soccer cleats and higher pricing, with ASPs rising from $145 to $170…
Shake Shack combines 23% restaurant-level margins, 703 locations and positive free cash flow; the bullish thesis targets $4 billion…
 Security Analysis 1 click
 SFIX · long
Stitch Fix’s 2017 IPO rested on overly ambitious long-term growth expectations and an unrealistic definition of its addressable market.
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s…
Every publication on this site, hand-picked.
Albert Anthony Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.