Oak Bloke Bonkers Conkers 13th September 2026
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys despite higher prices and unresolved project risks.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys despite higher prices and unresolved project risks.
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
1/ So first things first, $HHH missed on top and bottom line. Am I concerned? Absolutely not. Value was created for shareholders and I'll briefly explain why...
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
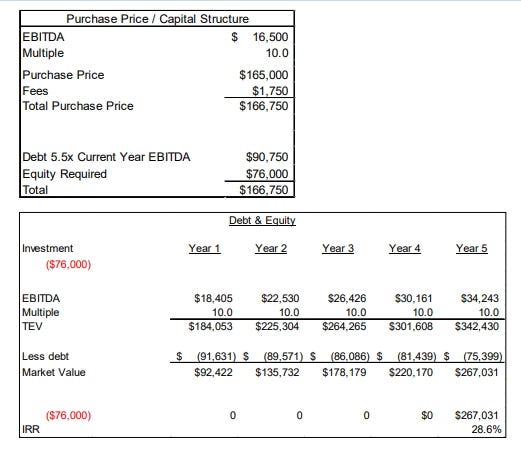
Here is a little pricing guide for any of you looking into $HHH at the moment. Credit to @mfwarder for the format. https://t.co/MeZP5qopmR
@marginofdanger @BillAckman Additionally, $HHH as a pure play MPC is much more valuable than the sum of its parts. Though the market doesn't understand it well at the moment it will likely come to appreciate it more as it grows and produces substantial FCF. Patience is key here.
$CART Moved forward its lock-up expiration date to 2/16 (Thursday) from the original 3/19. >65% of the shares will be eligible for sale. COO leaving, just announced a restructuring w ambitious guidance. Almost certainly did so to support the stock in advance of a secondary.
$YOU Delta just significantly expanded its Digital ID program. This service is free, more efficient than Clear and now available in Clear's core markets. Other majors will have to follow in order to compete on service. Seems like this could kill $YOU in pretty short order. https://t.co/tgfebZZCWK
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…
TransDigm’s sole-source aerospace parts generate roughly 70% aftermarket margins, with 90% of revenue tied to owned IP and 80% from…
Gaming and Leisure Properties raised AFFO guidance and dividends after Q2, trading at 10.2 times forward AFFO with an 80% payout ratio and…
Deckers Outdoor has fallen about 60% from its late-2024 peak and trades at 11x earnings as HOKA growth slows.
Intercontinental Exchange's valuation case rests on 5% Q2 revenue growth, a 61% adjusted margin and $100 million of MarketAxess synergies.
 Mike Zaccardi, CFA, CMT
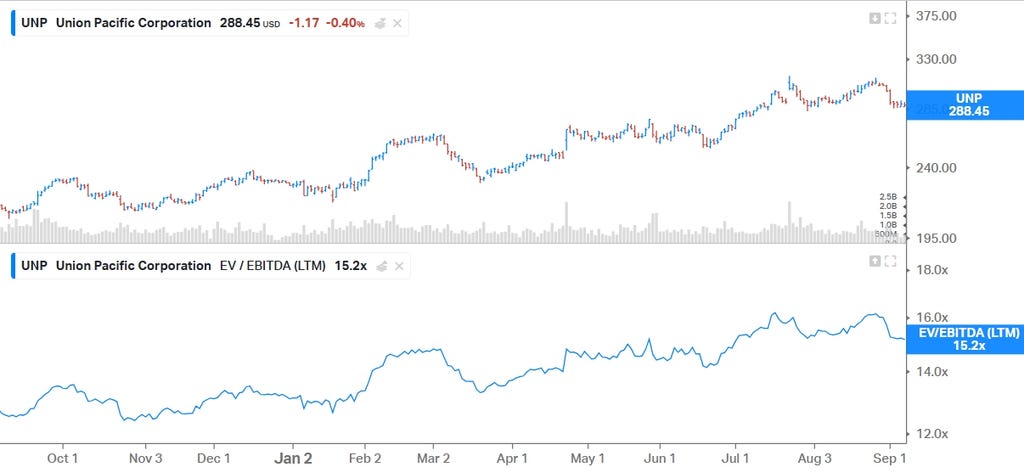
Union Pacific’s $85 billion Norfolk Southern merger pitch centers on a coast-to-coast rail network that cuts interchange delays and wins…
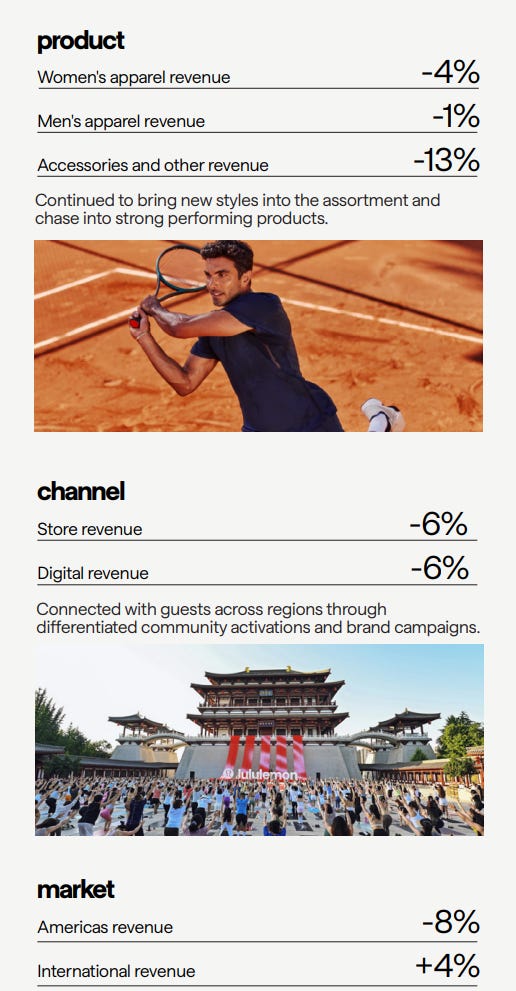
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel…
SoFi targets $4.75–$4.85 billion of 2026 adjusted net revenue as lending, loan-platform fees and cross-selling scale its financial-services…
 The Curious Analyst
 UHS · long
Universal Health Services is a profitable hospital operator whose $146 share price over-discounts an earnings-collapse scenario.
Ryan Tunis discusses P&C insurers, favoring Travelers over Chubb in a soft commercial market and calling AIG a near-book-value self-help…
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
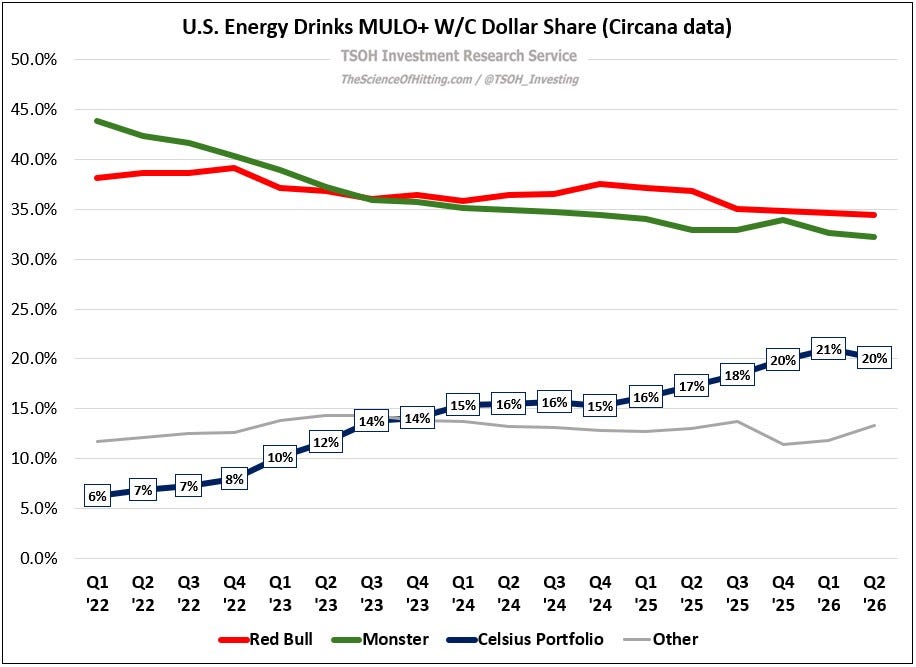
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
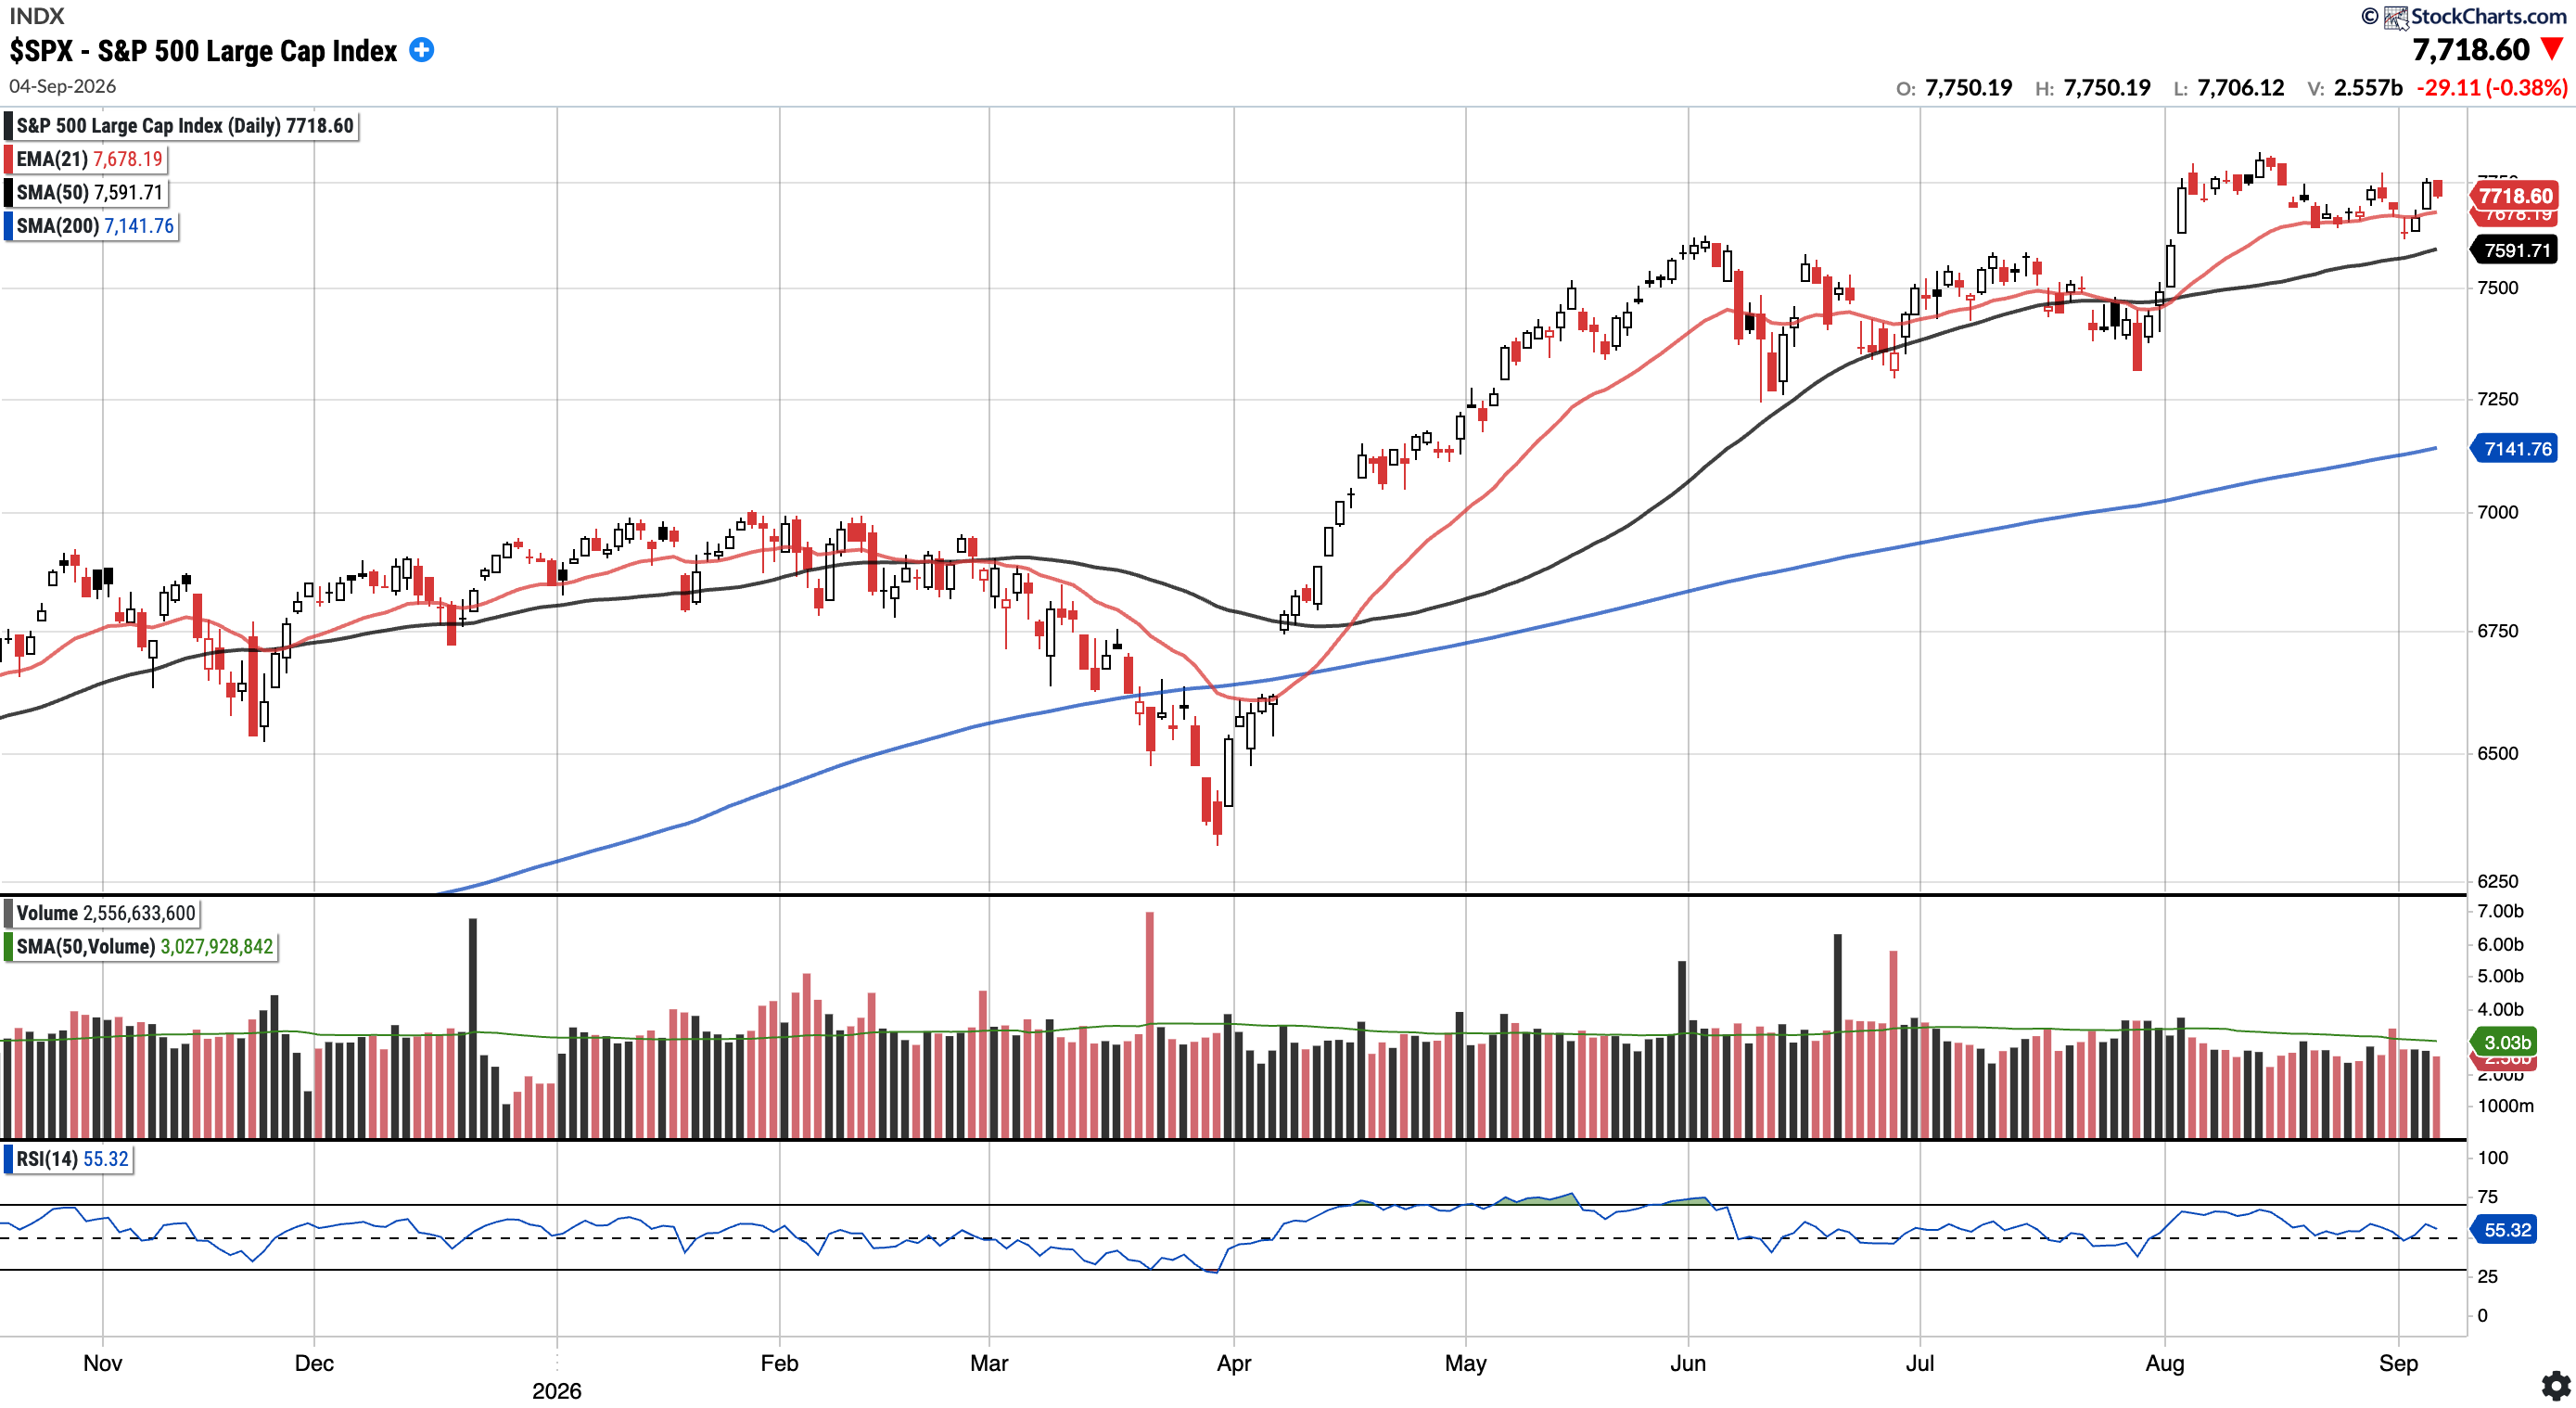
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
X-energy targets $1.8 billion in annual revenue and more than 42% gross margins by 2032 through reactor IP, project services and…
 Simple Investment Ideas 2 clicks
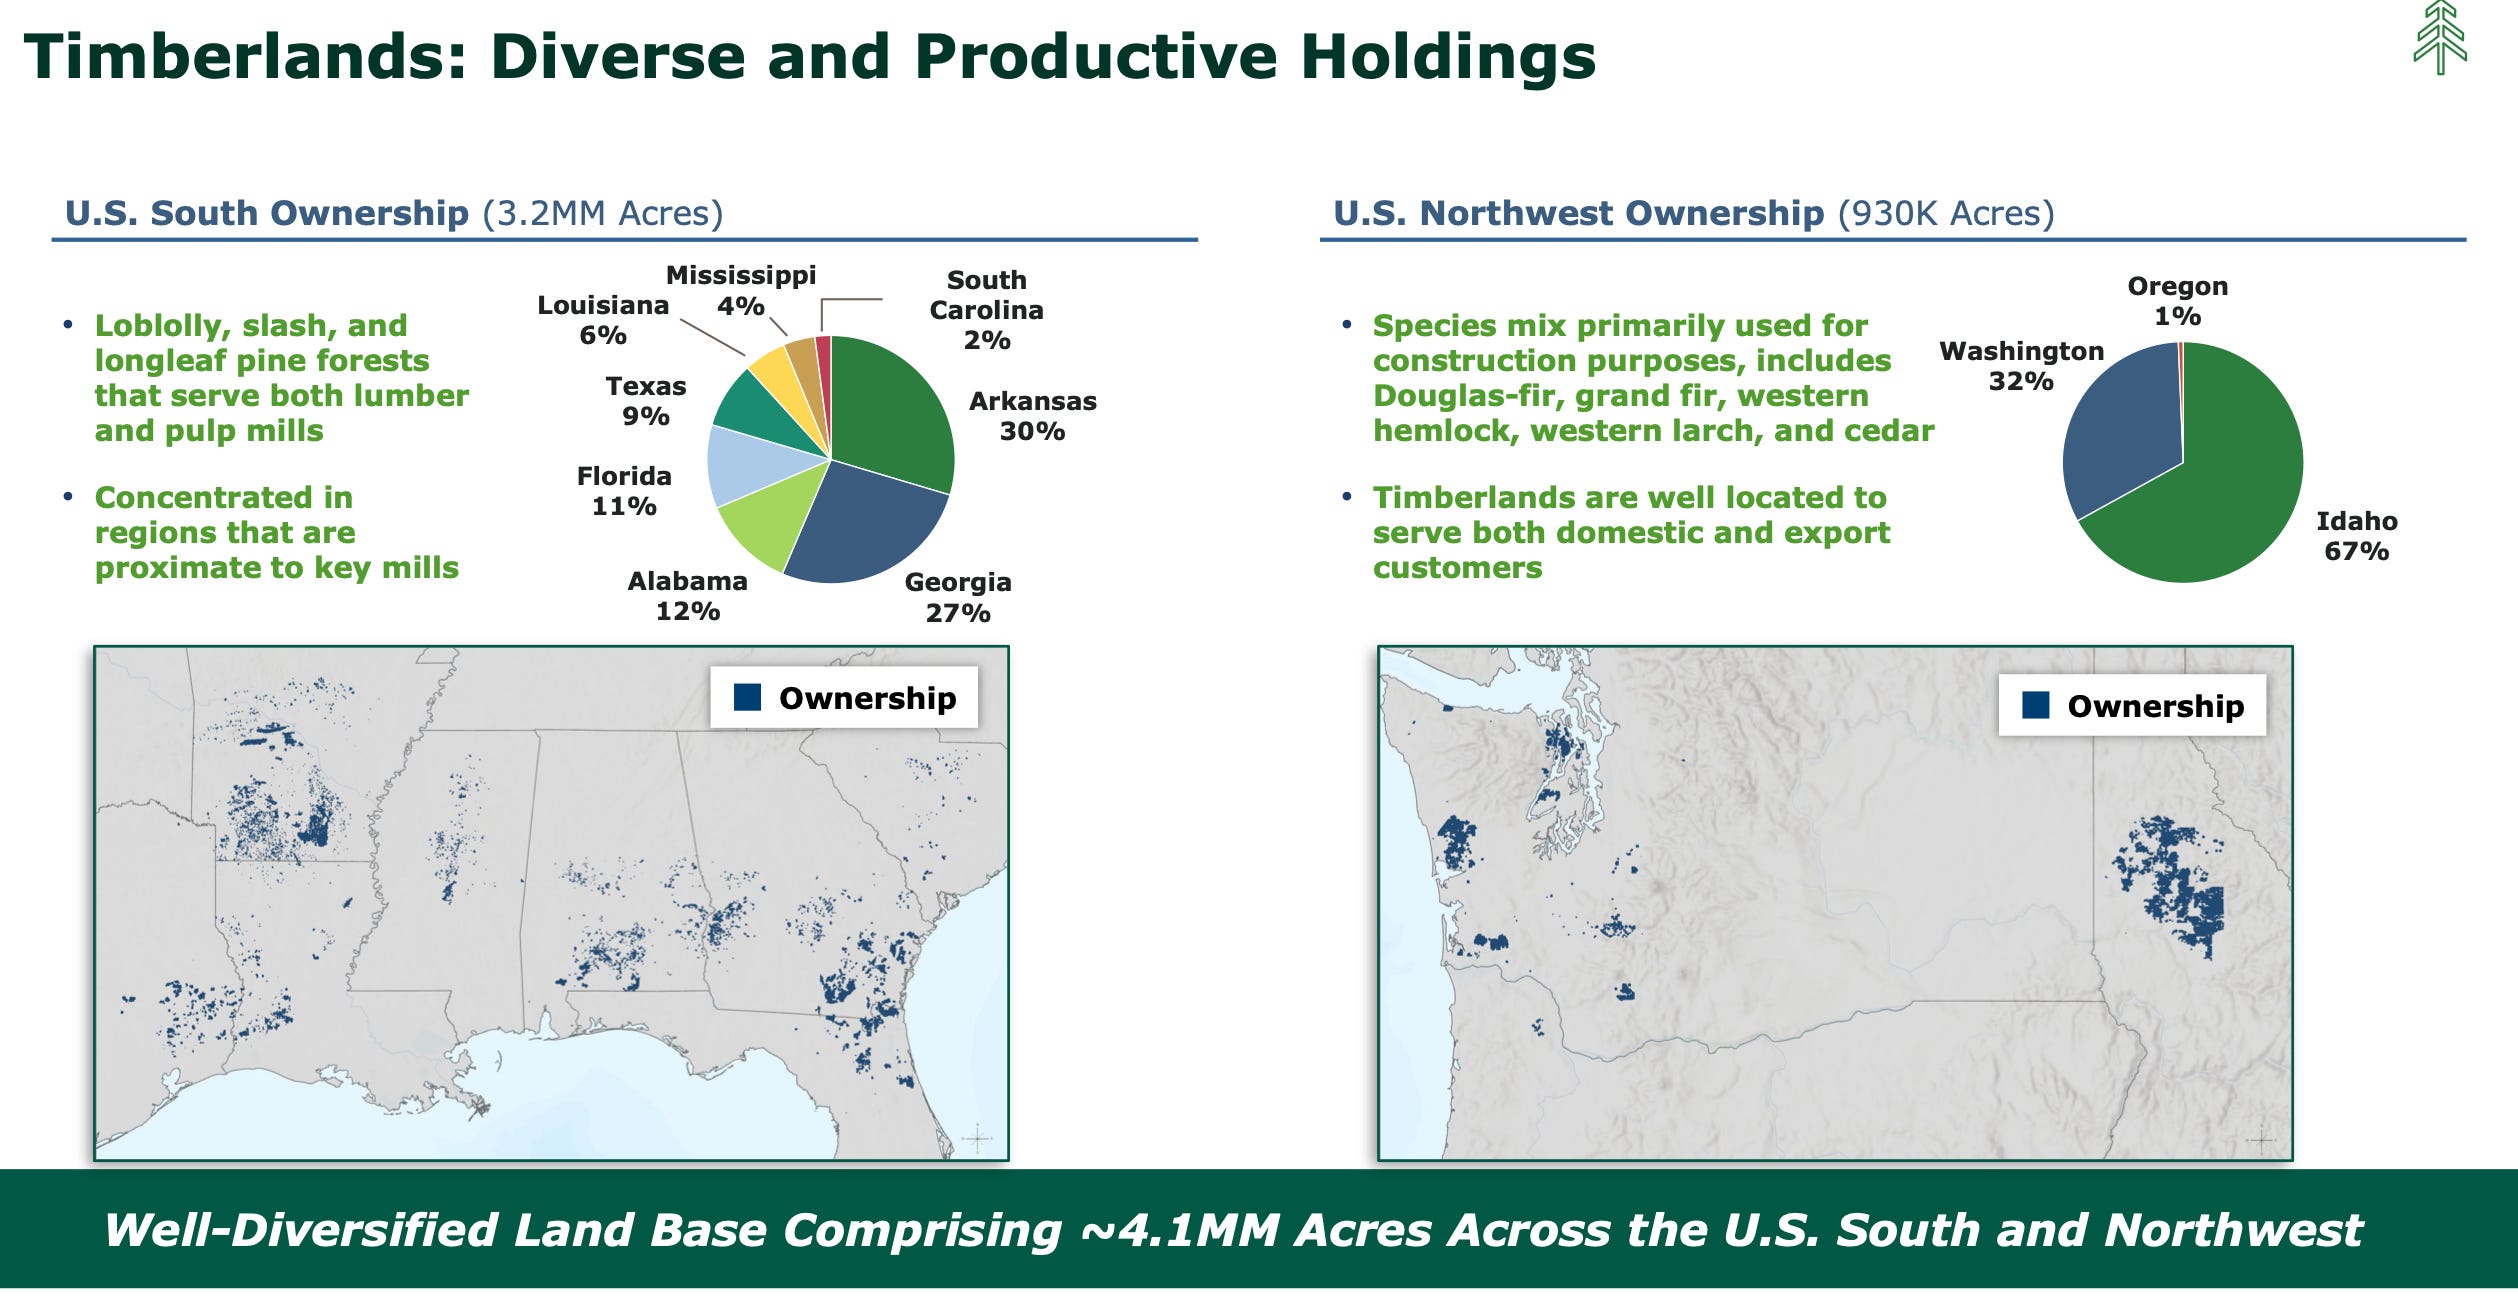
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
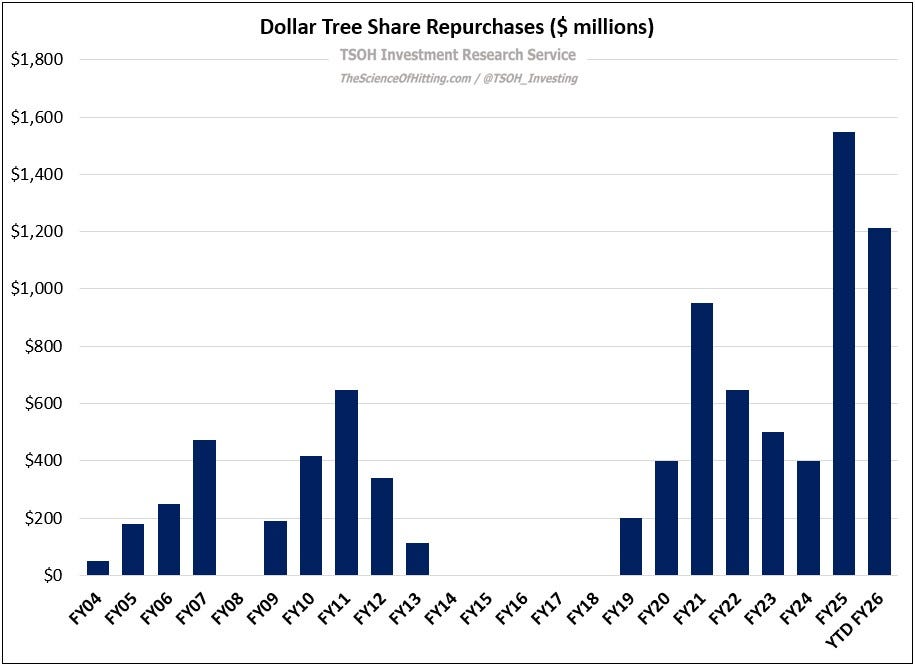
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Southwest Airlines is adding ancillary fees, assigned seating and premium products after a 6.7% Q2 adjusted operating margin, targeting up…
 Tim Dunn
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.