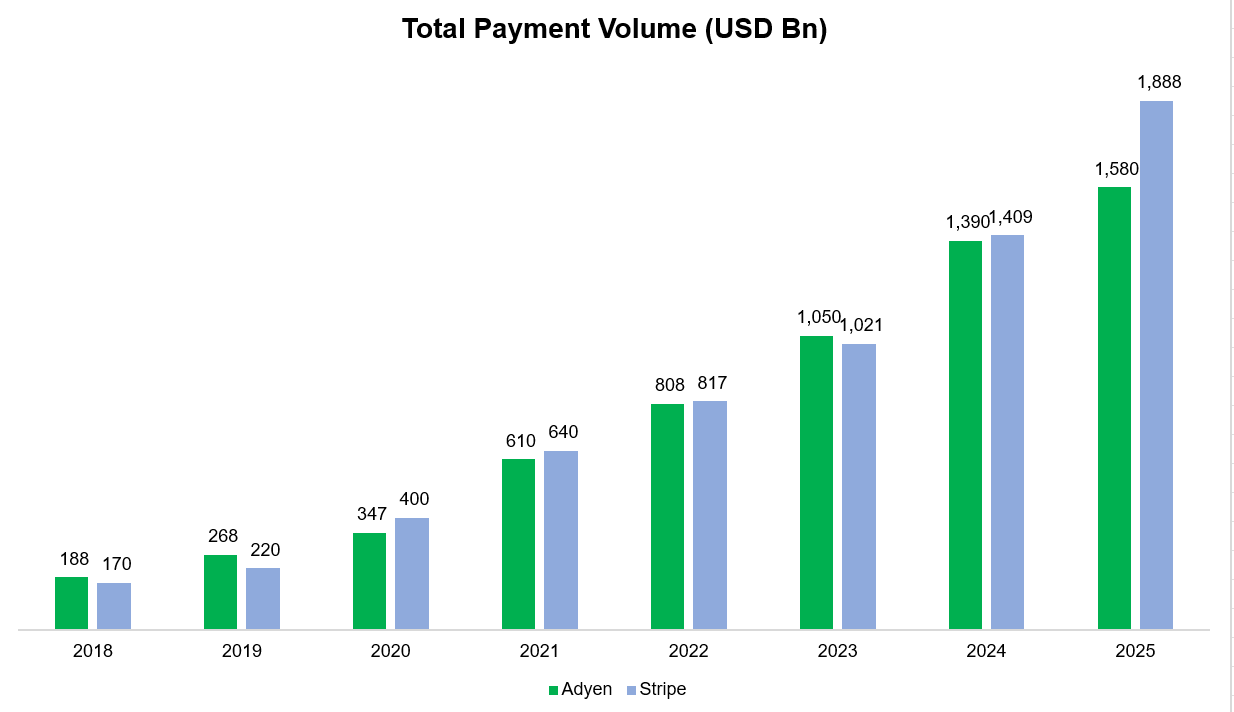
Stripe’s “Singularity” and the Divergence from Adyen
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including OpenRouter and Metronome.
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including OpenRouter and Metronome.
@JakeNapppoa4 i don’t look at price but currently long $BE
Whether it’s AI demand or player sentiment heading into the GTA VI release, you’ll never get to ground truth by lazily relying on what algorithms surface: copy/paste headlines and viral investor takes often driven by confirmation bias. Go to the source. Small accounts. Real people who actually consume the product, not those clouded by the trade. $TTWO
@TheValueist No, the best capital allocation for both $MU and $SNDK would be to either dividend back cash or sit on the cash until the cycle turns down. Buying back stock at around the peak of the cycle and at (give or take) 20x the value of their invested capital base is not smart.
 DKS 2026-08-22
DICK’S Sporting Goods trades at 12.8 times FY26 EPS after breaking multi-year support, while maintaining $13.50 to $14.50 FY guidance amid…
 Mike Arnold 2 clicks

IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…
Zoetis’s U.S. companion-animal revenue fell 6% as dermatology competition drove rebates and discounts, pushing full-year net pricing to…
Copart faces a near-term lift from pricier AV repairs and total losses, but shrinking accident volumes could eventually force its…

GFL’s proposed acquisition of Secure follows 19% revenue growth at Secure and 14.8% EBITDA growth at GFL, with Permian produced-water and…

Glenn Schorr and Ken Worthington discuss risks in private-credit software loans, agentic AI at retail brokers, crypto use cases and bank…
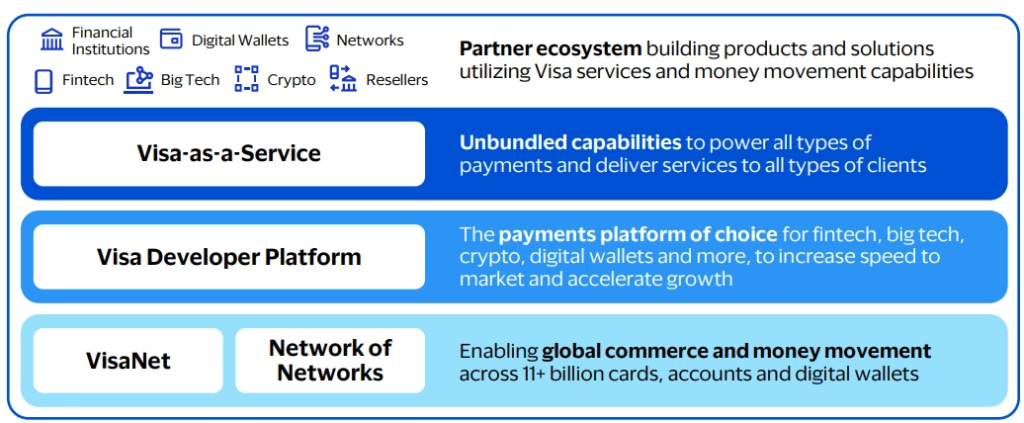
Visa and Mastercard have absorbed digital wallets and BNPL into their networks, using global merchant acceptance to turn supposed…

Steve Eisman reviews SpaceX earnings, AI capital spending’s drag on free cash flow, Meta’s struggles, and the collapse of Situational…
 GLXY · long
Galaxy Digital (GLXY) is presented as a long investment idea.
LVMH’s 2025 revenue fell 5% and operating profit 9% amid forex and luxury weakness, while Fashion & Leather Goods improved in the second…

Coupang’s former strategy VP discusses Taiwan expansion, 1P-versus-3P economics, margins and competitive risks as CPNG trades 35% below its…
Uber’s $50 billion revenue and $4.5 billion operating profit reflect a turnaround from years of subsidy-heavy growth, with autonomous…

Fair Isaac raised FICO Score royalties from roughly $0.50–$0.60 in 2022 to $4.95 in 2025, drawing regulatory scrutiny over its…

MercadoLibre’s Daniel Wu discusses MELI’s Latin American e-commerce operations, fintech business model, growth opportunities and risks on…

Brookfield faces whistleblower allegations over its VC funds; $569 million of Q1 buybacks challenges claims that $8 million of remaining…
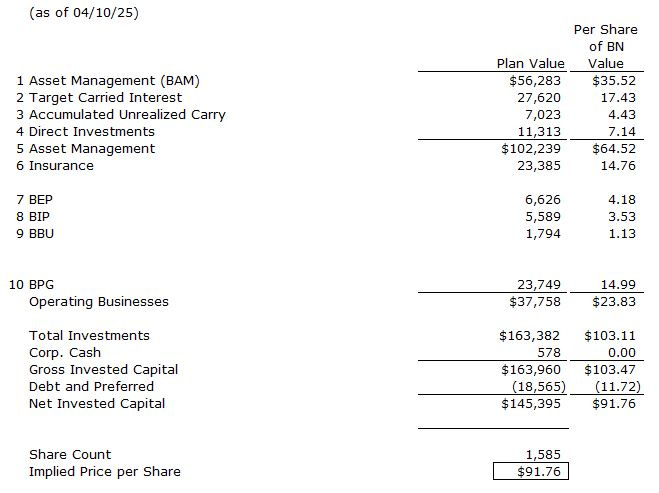
Brookfield Corp. trades at 13.2x 2025 distributable earnings and $45.97 against management’s $91.76 sum-of-the-parts Plan Value, discounted…
ICBC’s chairman describes embedding Chinese Communist Party leadership, anti-corruption campaigns and Xi Jinping Thought into governance at…

Alnylam’s 2022 50% phase-three gain faces FDA advisory-panel scrutiny over its amyloidosis drug’s label extension.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.