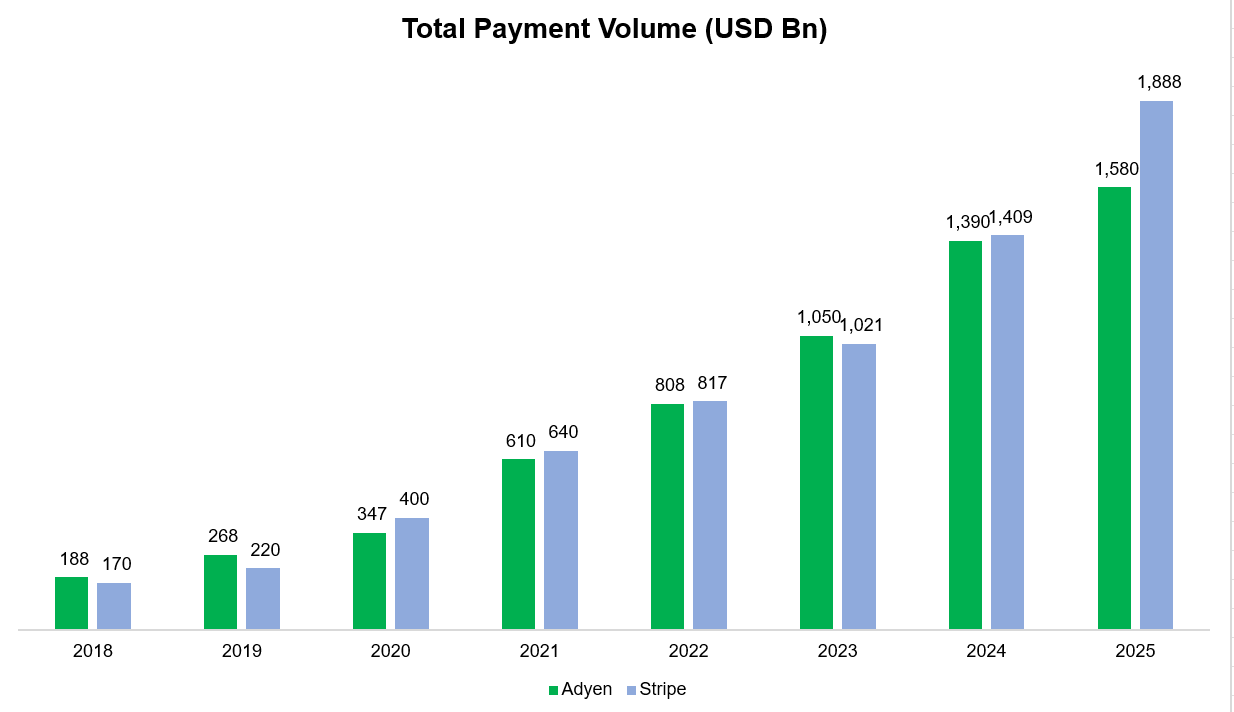
Stripe’s “Singularity” and the Divergence from Adyen
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including OpenRouter and Metronome.
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including OpenRouter and Metronome.
$PLUS Earnings on 8/5, expectations & stock disconnected from reality. Suppliers ($CSCO – 50% of product sales), competitors & customers all reporting sharp sales declines. Non-event PR today re a service they’ve been offering for 3 yrs is pumping stock; suggests mgmt is grasping
@Mike10947310 $CVGW Sources >90% of its avocados from Michoacan, MX. $CMG purchases ~10% of tot US avocados. Its latest ESG report noted “diversifying away from Mexican suppliers.” This latest drama down there will almost certainly accelerate sourcing away from $CVGW, etc.
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
 NVDA 2026-08-22
Nvidia’s exclusive SpaceX partnership targets a 10 GW data-center buildout and could add $120 billion to $230 billion of revenue beyond…
 Uttam Dey 2 clicks

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
BAC 2026-08-20 Bank of America’s BAC.PR.B yields just over 6% near par, while discounted lower-coupon series such as BAC.PR.P offer better value despite…
 Prakhar Agarwal, CFA 1 click
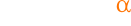
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
APP 2026-08-19 AppLovin’s AXON 2.0 self-serve rollout, e-commerce onboarding and Connected TV expansion aim to revive growth after Q2 2026 revenue and…
 KL Research 1 click
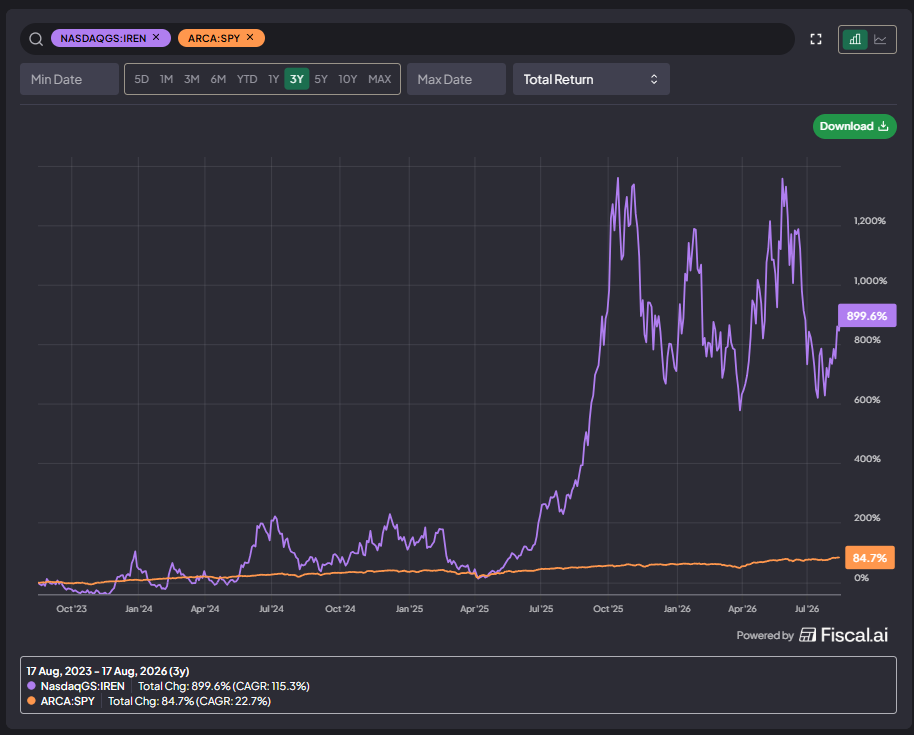
IREN awarded each co-CEO roughly 9 million RSUs, about 2.5% of shares and $400 million, in exchange for no further equity grants until…

Nubank's 140 million customers, 20% efficiency ratio and 30% ROE frame whether its high-teens P/E reflects a scalable fintech or a maturing…

Hyperscalers’ off-balance-sheet lease and purchase obligations rose from roughly $1 trillion to $1.5 trillion, turning the AI buildout into…
HubSpot trades near its 2020 share price despite quadrupled revenue and $750 million in free cash flow, with Breeze AI upside weighed…
 JBTM · long
JBT Marel is an enduring food-equipment business with low AI risk, automation upside and favorable GLP-1 exposure.
FUTU 2026-08-23 Futu Holdings' Q2 funded accounts rose 33.6%, client assets 43.6% and net income 41.6% as it shifts from mainland China toward Singapore,…
 Emanuel Nemec 4 clicks
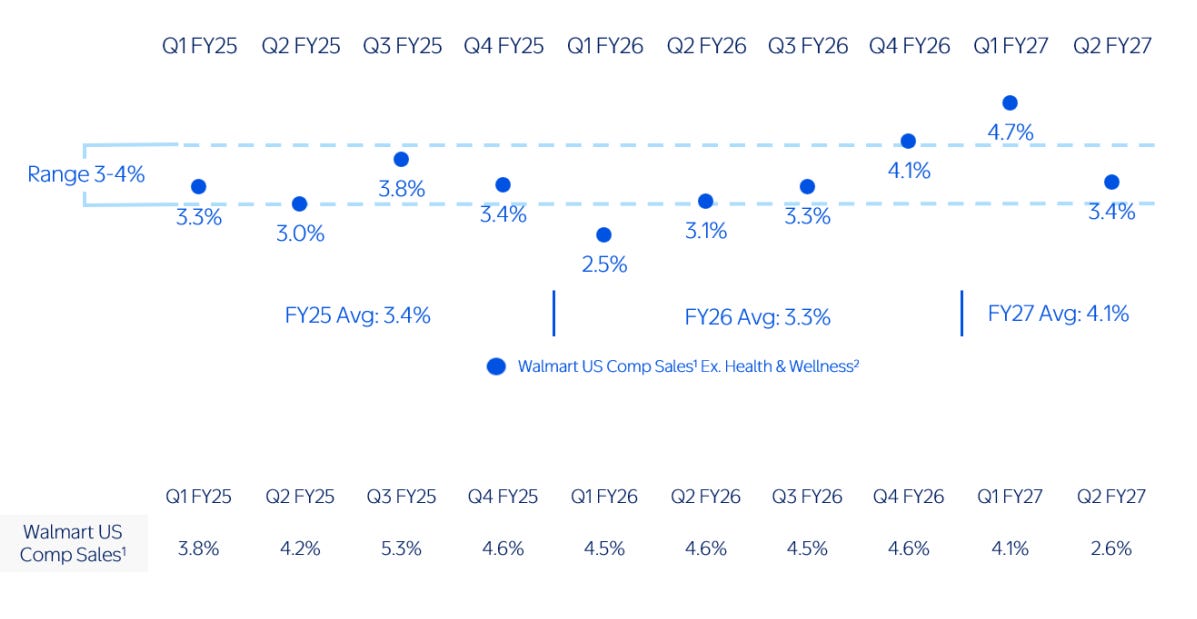
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes…
PLTR 2026-08-21 Palantir’s revenue rose 93% to $1.94 billion as U.S. commercial bookings jumped 149%, lifting GAAP operating margin to 47% and free cash…
 Quantryon Capital 1 click
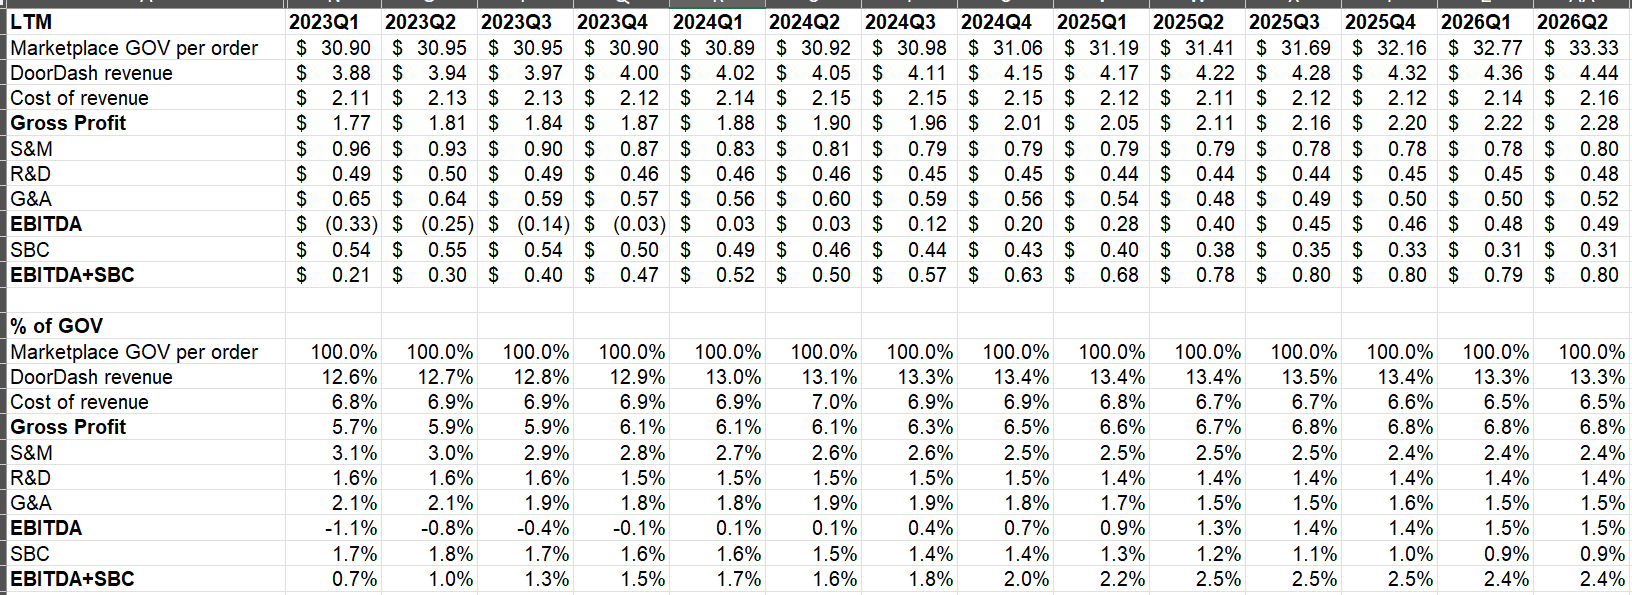
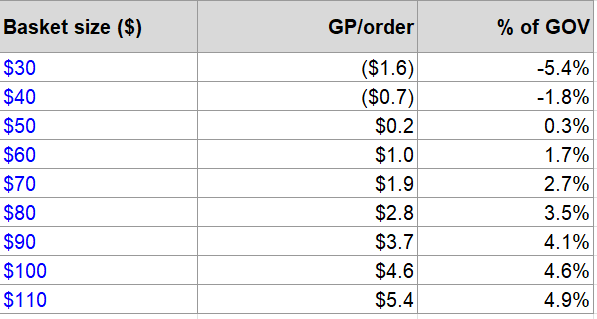
Instacart’s per-order unit economics provide a benchmark for assessing DoorDash’s LTM profitability and operating model.
NBIS 2026-08-20 Nebius posted 454% revenue growth and a 41% EBITDA margin, while Meta’s $27 billion agreement supports its AI infrastructure backlog.
 The Quality Growth Investor 2 clicks
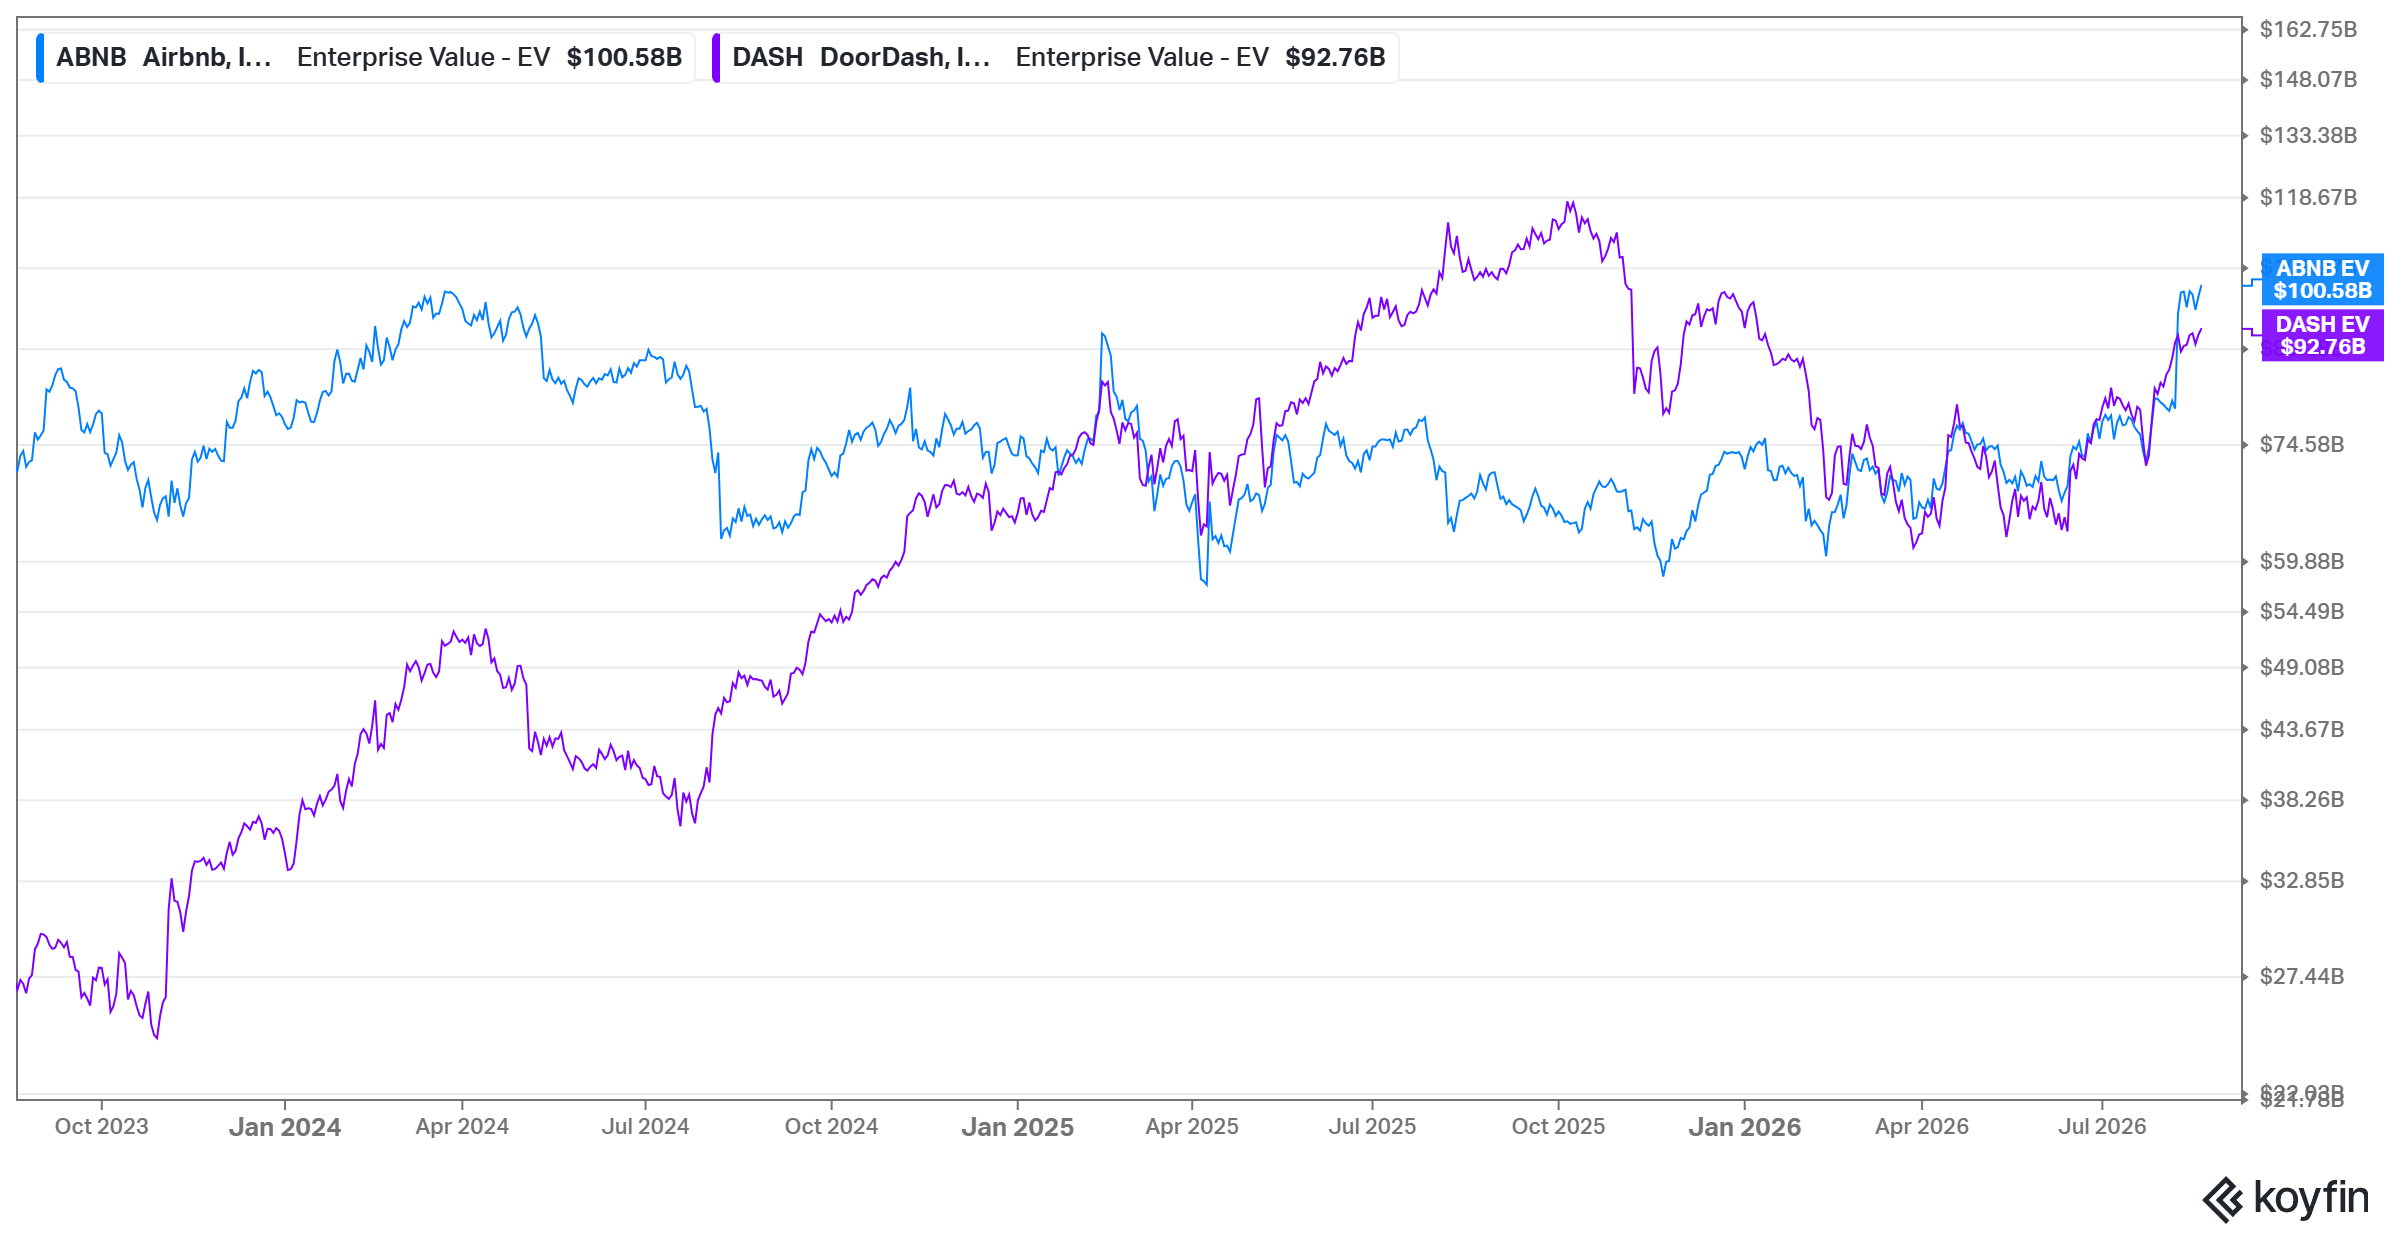
Airbnb shares have risen about 50% since October 2025, prompting a revised 2026 model and return assumptions at the current price.

Steve Eisman argues the AI boom hinges on Anthropic and OpenAI’s importance to hyperscalers, while weighing software, CoreWeave and Cisco…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
Macy’s and Kohl’s face renewed short cases as their recent reratings ignore fading store-refresh gains, credit-card earnings exposure and…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang Prakhar Agarwal, CFA
 PV Research Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.