Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
S Stock Thoughts 1 click
Lesaka’s executive chairman has invested more than $10 million personally and targets EPS compounding above 40% through consumer, merchant…
S Mispriced Assets 2 clicks
VersaBank's Q3 revenue rose 23% and adjusted net income 27%, while a 2.19% net interest margin and 19.15x forward earnings temper its 2027…
SA  Grassroots Trading
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
S Latticework by MOI Global 2 clicks
Pyxis Oncology's recent financing extends MICVO's runway to clinical milestones as the oncology candidate works to establish a safe,…
SA  Myriam Alvarez 2 clicks
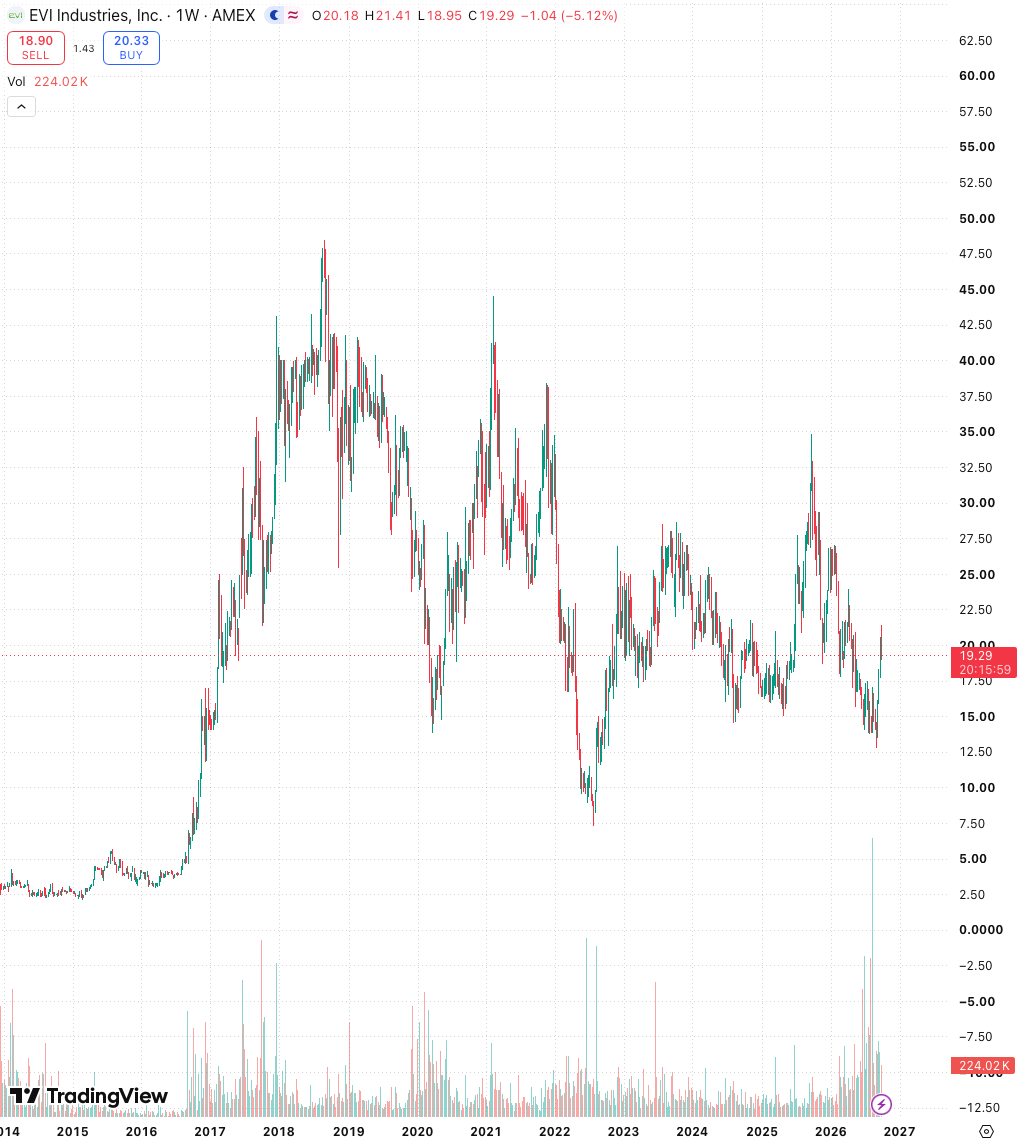
EVI Industries says its ERP and service-platform build is largely complete, testing whether 10.8% revenue growth can finally outpace…
S Kairos Research 2 clicks
Huckleberry.AI trades near $3.30 against $221 million of cash and $900 million-plus of NOLs after selling its operating business, creating…
S Hidden Rock Capital's Newsletter 4 clicks
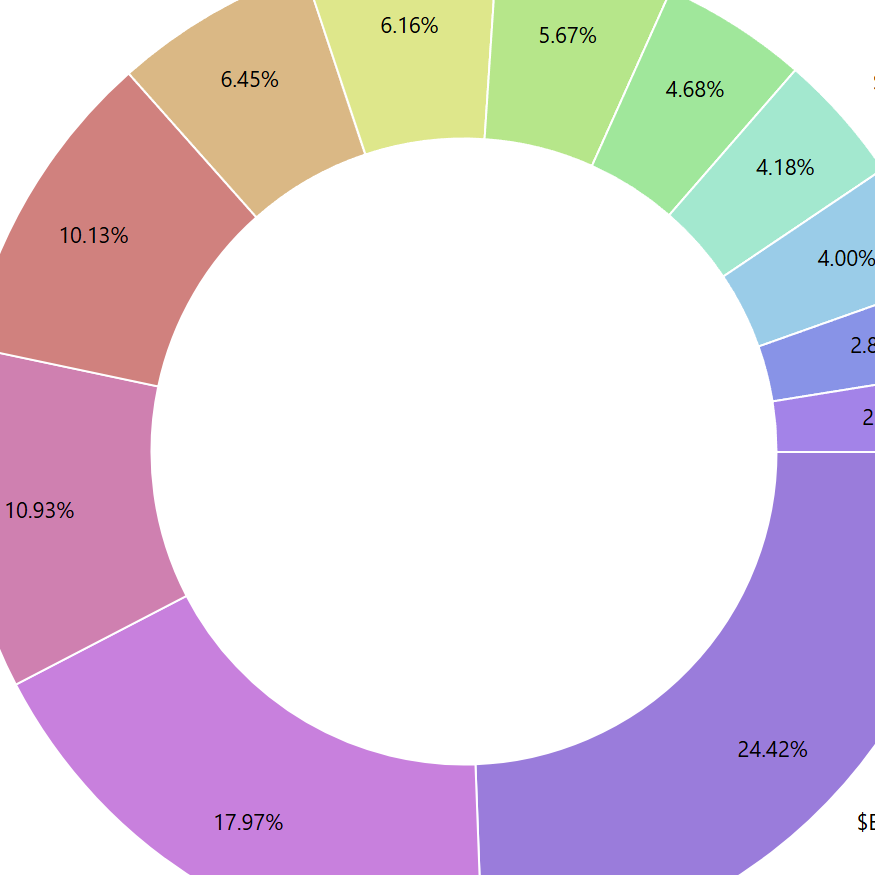
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
S The Mikro Kap 1 click
Washington Trust Bancorp offers a 5.8% dividend yield, with C&I loan growth supporting ROE despite 40% commercial real estate loan…
SA  Sorrento Research
Zentek shipped its first ZenGUARD air-filter order to a Canadian federal facility as its Albany graphite PEA confirmed a US$3.85 billion…
BL Atrium Research - Equity Research 1 click
 ZOOZ · long
ZOOZ Strategy trades at a roughly 37% discount to the market value of its Bitcoin holdings and cash on a fully diluted basis.
BL Value Investors Club 2 clicks
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…
S Calvin Blissett 4 clicks
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
S Triple S Special Situations Investing
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
Riley Exploration Permian raised oil production guidance after a Q2 beat, targeting 30% growth while trading at 6.52 times forward earnings.
SA  The Supercycle Investor
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
S Substack von Philipp 7 clicks
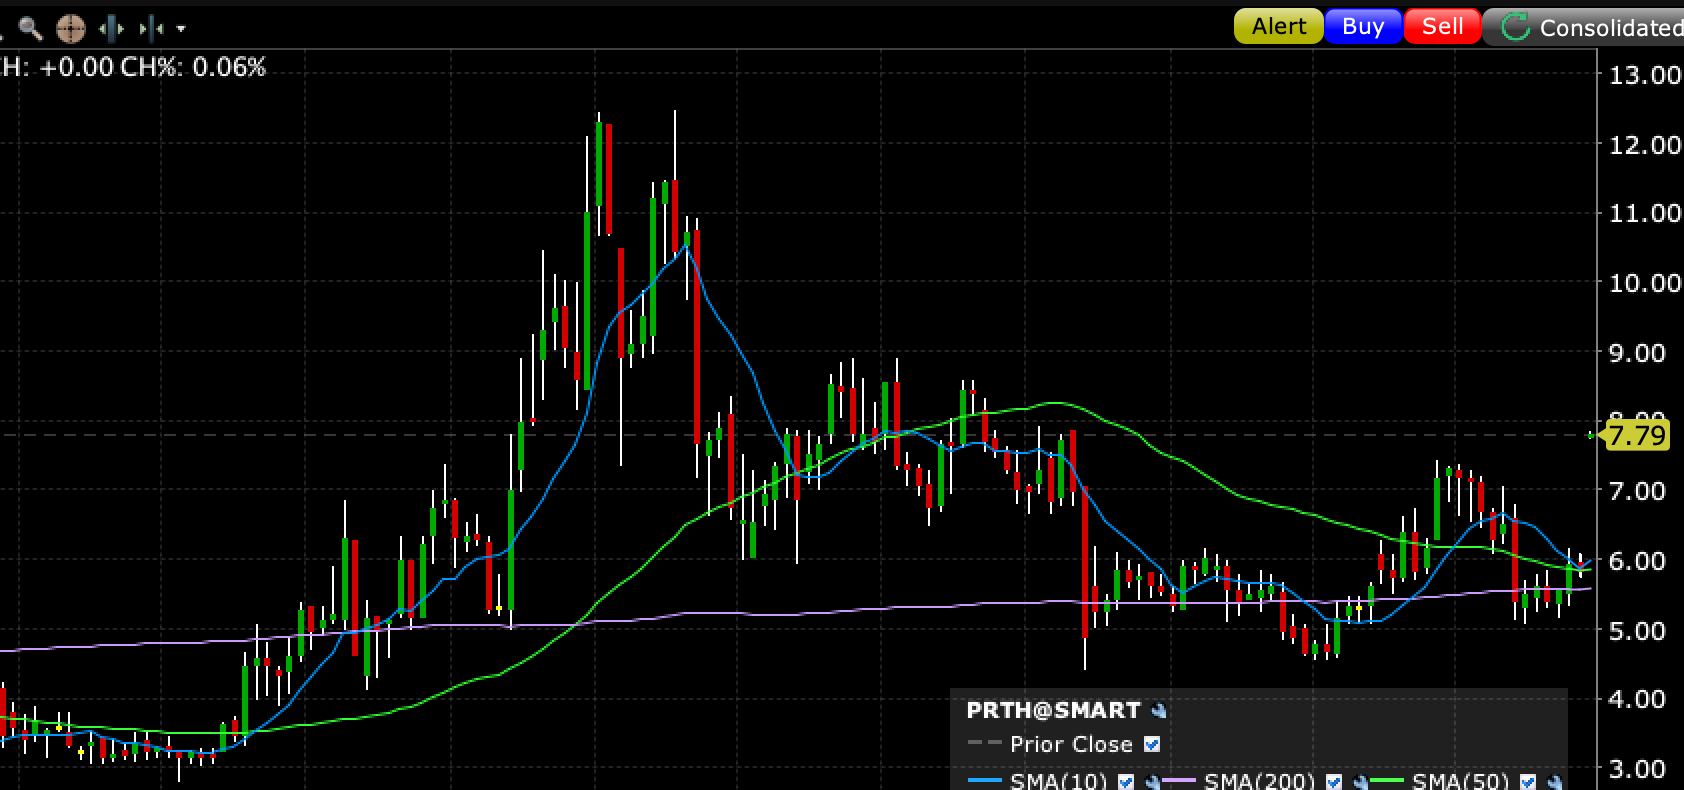
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
S Nat Stewart - Stock Picking Newsletter 8 clicks
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
S WHAT ARE WE DOING? “Contrarians At The Gate” 1 click
IEH booked $3.6 million in mobile-defibrillator connector orders, lifting its medical revenue outlook and diversifying beyond aerospace and…
BL Atrium Research - Equity Research 7 clicks
EuroDry shares rose more than 300% year to date as dry bulk markets strengthened, but an aging fleet, no dividend and a $20 million equity…
SA  Henrik Alex 4 clicks