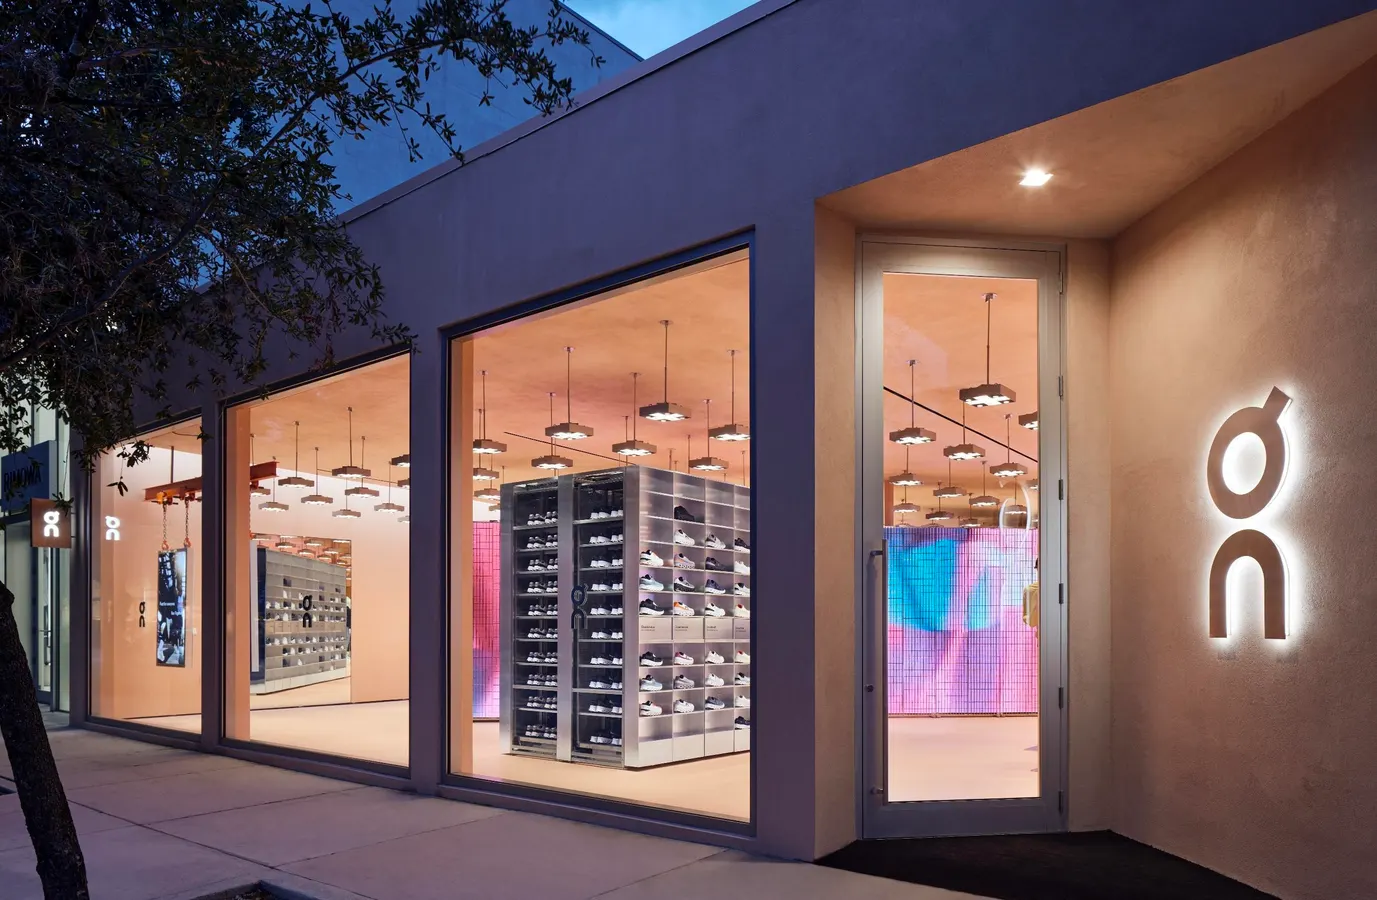
New Position (ONON): Game is On
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S. consumer weakness and China growth.
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S. consumer weakness and China growth.
S&P earnings expected to increase 27% in Q3 (slight decel from Q2). Chopping that growth up a few ways (H/T to GS’s Tony P): -->80% of growth expected to be driven by tech and energy -->Half the growth driven by AI infrastructure names -->1/3rd of the growth driven by $MU and $NVDA alone Headline 27% eps growth estimates not quite as healthy as they appear
$FRVO price drops from ~$31 on Jun 26 to ~$13.50, and now they publish a short report? https://t.co/57Dy0iV2lE
$SMCI is a SpaceX pick-or-shovel? https://t.co/iPapUcZbMh
Just sold a couple positions that have been frustrating me for a couple years ($GBFH and $AERG). They'll probably moon now, but feels liberating.
What you need to know about the $BRUN news. https://t.co/ltboFSZJhC
Intuit’s $21.4 billion software franchise faces AI-driven pricing pressure in tax and accounting, even as QuickBooks and TurboTax retain…
Capitol Federal Financial's 2.31% net interest margin and $23.6 million Q3 profit support its shift toward higher-yield commercial lending,…
 Growth Stock Hunter
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Uber’s valuation is framed as undervaluing ride-hailing and robotaxi growth, while record institutional ownership offsets concerns over…
 The J Thesis 3 clicks
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
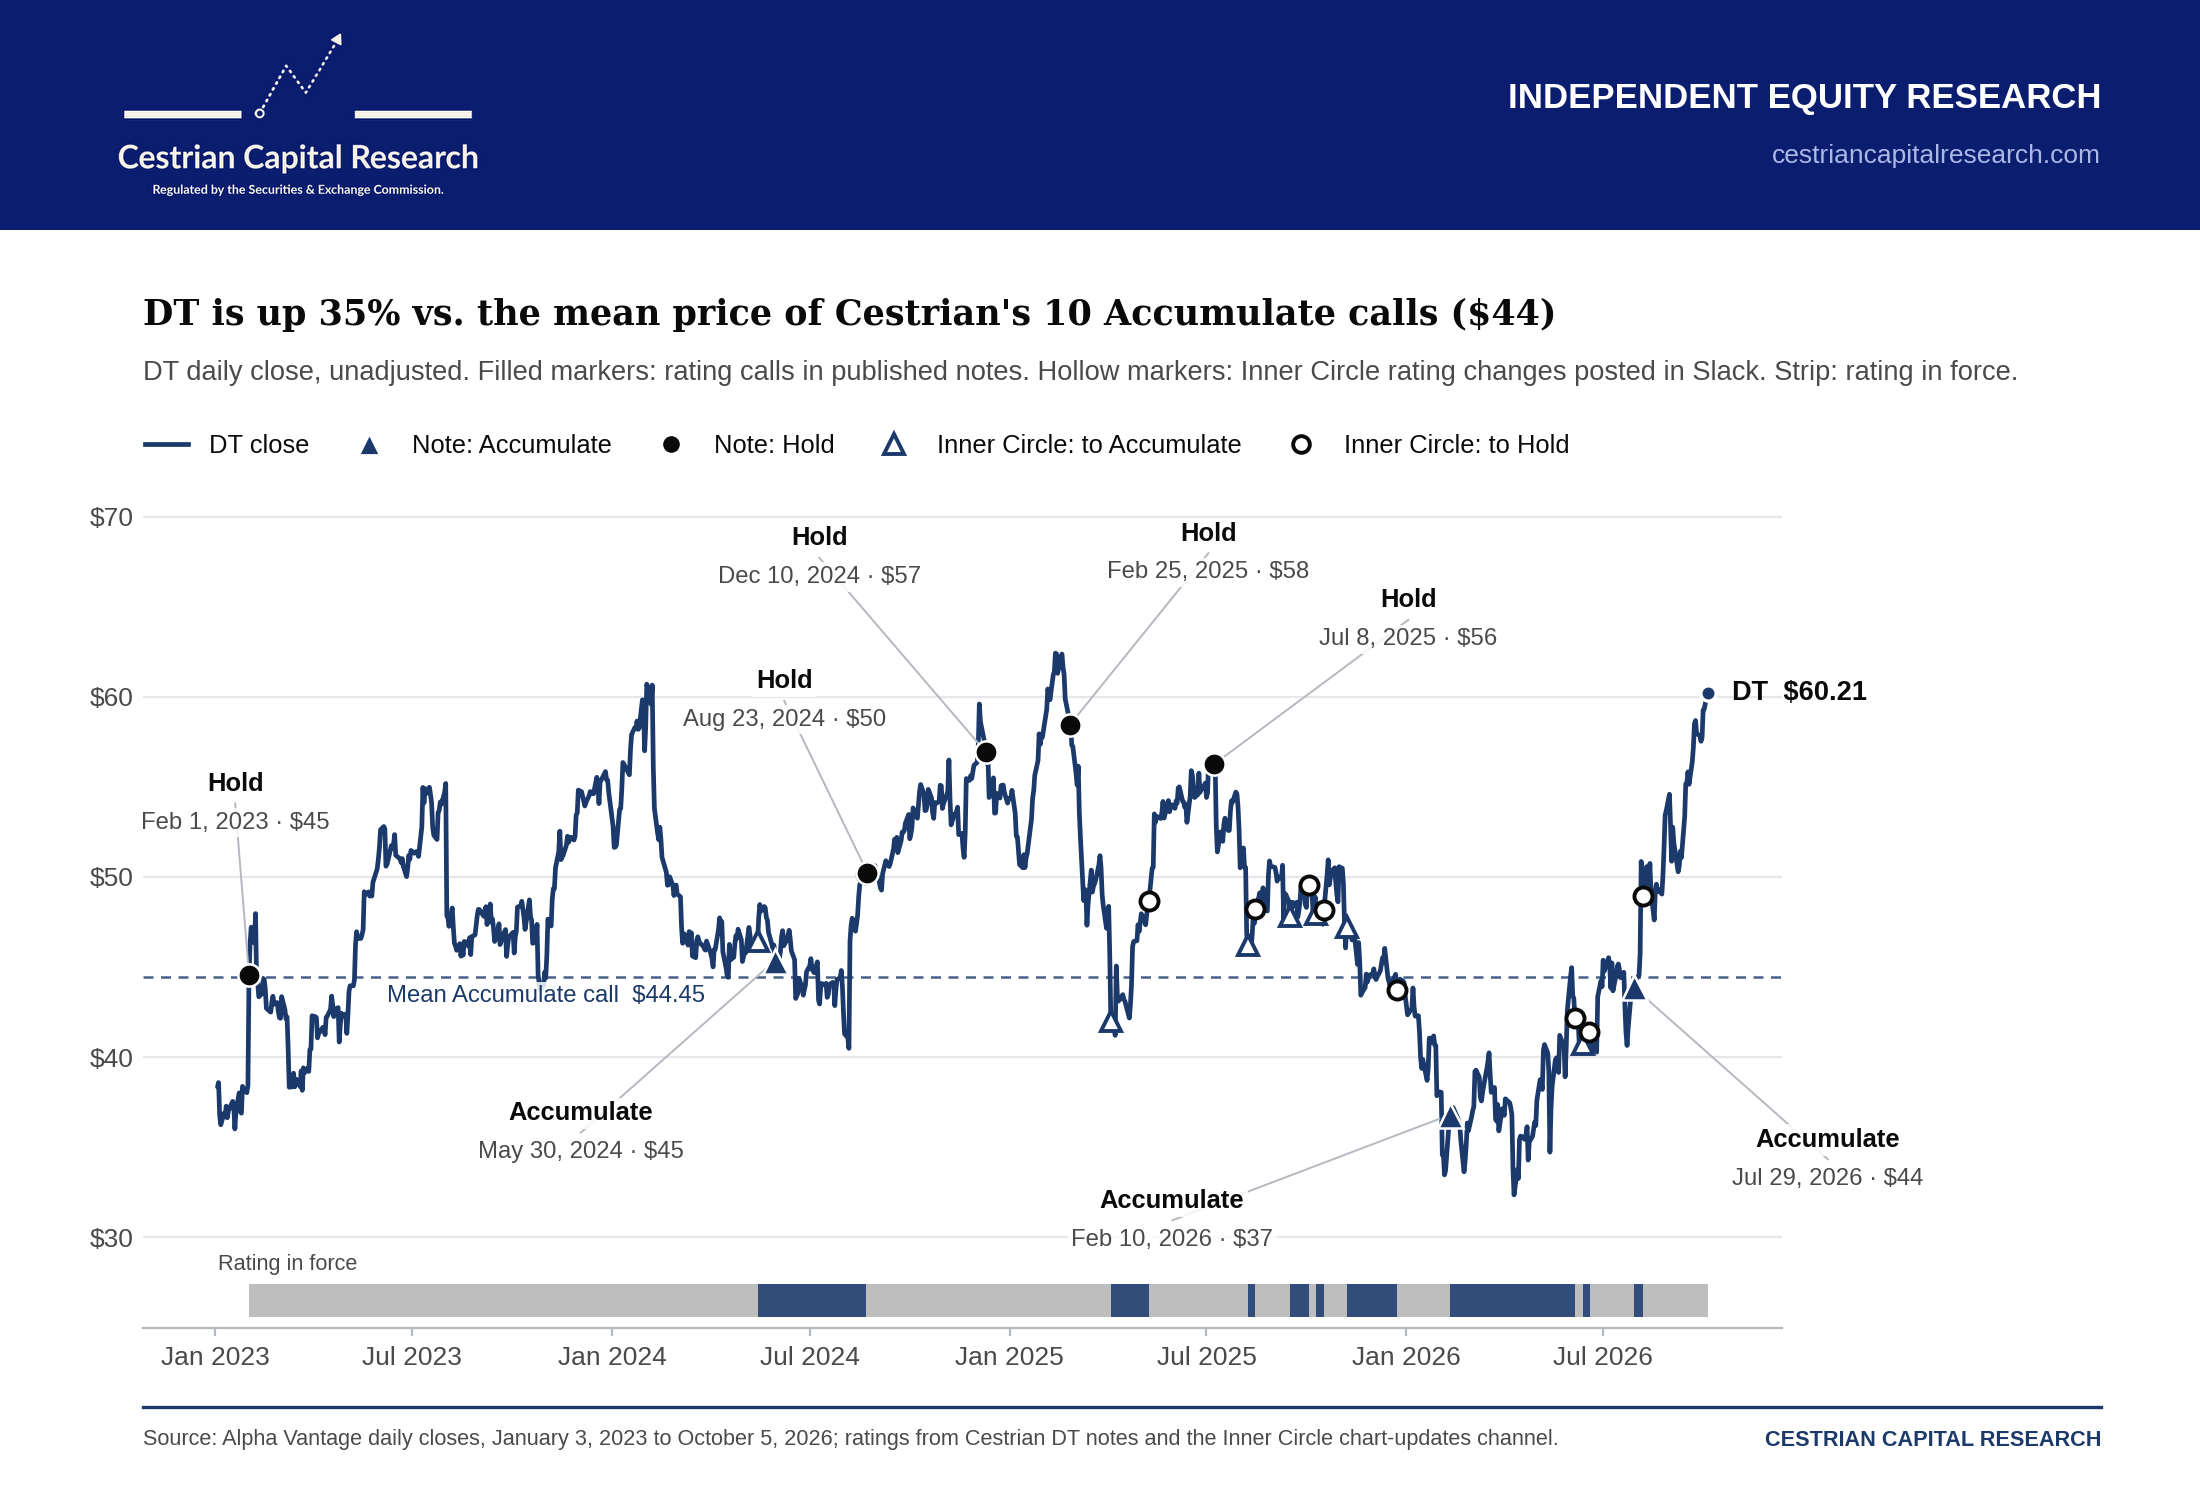
Dynatrace is rated Distribute after a 90% rally to $60.21 nears $62 resistance, while revenue and RPO growth decelerate ahead of November…
Nebius gains preferred sovereign infrastructure status for Palantir’s enterprise AI stack, using its customer base to accelerate modular…
 Petri Dish Reports 3 clicks
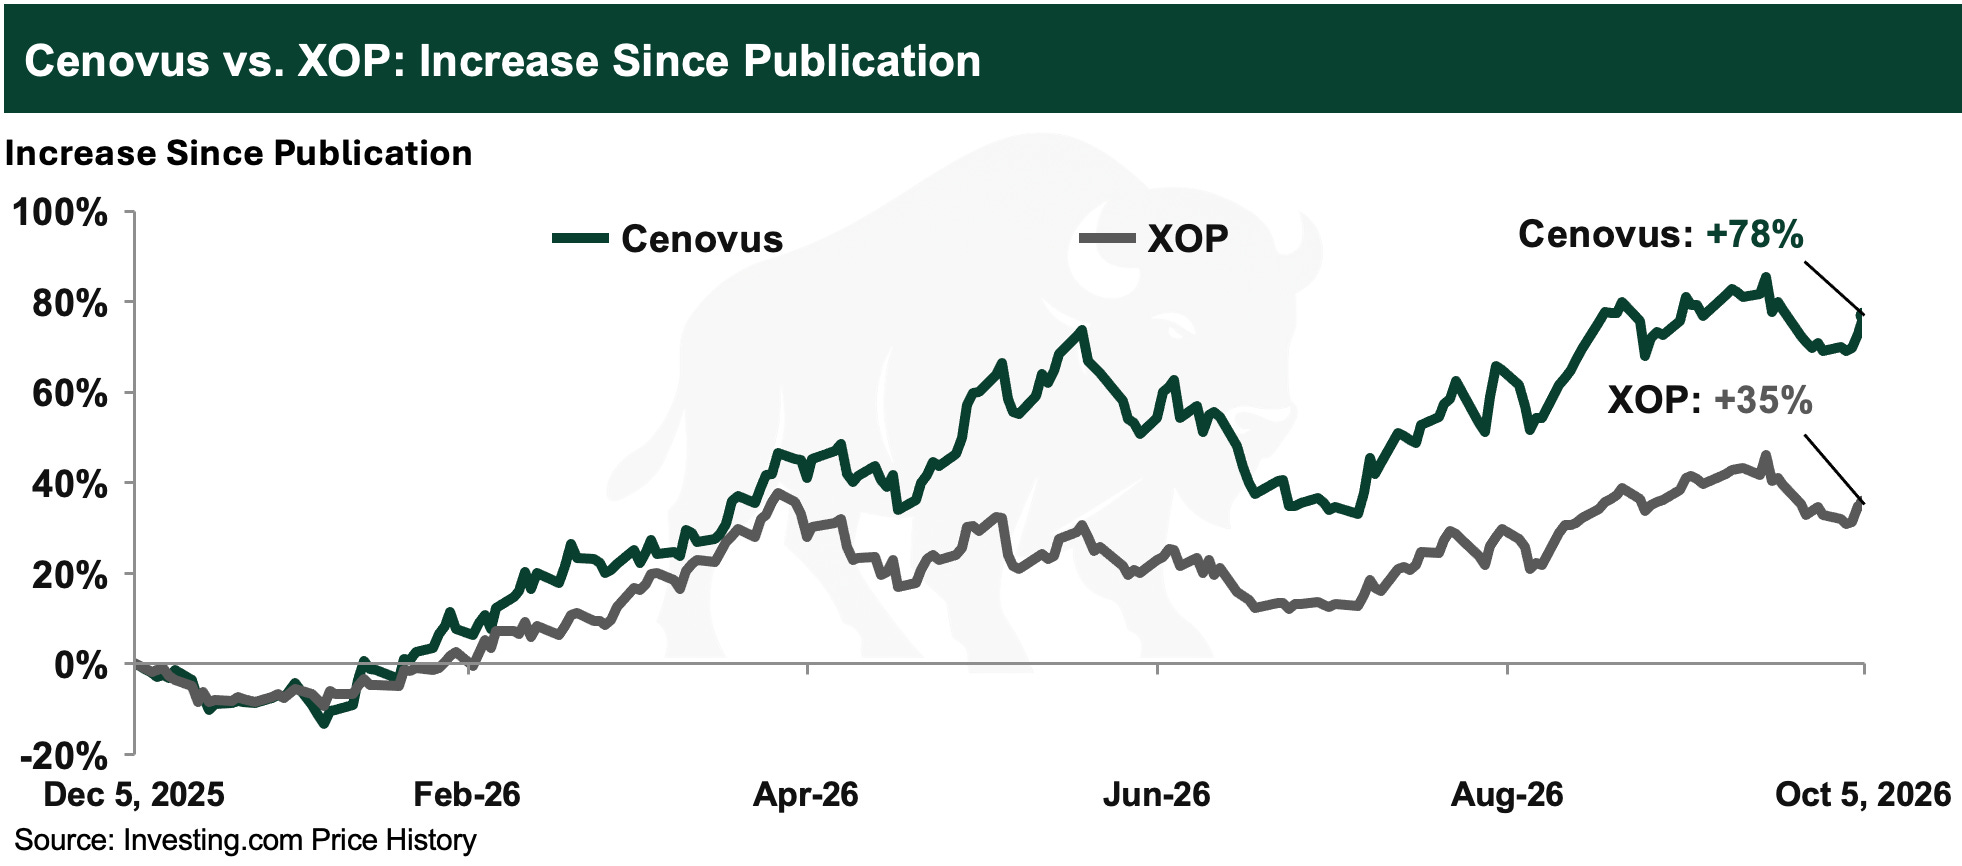
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
Canterra Minerals increased Lundberg indicated tonnage 55% to 26.1Mt, with 226.2Kt of contained copper equivalent, supporting a Buchans…
Franco-Nevada bought 10.0 million Kenorland shares, a 12.4% stake, for C$22.2 million in a secondary transaction that issued no new shares.
 ZOOZ · long
ZOOZ Strategy trades at a roughly 37% discount to the market value of its Bitcoin holdings and cash on a fully diluted basis.
GFL Environmental’s take-private bids reportedly fall within $50 to $55, with a top-of-range offer likely needed to secure shareholder…
Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…
 Quad 7 Capital 2 clicks
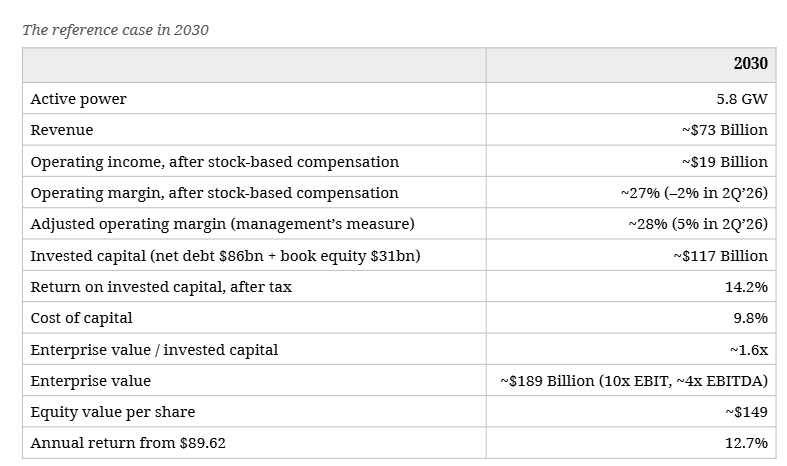
CoreWeave’s compute-selling economics face a narrowing margin of safety if new capacity closes today’s AI supply-demand gap.
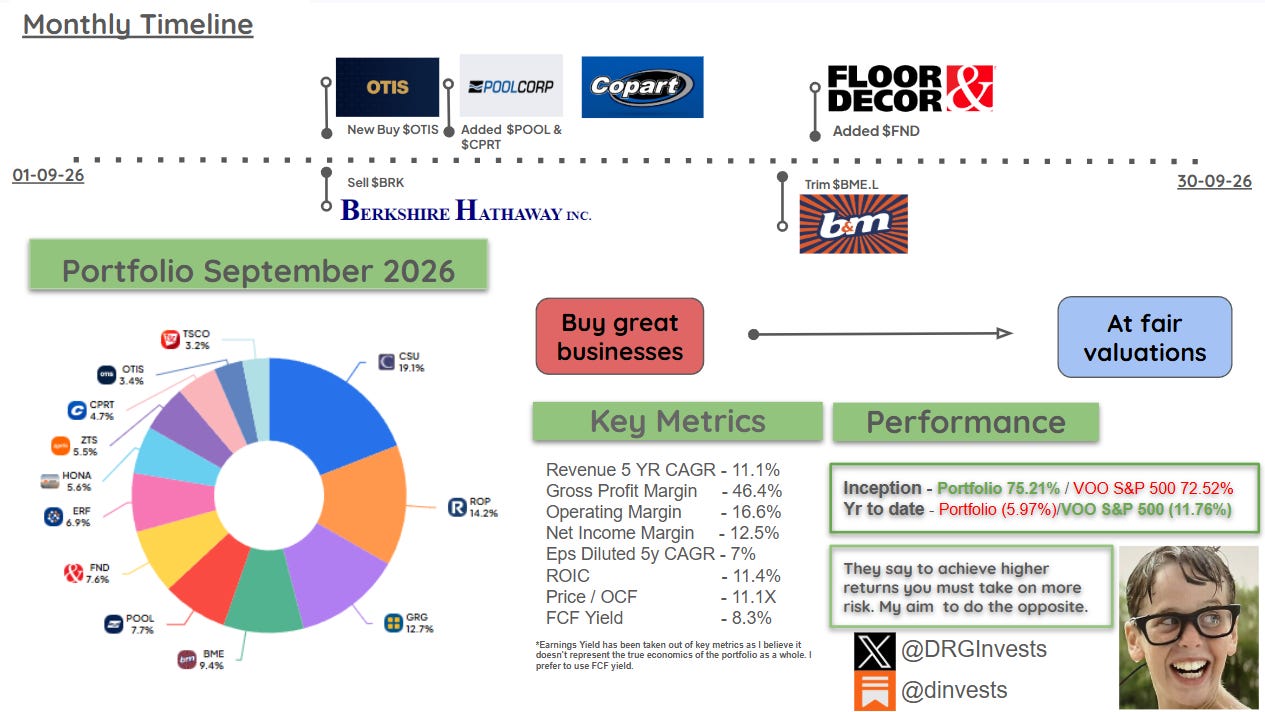
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Ciena’s optical networking equipment sales to stronger telecom customers underpin a 2027 long thesis, unlike its 2000-era boom.
 Marc Gerstein 2 clicks
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
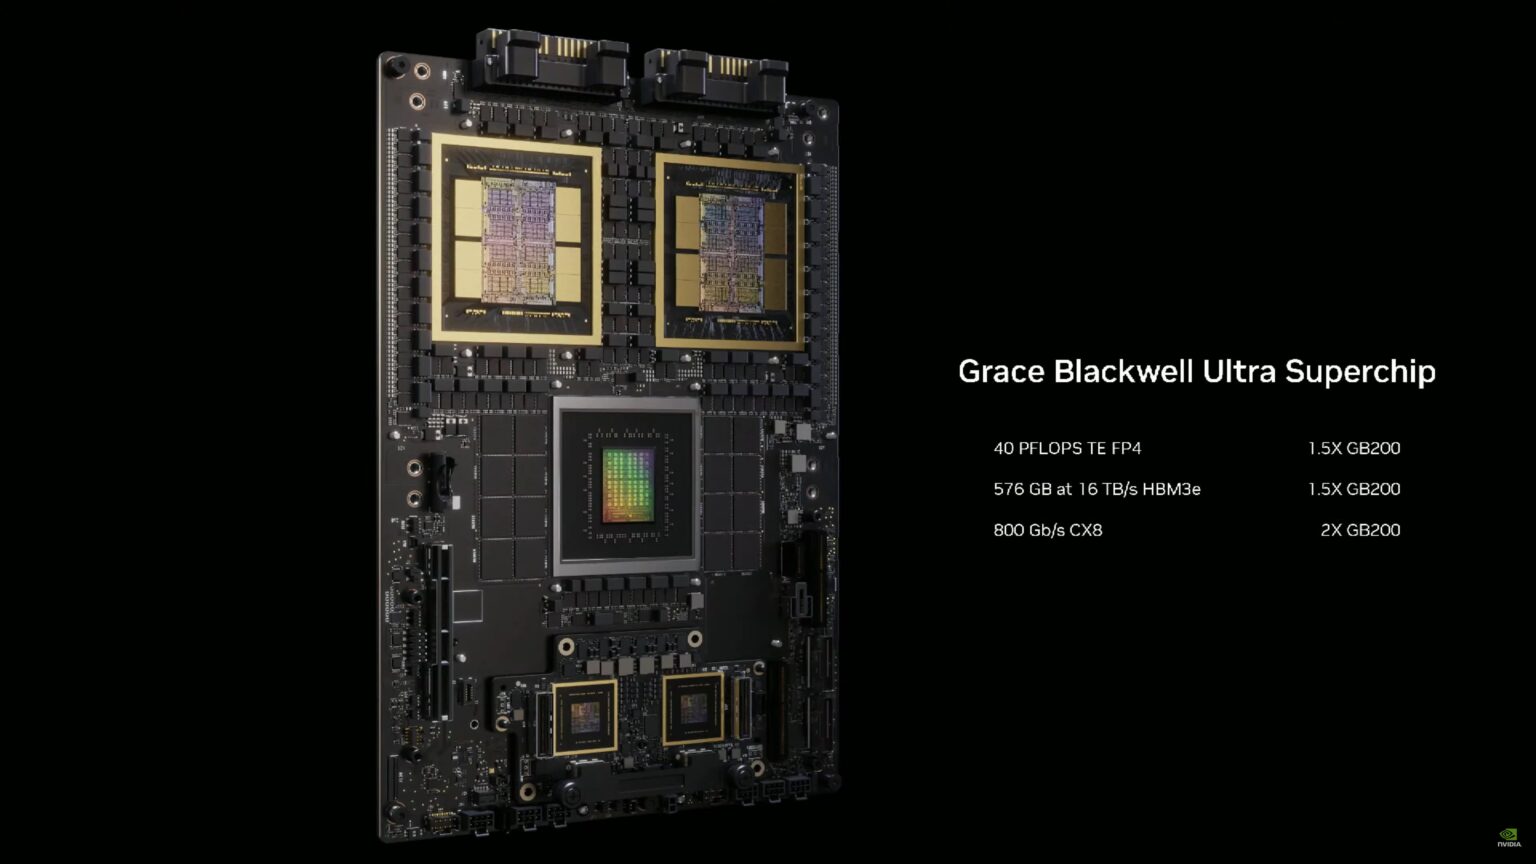
Nvidia’s Blackwell GPU rollout created an AI compute oversupply after customers preordered millions of chips amid expected shortages.
Alliance Resource Partners has 2026 coal sales fully contracted and is expanding oil and gas royalties through AllDale, supporting its 9.8%…
 Timur Mekhantev 4 clicks
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.