Toll roads in the sky
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales services rather than new installations.
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales services rather than new installations.
Ngl I'm the most bulled up I've been in a while here. Not bullish the entire market and $SPY, but bullish stuff like breadth, $RSP, low vol stuff. Breadth has crashed, sentiment is in the toilet, and October is historically pretty strong seasonality wise. https://t.co/Q3nWJ8IpAN
@27XVII $CSHR for bitcoin etfs
$CXW got a new President/CEO today. https://t.co/7WpulDuHkg
$IEHC continuing to expand into new markets and earn new customers. https://t.co/mAoKYoXKwz
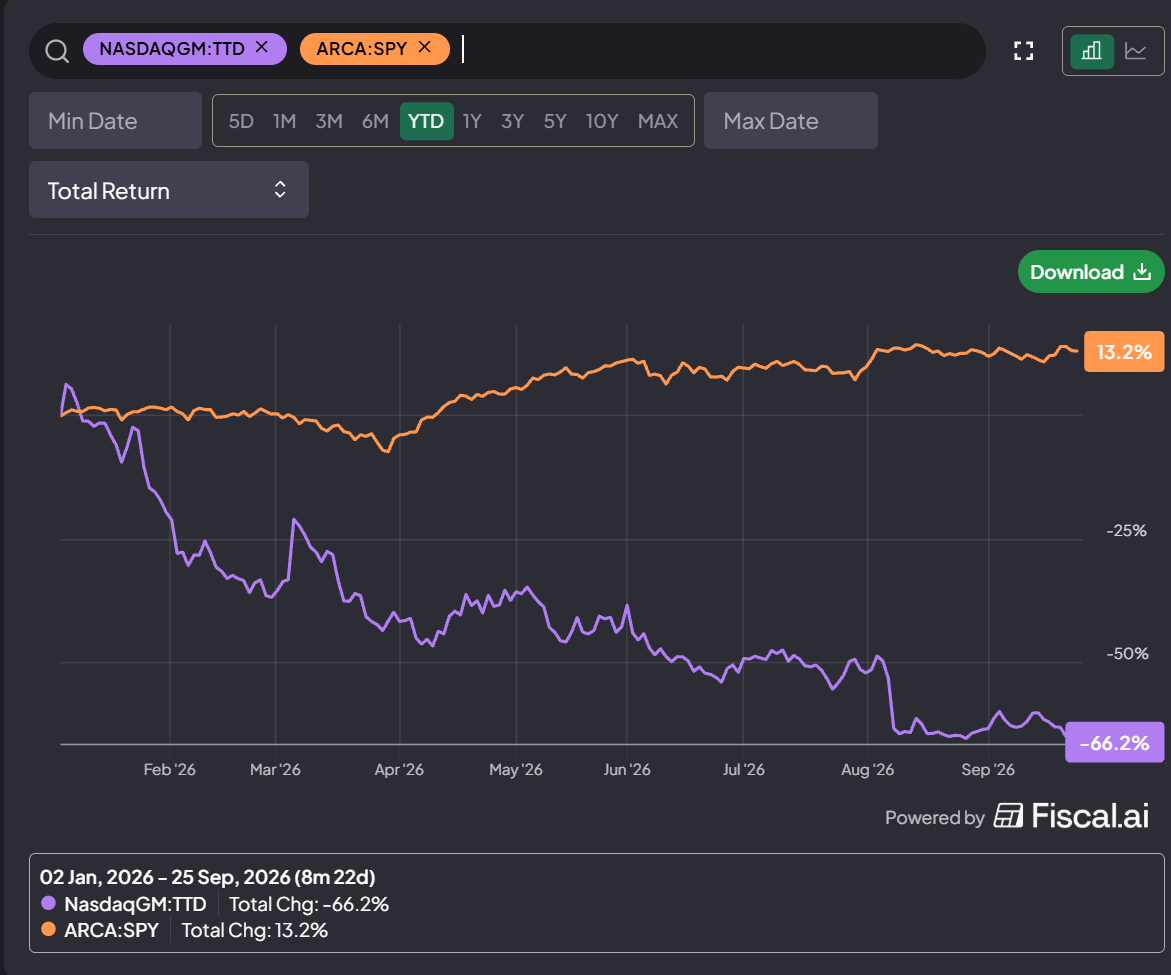
The Trade Desk’s CEO received a new 10-year option package targeting $105 per share as the company seeks shareholder approval to reprice…
Cullinan Therapeutics plans December 2026 autoimmune updates for CLN-978, while zipalertinib awaits an FDA decision in previously treated…
 Myriam Alvarez 2 clicks
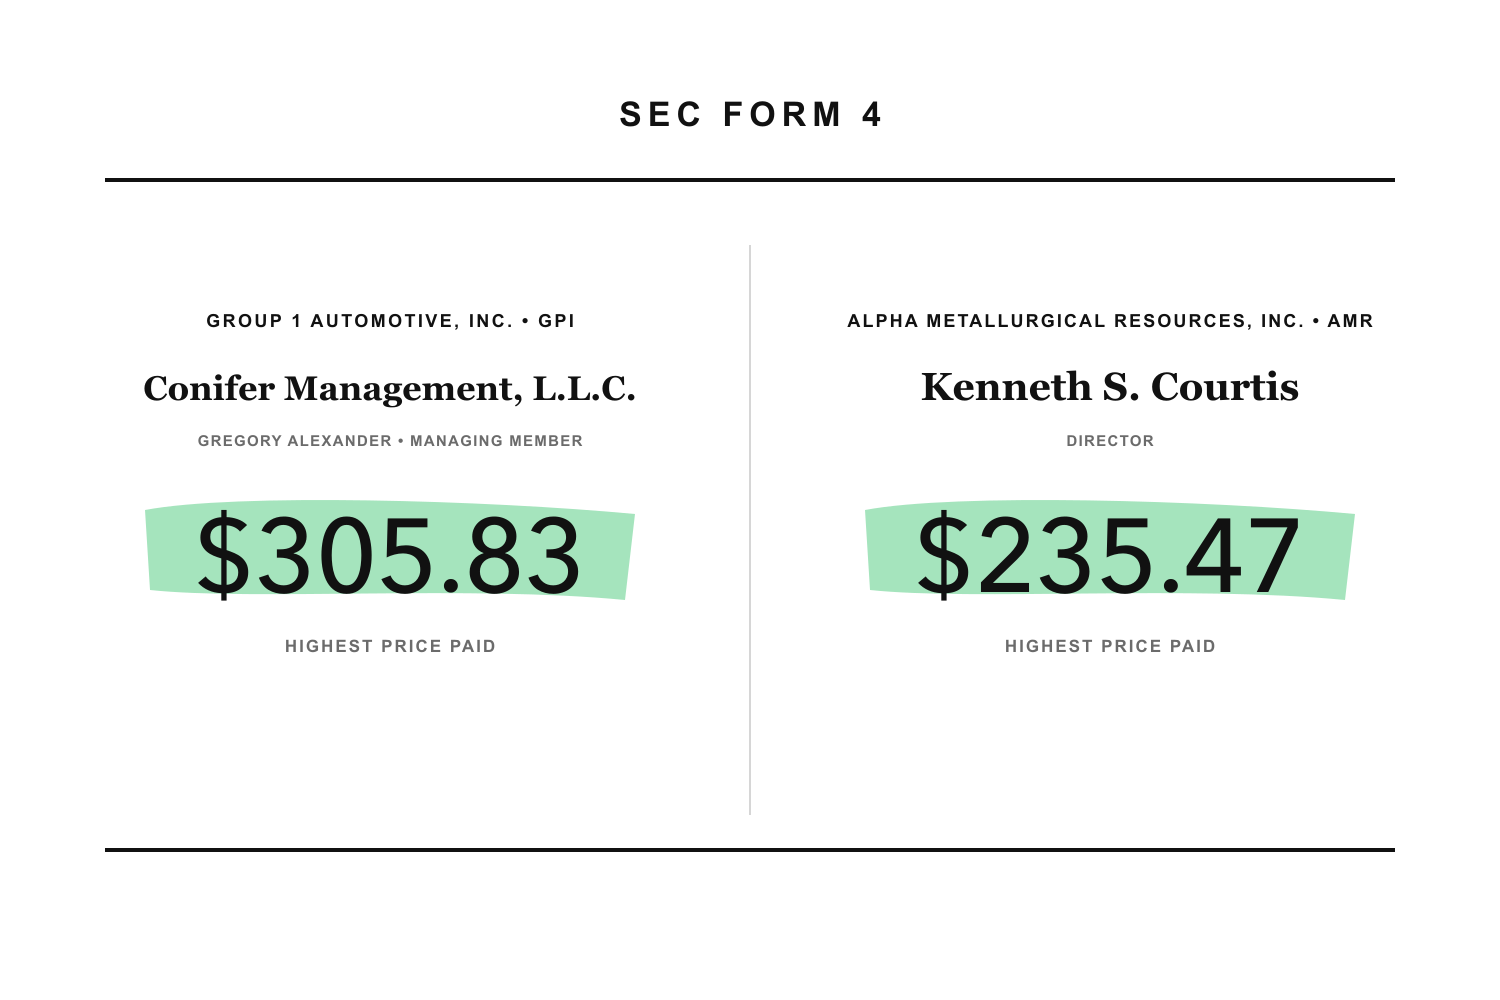
Alpha Metallurgical Resources director Ken Courtis bought $10.5 million above $190 after a blackout lifted, while Conifer’s 12.7% Group 1…
Monte Investments upgrades Karman Holdings to Buy with a $133 target after a 65% drawdown, citing 28.83x EV/aEBITDA and governance changes.
Applied Optoelectronics targets $1.1 billion in 2026 revenue as 800G and 1.6T data-center demand drives capacity expansion, despite…
 Infinity Curve 2 clicks

Zscaler posted 25% Q4 revenue growth to $898.2 million and a 24.3% operating margin, but guided FY27 growth down to 16.6%-17.5% as free…
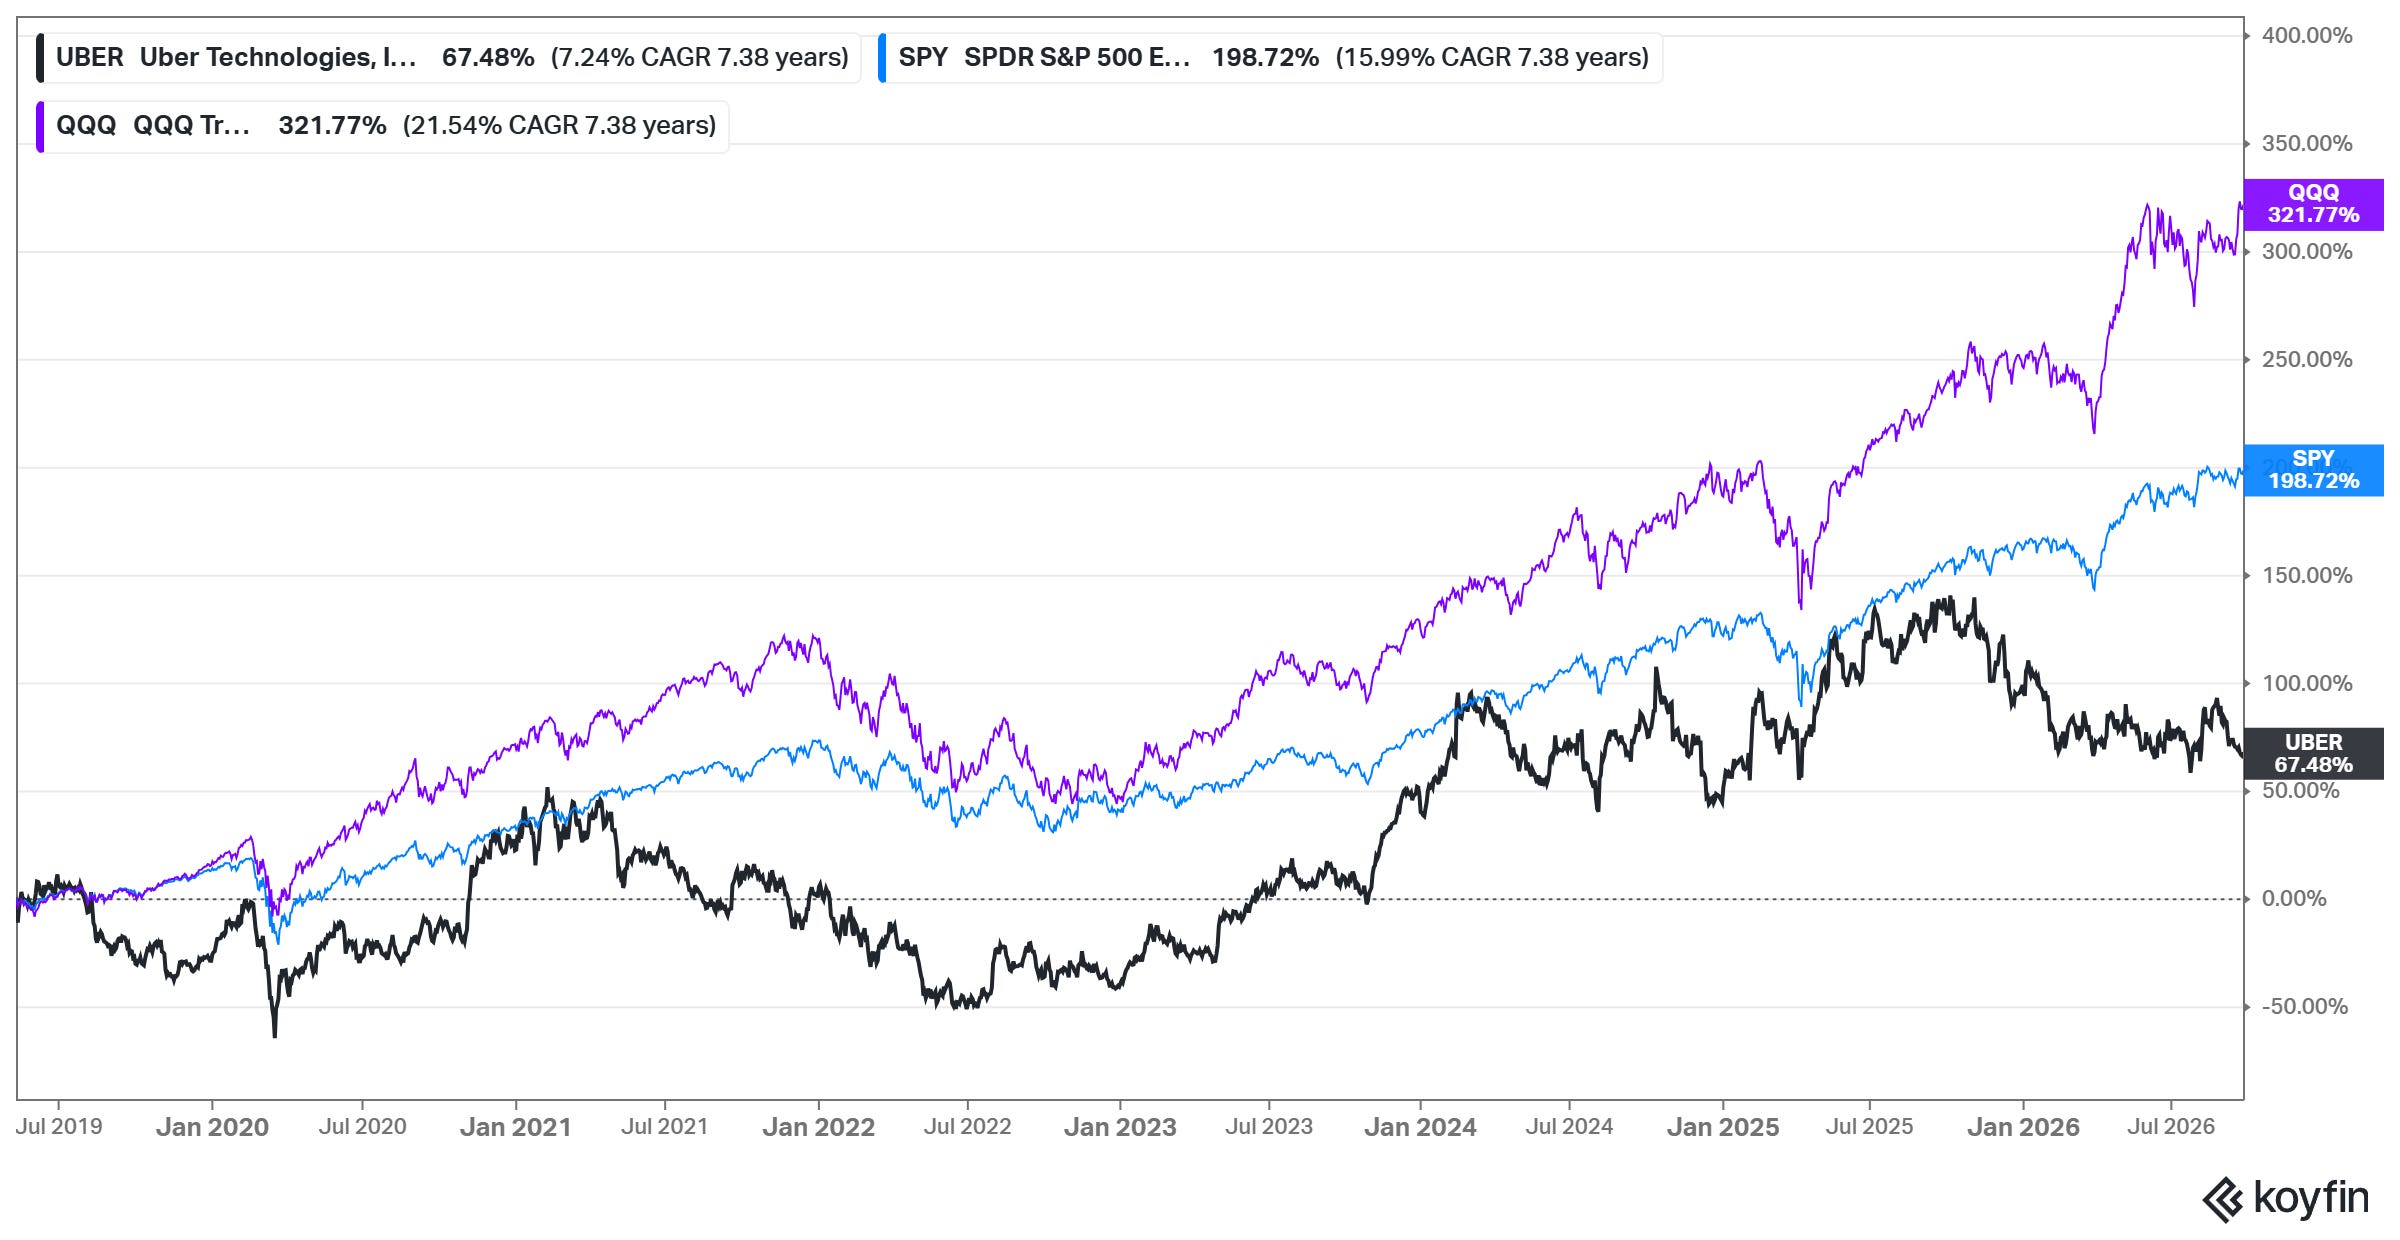
Uber's $193 billion in gross bookings and $10 billion in free cash flow contrast with modest stock gains as autonomous vehicles and…

Veeva Systems moved VEEV to Distribute at $277 after a 41% gain in less than two months, despite Q2 revenue growth of 18% and 45% EBITDA…
Gentherm’s Oct. 1 Reverse Morris Trust with Modine adds commercial and off-highway operations, leaving THRM at 7.4x pro forma EBITDA with…
QuantumScape faces a 2029 PowerCo plant delay, reduced partner commitments and no revenue, with a scenario-weighted $2.12 per-share…
 Bears of Wall Street
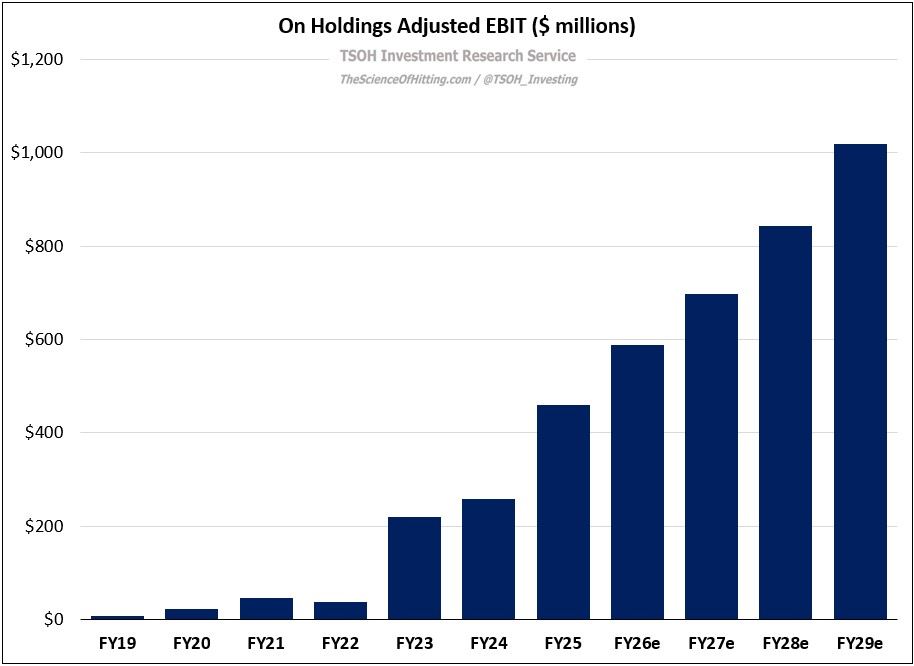
On Holdings targets premium growth through 2029, using LightSpray soccer cleats and higher pricing, with ASPs rising from $145 to $170…
Shake Shack combines 23% restaurant-level margins, 703 locations and positive free cash flow; the bullish thesis targets $4 billion…
 Security Analysis 1 click
Micron and Nike earnings headline a weekly briefing featuring Exor’s NAV discount, Meta’s Muse agent and Bellway’s UK housing valuation.
 SFIX · long
Stitch Fix’s 2017 IPO rested on overly ambitious long-term growth expectations and an unrealistic definition of its addressable market.
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s…
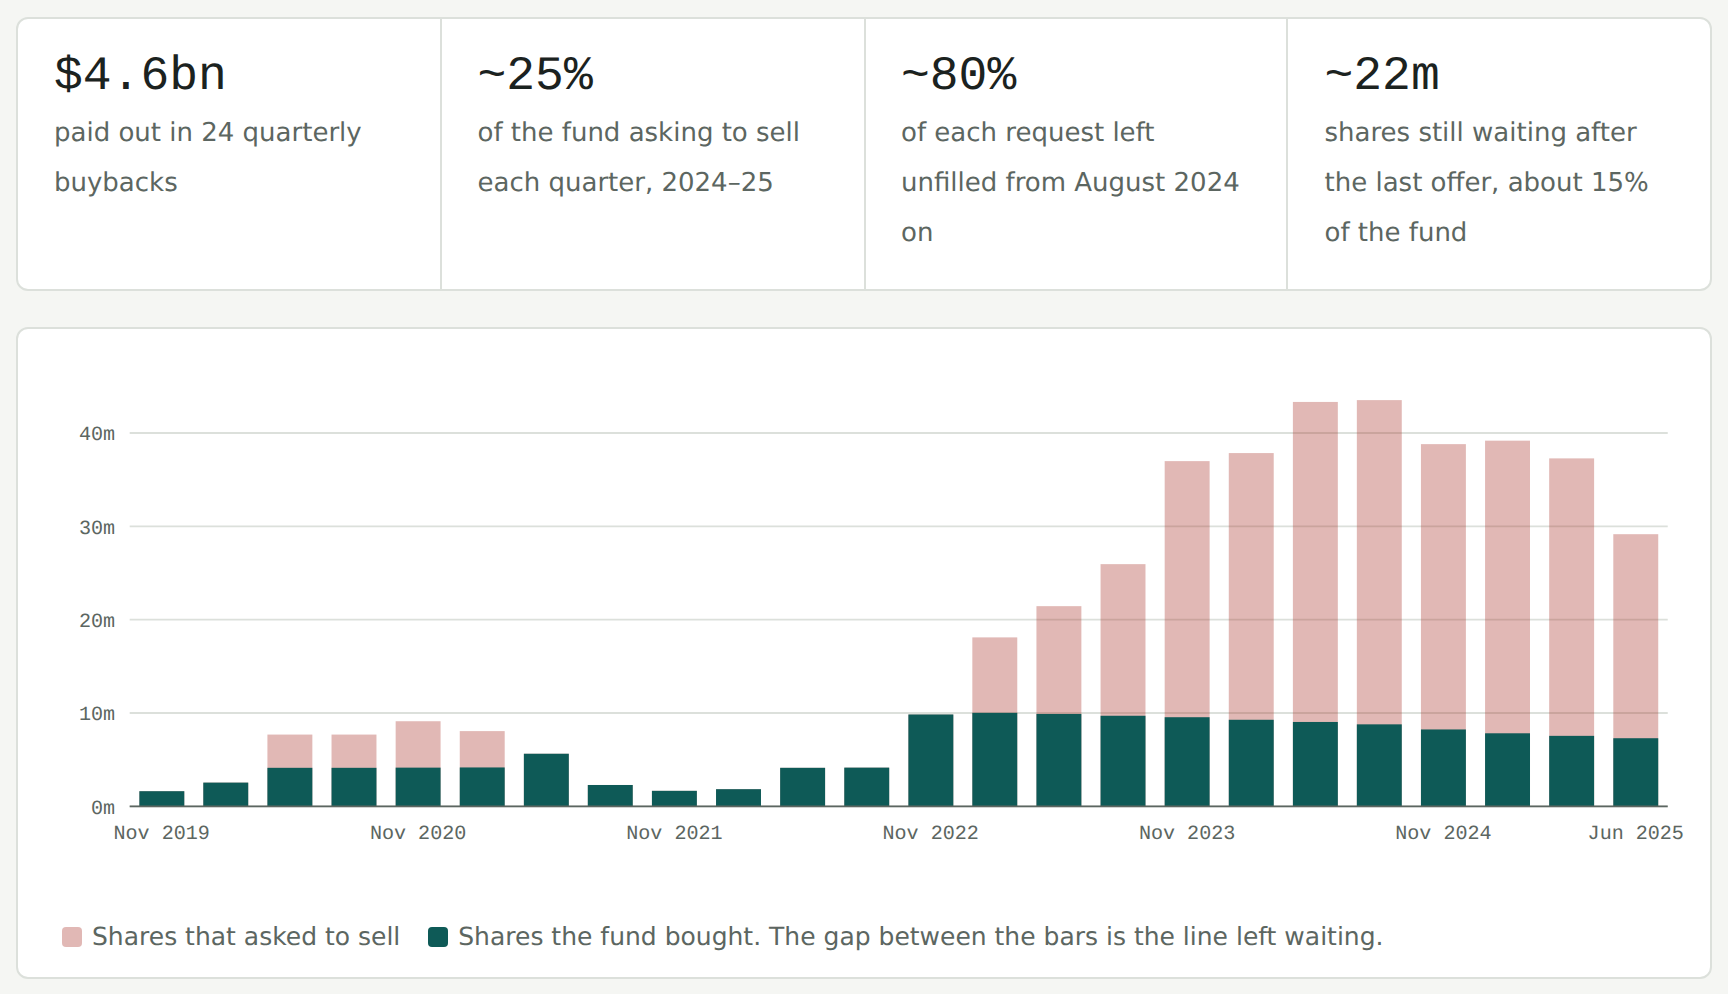
BPRE trades 45% below NAV as Saba and Bulldog press for buybacks or a manager change, challenging Bluerock’s incentive to preserve…
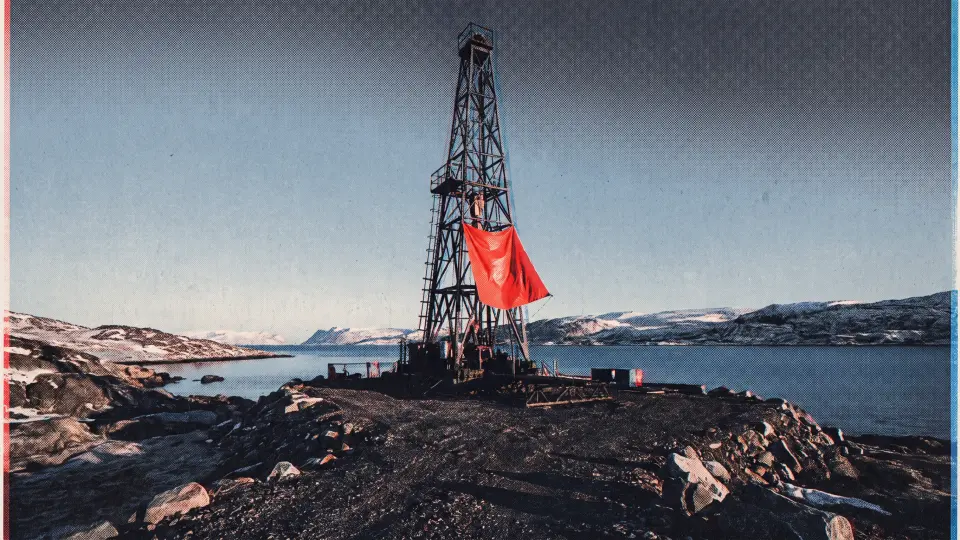
Greenland Energy Company holds 2.1 million acres in the Jameson Land Basin, but drilling permits, political risk and warrant dilution cloud…
 Ron Ferrie
Hindsight Capital tests crisis-era investment decisions using anonymized company financials, including TransDigm, Halma and Texas Pacific…
Neighborhood Intelligence, NXH, faces a cash shortfall after failed and restructured acquisitions, as losses and limited financing options…
 Vince Martin 1 click
Honeywell Aerospace, newly spun off as HONA, fell 41% from post-listing highs after Q2 2026 as supply-chain bottlenecks delayed revenue…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.