QNT: The 100× Question
Quantinuum's improving logical-qubit error correction, 1,504 successful-circuit benchmark score and paid deployments at RIKEN, BMW and Oracle frame quantum computing as a costly specialty…
Quantinuum's improving logical-qubit error correction, 1,504 successful-circuit benchmark score and paid deployments at RIKEN, BMW and Oracle frame quantum computing as a costly specialty…
I just published an Earnings Update about the Shelly Group $SLYG Q1 2026 results. You can find it in the portfolio section of the blog :) https://t.co/PBu7hw3ZdE
@thebankzhar @SteveChuck5 There are many candidates for $BANR to pursue next. $CSHX $CWBC $OVLY $PVBK $SFBC the list is endless. https://t.co/ssMeFndZzi
Let's not forget this is the CEO that actually wrote "our share price is candidly, and please pardon my language, way too f-cking low." Global Net Lease to Acquire Modiv Industrial in $535 Million Transaction $MDV $GNL
@JoesAutopen yes - it is on Carr. The same Carr who has surely seen the real world testing that $NN has done, and still submitted a draft NPRM. Is it your belief that the real world data was negative, and Carr chose to purposefully put his head on the chopping block?
Progyny's Q2 revenue rose 11% excluding Amazon, with margin expansion and nearly 100% EPS growth guidance for 2026 supporting…
 Robert J. Lake
Vizsla Silver's Panuco project in Sinaloa remains shut after nine workers were found dead, delaying construction of a fully funded 17.4 Moz…
Ethos relies on three carriers for 88% of revenue as TruStage payment failures triggered policy lapses and Family First Life publicly…
Talos Energy is raising standalone production guidance without added capex while using offshore cash flow to fund Shell acquisition and…
 Capital Connoisseur
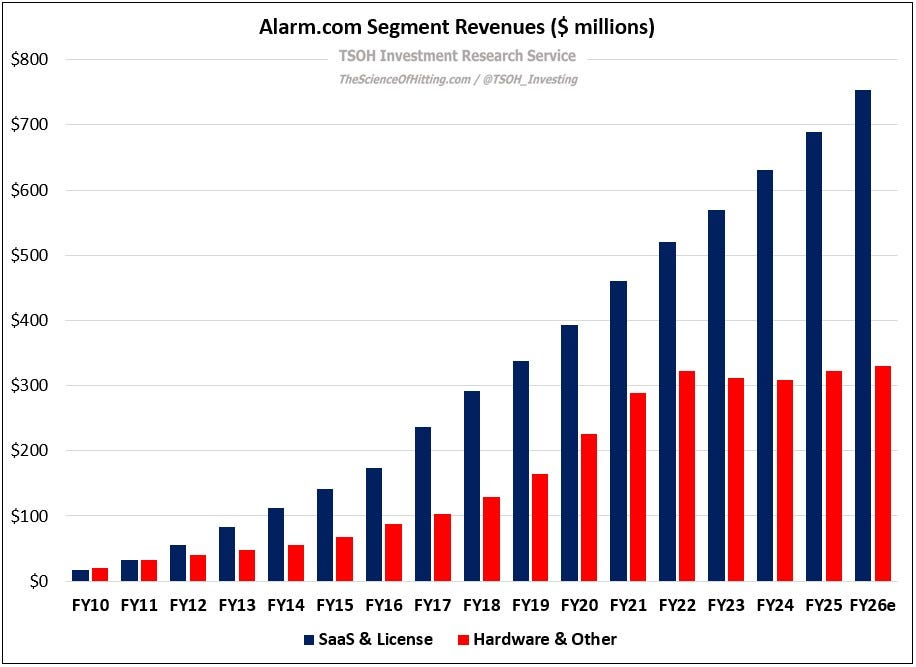
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
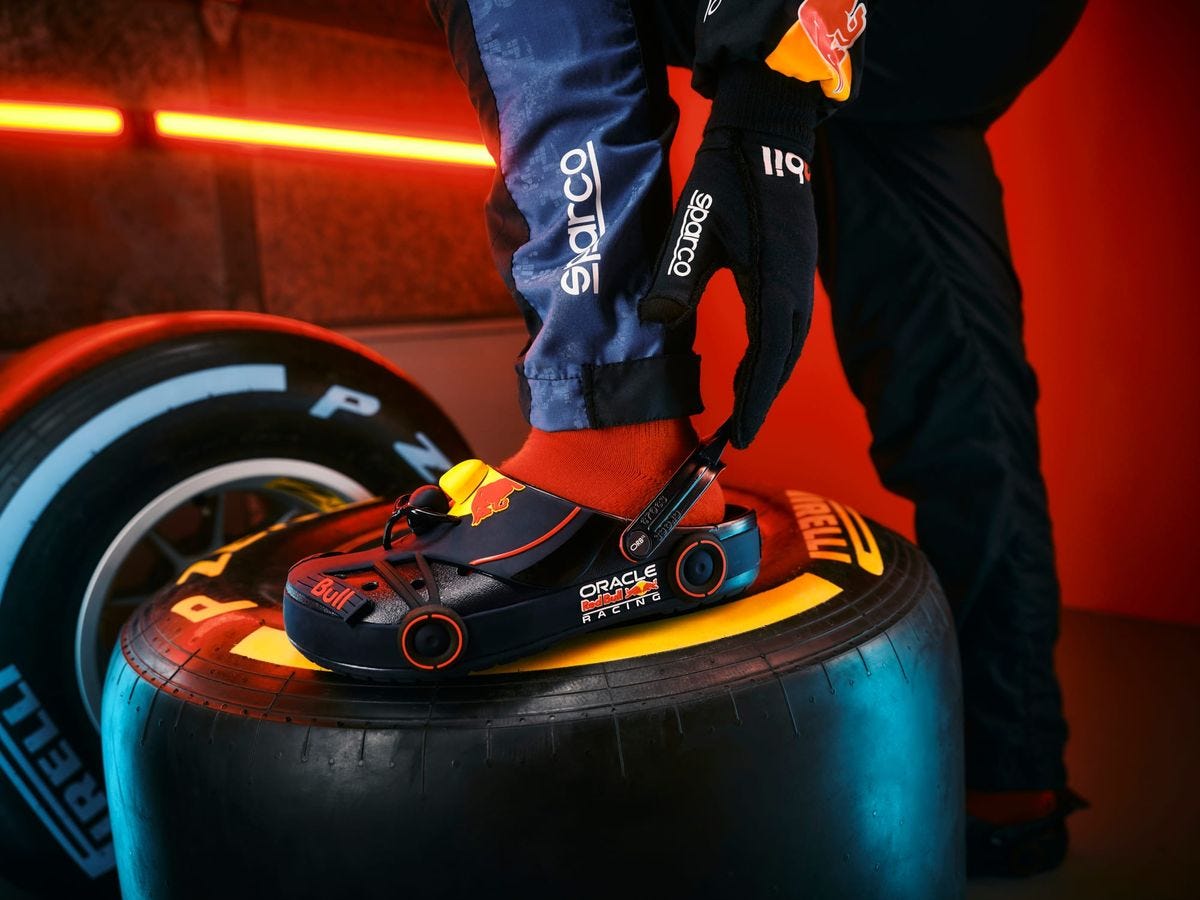
Crocs’ core brand surpassed $1 billion in quarterly revenue, while HEYDUDE weakness, tariffs and 2025 impairments weigh on shares trading…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…
Signet, Medipal and First REIT headline 27 situations spanning buybacks, activism, M&A and liquidation catalysts.
DHT Holdings' low-leverage VLCC fleet has paid 66 consecutive dividends, with charter income covering forecast costs and spot earnings…
 Arizona Equity Research
 EFXT · long
Enerflex, a $3 billion natural gas infrastructure and equipment company, blends contracted energy-services cash flows with equipment…
Kodiak Sciences expects Phase 3 DAYBREAK results for Zenkuda and KSI-501 in wet AMD, with durability and vision outcomes key beyond…
 Sam Mancini
Applied Aerospace & Defense reported Q2 revenue growth of 47% to $167 million and $1.13 billion in backlog, supported by missile production…
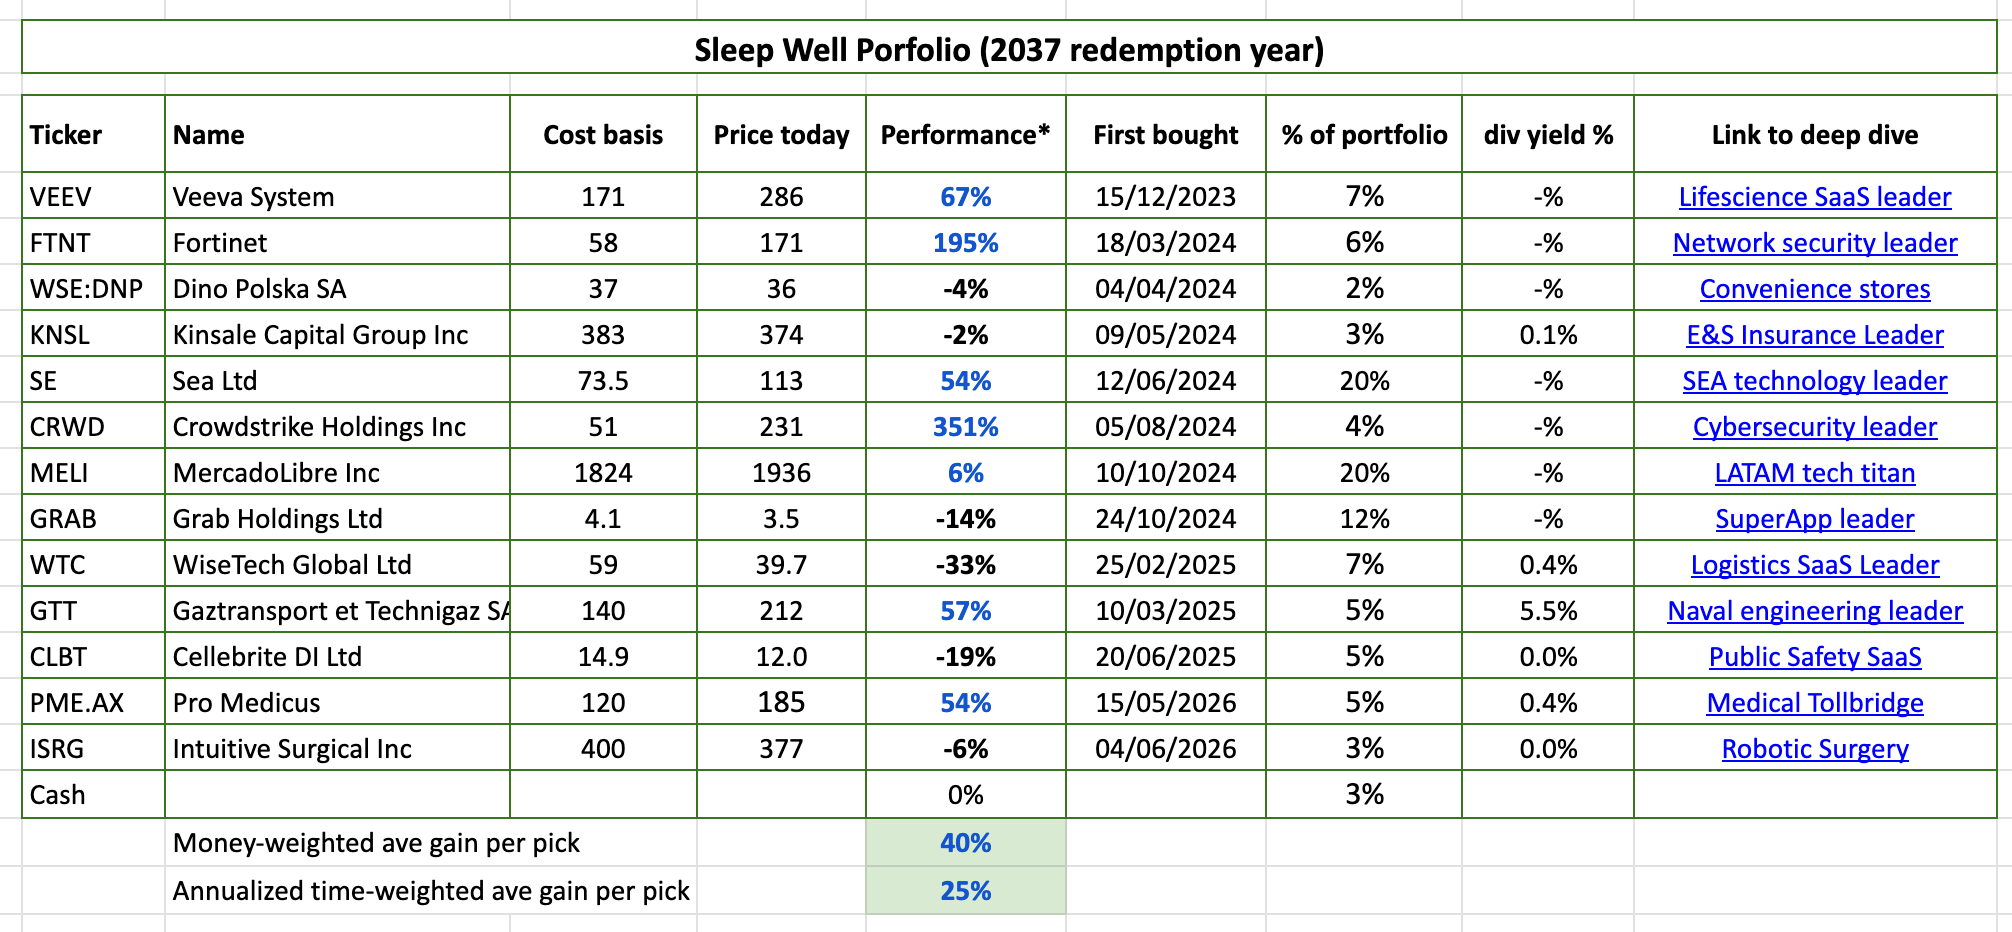
Sleep Well Portfolio’s August gains were led by Veeva, CrowdStrike and cybersecurity, while Cellebrite and WiseTech reported early AI…
Special-situations survey profiles 31 activist, buyback, M&A and strategic-review cases, including Abercrombie, PagSeguro and Vodafone.
Fastly's Q2 revenue rose 23%, while Security and Compute reached a $200 million run rate and drove record profitability.
 Miletus Research
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare…
AEVEX faces an eFY27 contract rollover after buying maritime drone maker BlackSea for $650 million, testing whether its 55-nation pipeline…

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
 BHVN 2026-08-27
Biohaven’s $795 million global opakalim licensing deal with SK Biopharmaceuticals boosts cash, lowers R&D spending and extends its funding…
 Edmund Ingham 1 click
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research Robert J. Lake Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.