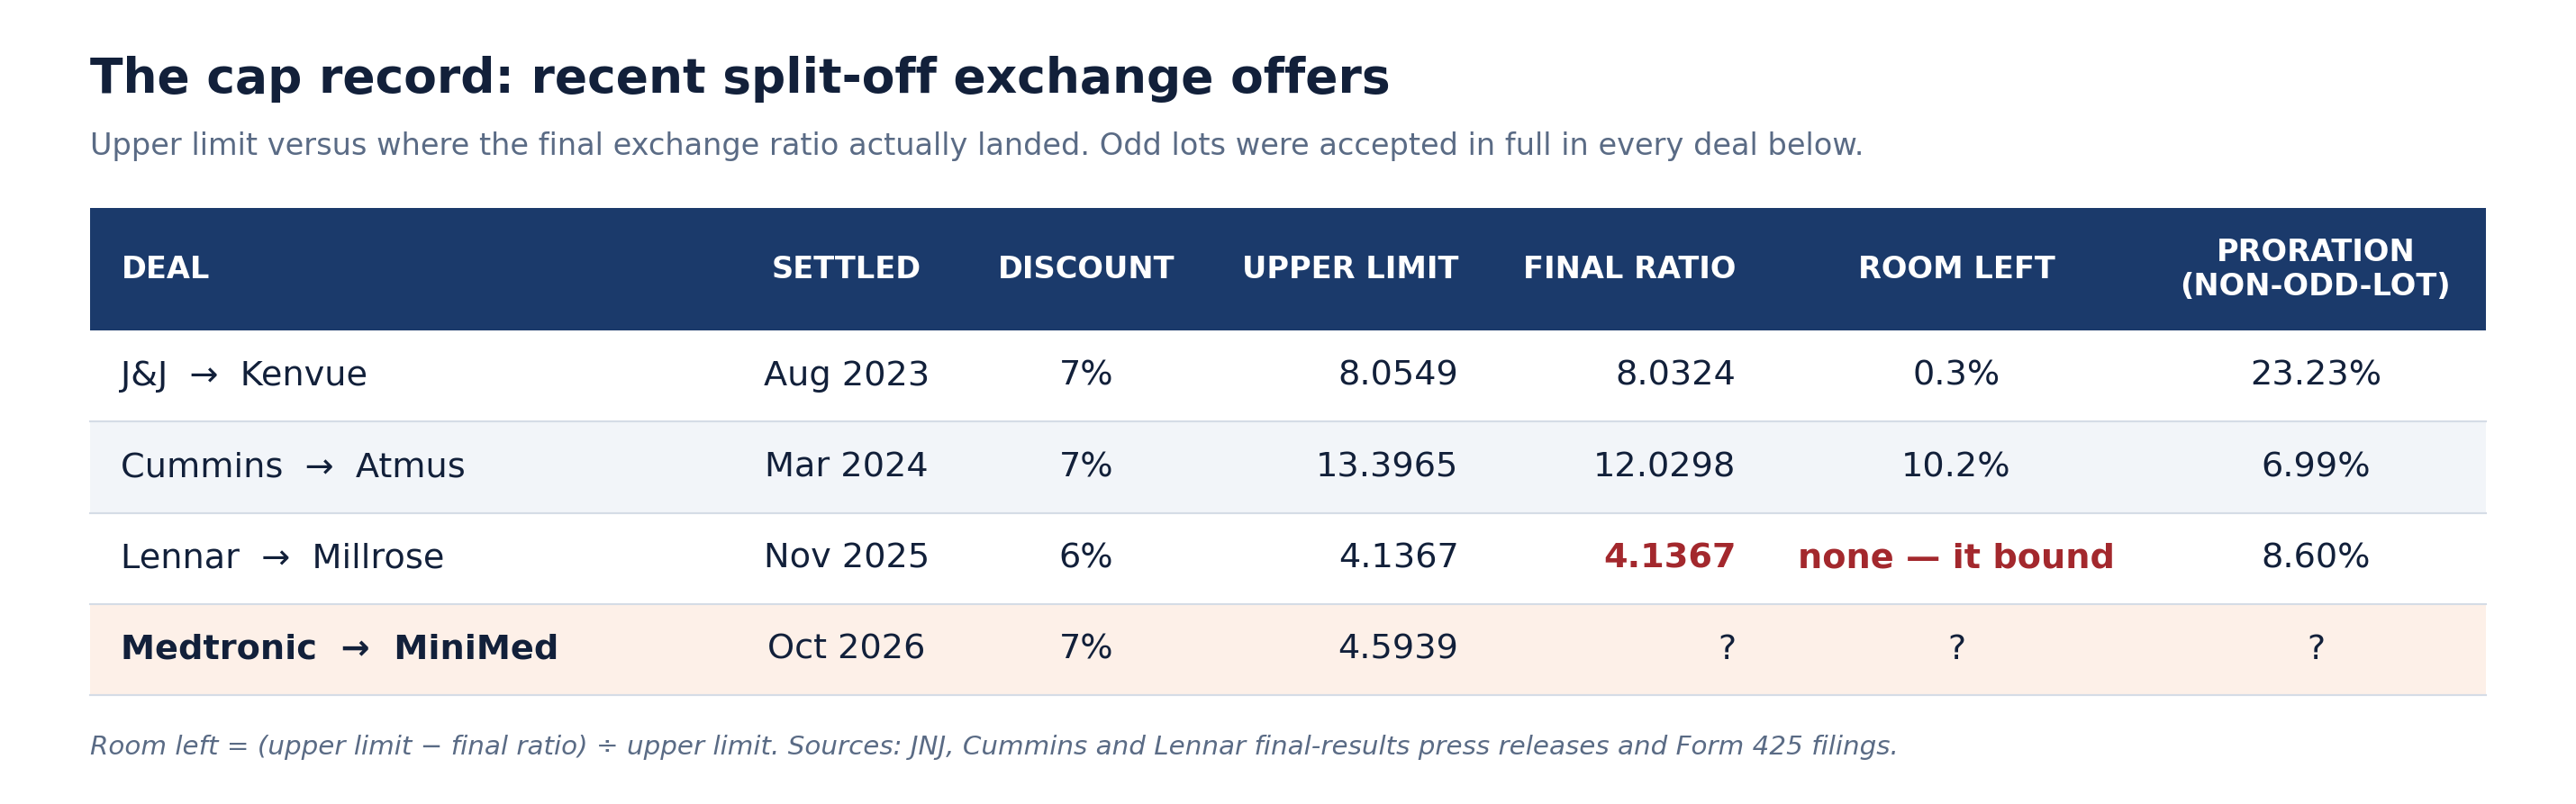
No Cap? Currently Capped by Three Hundredths of a Percent: Medtronic’s MiniMed Split-Off Odd Lot
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
Medtronic’s MiniMed split-off gives odd-lot MDT holders priority on a 7% discounted exchange, but a 4.5939-share cap has begun reducing the payoff.
StoneX highlights $ZM into the post labor day Anthropic S-1 Unlike certain SPVs/tokens, Zoom has actual ownership. $125 PT that becomes $135+ if Anthropic meets $2T https://t.co/o0xtRsx5KG
UBS: We believe $CENX offers the best leverage to a US Regional Premium that is sustainably higher. CENX currently trades at ~3.1x UBSe 2027 EBITDA estimates (below ~5x normalized 5yr average). We expect CENX to rerate towards our ~4x peak multiple driven by clarity… https://t.co/93RbEN5Ex7
Another $PBI debt upgrade... "Pitney Bowes Inc. Upgraded To 'BB-' From 'B+' On Strong Credit Metrics; Outlook Revised To Stable From Positive" https://t.co/dl97639K74
@DreamPositiveCp @grok what is the binary event for $NN?
@FishtownCap Could $UNFI and $CHEF merge or too much overlap already
Cestrian initiated Joby Aviation at Accumulate and upgraded Applied Materials and Broadcom to Accumulate for the week ended 11 September…
T1 Energy’s G2_Austin factory is expected to lift margins and add vertical integration from 2027, but requires substantial financing that…
 Investor Overview

Adobe’s fiscal 3Q26 revenue grew 13%, while ARR growth was about 9.3% excluding Semrush.
Enel Chile uses battery storage and grid management to turn renewable oversupply into flexibility, lifting H1 2026 EBITDA 3.9% and net…
 Ryan Canady 4 clicks
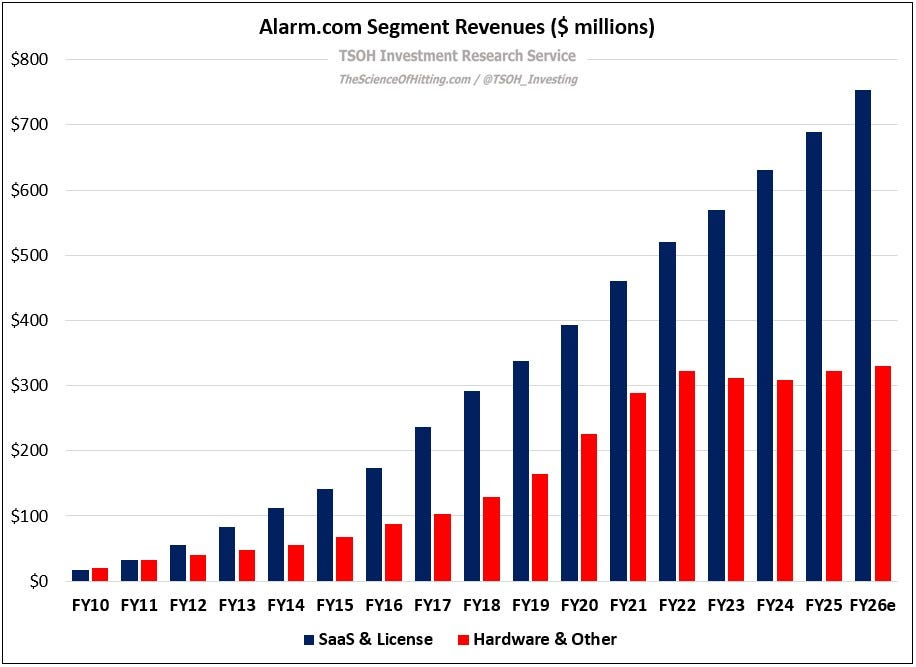
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
Barnes & Noble Education is shifting from campus bookstore retail toward recurring-revenue infrastructure for inclusive-access course…
 Given Mahlangu 2 clicks
Zentek initiation report.
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
 SLVM · long
Sylvamo, a $1.6 billion uncoated freesheet paper producer, has fallen about 60% from its November 2024 high above $95 to roughly $40.
Nintendo expects software, digital sales and character licensing to drive growth, with FY2027 revenue forecast at ¥2.05 trillion and…
 LL Insights
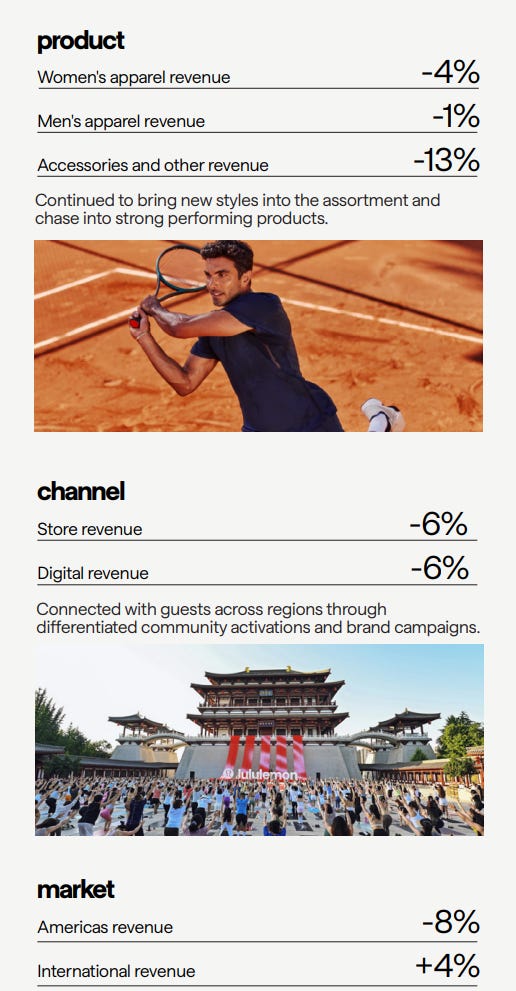
Lululemon’s growth stalled as affordable-luxury apparel brands face fading post-Covid demand, cheap social-media influence and China…
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…

Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
NET Power’s $1.80 shares are paired with January $2 covered calls for 40 cents as the company pivots from carbon capture to Permian…

Tsakos Energy Navigation benefits from higher oil prices and stronger tanker sentiment, but faces long-term demand destruction and…
 Long Player

Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…

Sofwave Medical grew Q2 revenue 43% as recurring usage fees reached 46% of sales for its non-invasive ultrasound skin-tightening devices.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor Investor Overview
 IWA Research
 Jaden Mealy LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.