[WAY – Waystar] Healthcare is a very complicated invoice
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare administration consumes 15% to 25% of spending.
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare administration consumes 15% to 25% of spending.
$NX Just acquired peer Tyman. >3x leverage, never done a deal before, commodity business, customers all cutting numbers w deteriorating resi remodel activity ($AMWD yesterday, $MBC, $OC, $JELD). Stock is trading at close to 14x EPS. Seen this movie before. Earnings next week.
$PLUS Earnings on 8/5, expectations & stock disconnected from reality. Suppliers ($CSCO – 50% of product sales), competitors & customers all reporting sharp sales declines. Non-event PR today re a service they’ve been offering for 3 yrs is pumping stock; suggests mgmt is grasping
@ragingbullcap @PropertyBigE $SEG could get very interesting. It'll be well capitalized and the approval of 250 Water St. definately doesn't hurt. I still need to see the S-1 filing and terms for the offering before making any major decisions but they've piqued my interest.
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
8/ There is a lot more to talk about (24% sequential increase in new home sales, ward village condo sales etc.) but I am hungry. So to wrap up, if you're selling $HHH on this quarterly report you do not understand what you own and I will be buying your shares at tomorrow's open.
 AMPX 2026-08-28
Amprius Technologies, after a 50% decline, reported 125.7% revenue growth and raised 2026 guidance to at least $140 million as…
 Kurt Christensen 1 click

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
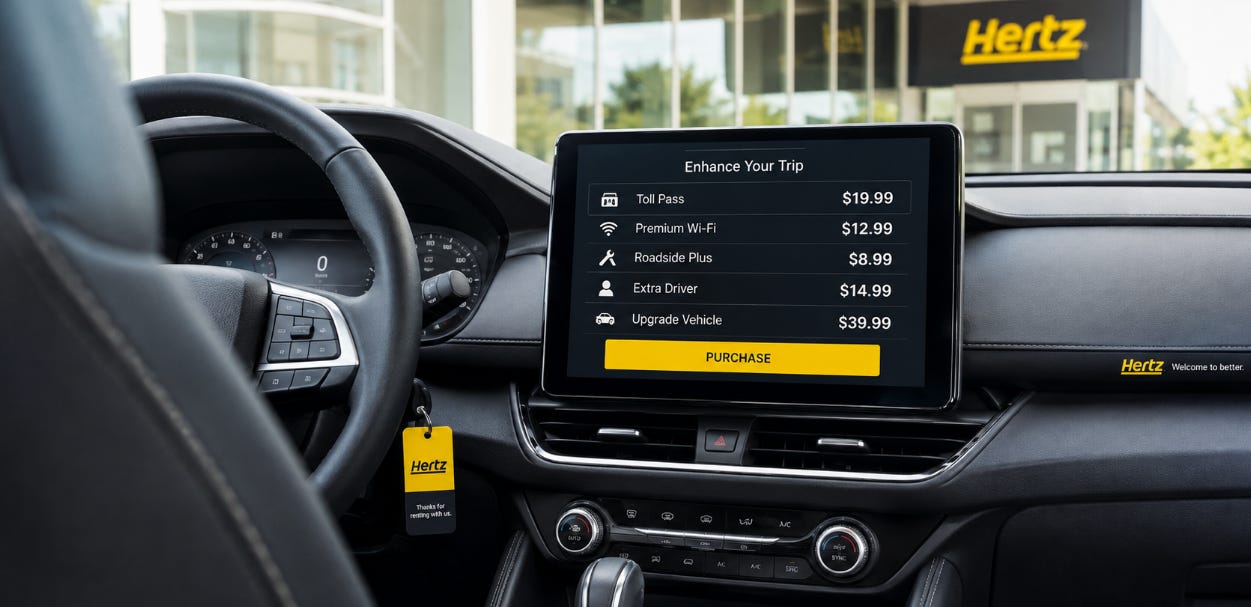
Verra Mobility renewed Hertz tolling management for five years. AutoKinex lets rental customers buy tolling, fuel and protection products…
BHVN 2026-08-27 Biohaven’s $795 million global opakalim licensing deal with SK Biopharmaceuticals boosts cash, lowers R&D spending and extends its funding…
 Edmund Ingham 1 click
Domo’s $400 million sale to Progress would leave a cash-rich public shell with $900 million of NOLs; January 2028 $5 calls cost 22 cents.
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and…
Star Equity’s $5 per-share Harte-Hanks acquisition offers $2.50 cash plus 0.25 STRRP per share after proration, against a $2 break price.
RCEL 2026-08-24 AVITA Medical’s more predictable reimbursement, RECELL GO rollout and PermeaDerm economics support adoption, with cash flow breakeven…
 Myriam Alvarez 4 clicks

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
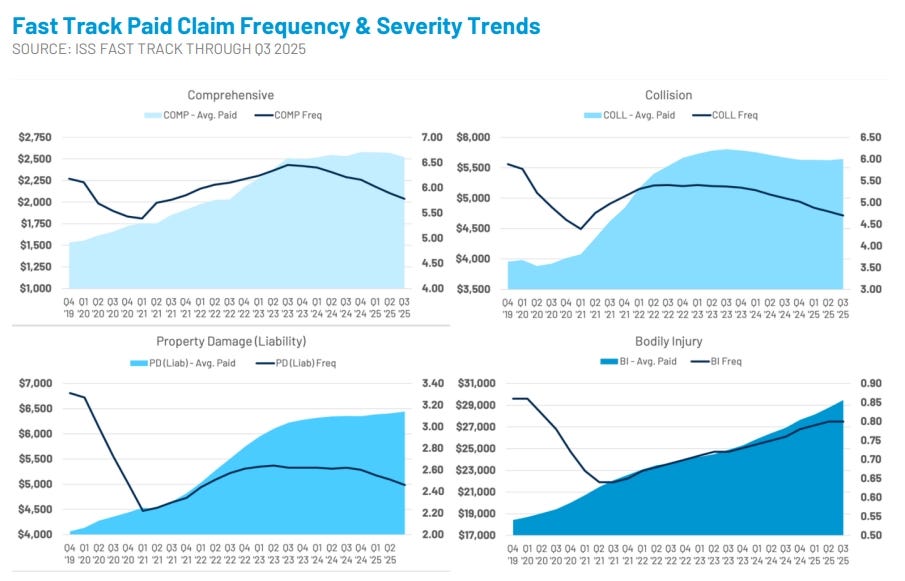
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
 COCO · short
Vita Coco, COCO, is pitched short after a 45% monthly rally, arguing investors are overextrapolating coconut water category growth.
FTRE 2026-08-30 Fortrea’s adjusted EBITDA rose 24% in H1 as cost cuts outpaced a 3.4% revenue decline, while new business awards increased 19%.
 Manimala Misra 2 clicks
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
SA 2026-08-20 Seabridge Gold's KSM gold-copper project could re-rate on a joint venture, 2027 feasibility study and infrastructure progress, with gold…
 Redfern Research
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028…
PGY 2026-08-19 Pagaya Technologies reported Q2 2026 network volume of $3.54 billion, 19% revenue growth and 99% adjusted net-income growth, while trading…
 Akim Guerreiro
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and…
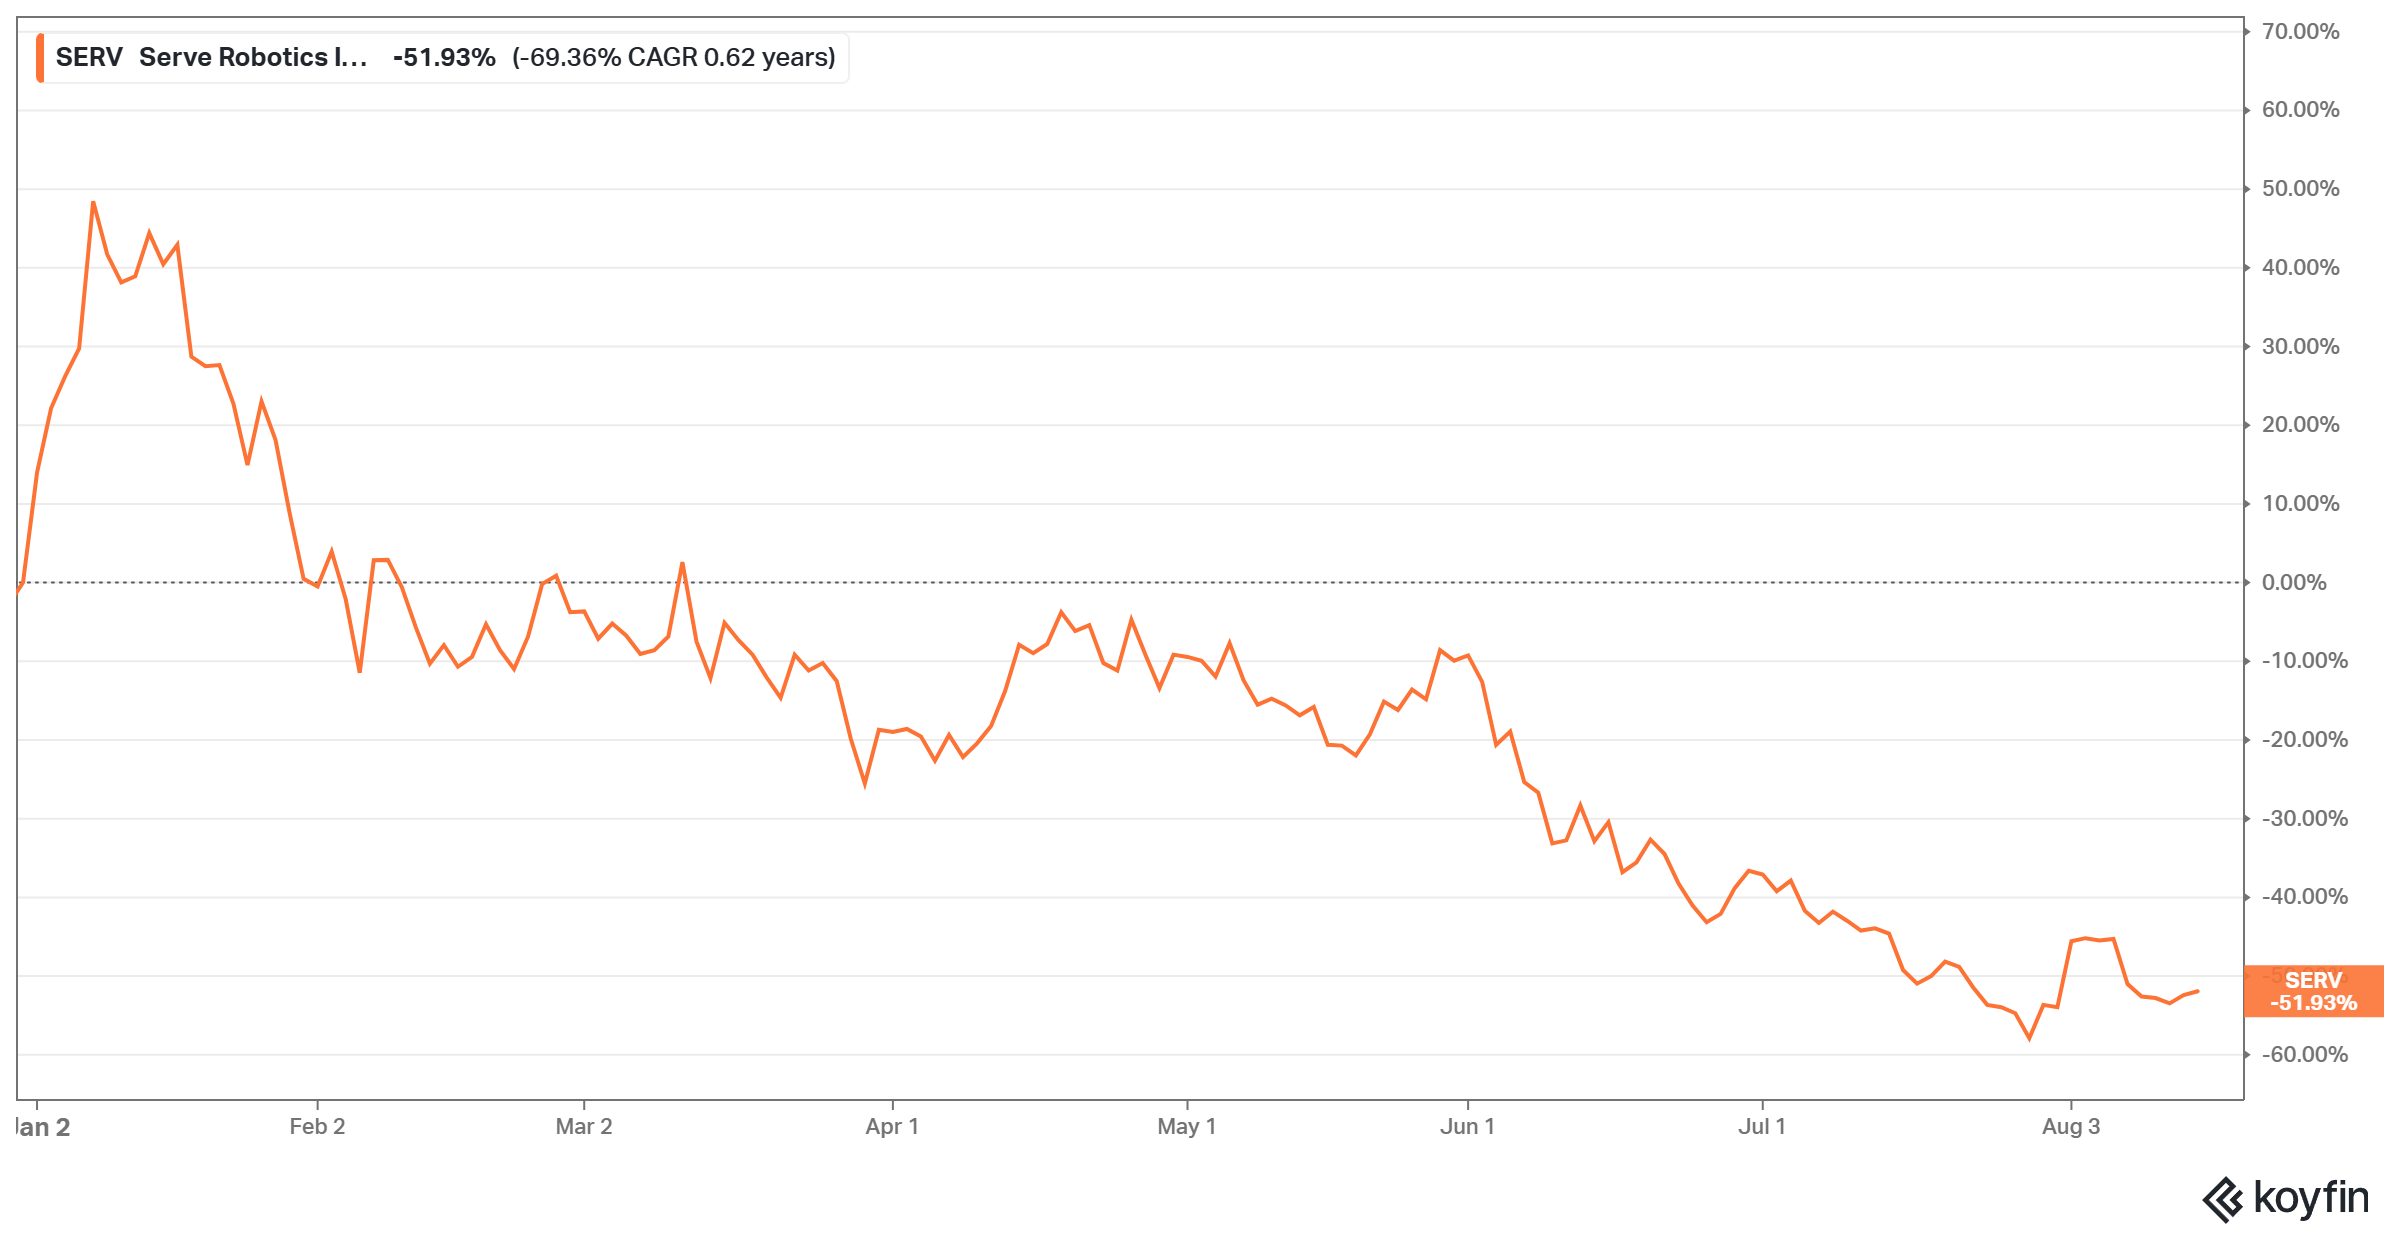
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.