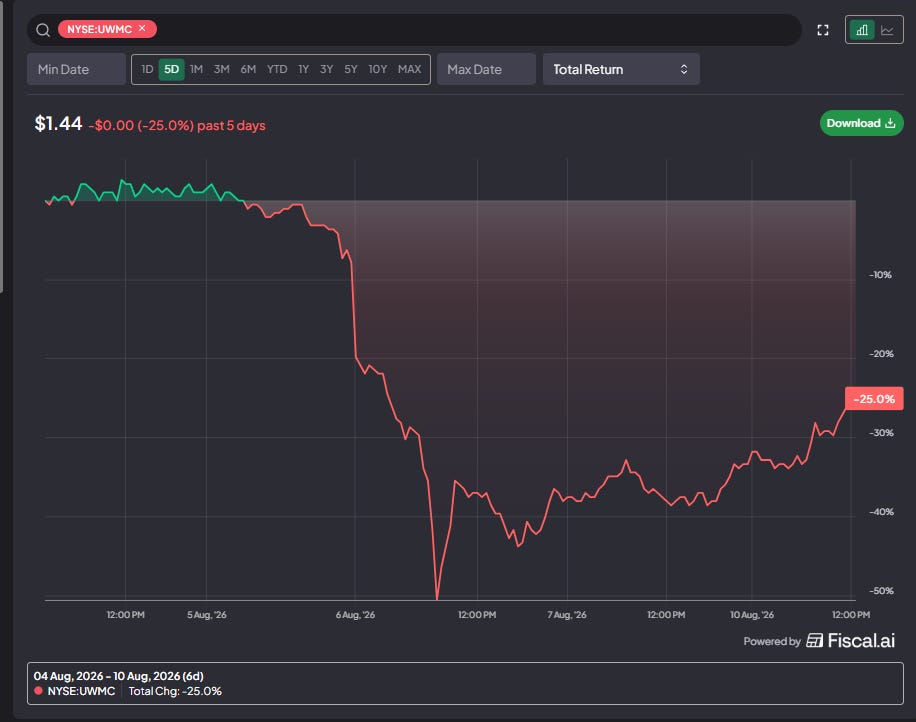
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.
S Yet Another Value Blog Aug 11 11 clicks
CBIZ activist Ryan Bunn urges ending buybacks, issuing equity and resuming bolt-on acquisitions to delever after the $2.3 billion Marcum…
YT Yet Another Value Podcast Jul 14 2 clicks
VEON’s 84% Kyivstar stake and JazzCash underpin a sum-of-the-parts case for 4x upside, despite its sanctioned shareholder, capital…
S Yet Another Value Blog Jul 1 1 click
Wingstop generates most of its $697 million revenue from franchise royalties across a 3,153-restaurant, 98%-franchised system while…
S Bearhold Research Jun 28 2 clicks
A software powerhouse posts a record quarter while trading at a 52-week low, raising a valuation disconnect between its business model and…
S The Value Road Jun 12 5 clicks
Vidrala has grown from a Spanish glass-container maker into a multi-country packaging platform with expanding Latin American exposure.
S smallvalue. May 19 6 clicks
AXT’s 85.5%-owned Tongmei depends on offshore pricing, export approvals and transfer-pricing economics despite AI-optics demand.
S Maius Partners Apr 2 7 clicks
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…
S Speedwell Memos Feb 19 1 click
A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…
S Treasure Hunting Feb 5 3 clicks
Haw Par combines Tiger Balm’s stable cash flows with property, leisure and healthcare operations plus stakes in UOB and UOL.
S smallvalue. Dec 17 4 clicks
TDC · short Teradata is a short as its on-premises analytics business declines while enterprises shift workloads to cloud-native platforms.
BL Value Investors Club May 16
National Beverage’s rare share repurchase is framed as a buy signal, with 50% upside projected.
S Nat Stewart - Stock Picking Newsletter Nov 25 3 clicks
Argentine banks, tariff-exposed stocks and Customer’s Bancorp anchor an earnings-season watchlist after Milei’s election victory,…
S Cluseau Research Oct 27 3 clicks
Upstart says longer repayment terms lifted Q1 debt-settlement acceptances 50%, but does not disclose delinquency changes or the number of…
S John Hempton's Newsletter May 6 2 clicks
Sarepta’s Exondys 51 approval despite a 12-patient trial frames FDA regulatory risk and a call to remove Commissioner Robert Califf.
S John Hempton's Newsletter Oct 31 1 click