Saturday, October 10, 2026

Back to today

From X

@StableBread

Fajasy on X

Elmet $ELMT expects Masan High-Tech Materials, its Vietnamese tungsten supplier, to stay its key refiner even after a U.S.-funded plant in Nevada comes online, and it bought 4.99% of the company for $124.75M on October 1. Masan High-Tech Materials (UPCoM: MSR) mines tungsten at Nui Phao in Vietnam, refines the concentrate into APT (ammonium paratungstate, the traded form of tungsten) and oxides, and calls itself the largest producer of processed tungsten outside China. Elmet, which turns tungsten into parts for U.S. missiles and jets, has bought from MSR for 12+ years, and the deal values MSR at $2.5B. The 55.1M shares came from a Masan Group (HOSE: MSN) subsidiary, so the $124.75M goes to MSR's parent, not into MSR. Along with the stake come (1) an MSR board seat, (2) an 18-month lockup on Elmet's MSR shares, and (3) 8+ years of supply that MSR puts at ~1,250 tonnes of WO₃ (tungsten trioxide, the standard measure of contained tungsten) a year, ~$1.5B of revenue to MSR at today's prices. That's ~$187.5M a year of spend with MSR ($1.5B / 8), equal to 82% of Elmet's $228.5M of TTM revenue. On September 14, Elmet's deck labeled ~$100M of the U.S. Department of War's (DoW) $450M "Strategic Investments in Elmet Refining & Trading," its new tungsten buying and trading division, to build a "diversified feedstock portfolio." The October 1 deck relabels the same ~$100M "Strategic Investment in Masan," and the stake cost $124.75M. At $2.5B, Elmet paid 10.7x the ~$233M of net profit MSR expects for 2026 ($2.5B / $233M). For context, APT was $3,040/MTU (metric ton unit, 10 kg of WO₃) on May 29, up from $330 in January 2025 per Elmet's deck, and Elmet's own 2031 targets assume $1,500/MTU. Elmet's 8-K also says it won't participate in MSR's 2026 interim dividends. On October 1, the day the shares traded, MSR's board proposed a second 2026 interim dividend of VND 5,000/share (Vietnamese dong). VND 5,000 is 8.5% of the VND 58,760/share Elmet paid, or ~$10.6M on its 55.1M shares. In September I wrote that Springer, the Nevada APT plant, gives Elmet the one step it didn't own: Turning tungsten concentrate into the oxide its powder line starts from. Elmet's deck calls MSR a "long-time supplier and processor of blue tungsten oxide (BTO)," so MSR already handles the conversion for Elmet. So the step Elmet didn't own in July stays with MSR, and Elmet paid 10.7x MSR's expected 2026 profit for its 4.99% while its own 2031 plan assumes APT at under half the May price.
@StableBread

Fajasy on X

My investing thesis in a nutshell (w/examples): 1) Buy with a strong margin of safety or stock price near/below cash and/or book value. 2) Buy in industries and/or markets where the money is flowing. Makes it a lot easier. 3) Buy the best early and/or the most overlooked in that particular industry. 4) Pay up for unfair advantages, excellent mgmt teams, and companies with huge latent pricing power. 5) Sell when the thesis breaks. Or a much better risk/reward setup hits your desk. Otherwise continue to add/hold. Don't track stock prices. Track the main business KPIs like any competent mgmt team would. Example #1: Bought $NBIS 4x mid $20's (best overall). Then bought $BRUN common and warrants pre-merger (most overlooked). Example #2: Bought $FTEK $1.39. Cash floor new excellent operator CEO. Strong upside potential w/data centers. Example #3: Bought $BABA $70's. Strong margin of safety, market leader, unfair advantages. Sold $170 for better risk/reward. Example #4: Bought $ELMT @$19 and @$14. Unfair advantage. Strategic. Cheap. Critical in strong growth industries. Example #5: Bought $TOST @$24. Beaten down due to macro headwinds and new/early $DASH competition. But almost everything in business stronger and expanding to new verticals. Lastly, if you're unsure or don't fully understand the business. Just say no. In fact, say no to most stocks. Most probably your best idea is already in your portfolio. Don't lockup your money in a 3/5 setup, you're trying to make outsized returns! And sub to my newsletter (link in bio) if you want my deep dives. 😉
@StableBread

Fajasy on X

The hoist at Levack, the flagship mine of Magna Mining $MGMNF (TSX: $NICU), was designed to move 6,000 tons a day, ~5.5x the record Q2 pace at McCreedy West, its producing mine. Most of Levack’s infrastructure is already built. Magna expects to finish refurbishing the hoist and the loading pocket where ore enters the shaft before the end of 2026. Magna is engineering a new ramp from surface (a sloped tunnel trucks can drive down) for the shallower zones, with the shaft serving the deeper Morrison ore. By mid-2026, crews had tunneled into the Intermediate Orebody (IOB), and Magna says mining the drilled part of the IOB “could begin immediately upon a positive restart decision.” CEO Jason Jessup said in July there’s a “very strong possibility that before the end of the year, we will skip first ore,” meaning hoist the first ore up the shaft, with shipments building through H1 2027. In the same interview, he said Levack and Crean Hill, Magna’s permitted nickel mine, are “both working towards commercial production in 2028.” On scale, he expects Levack to produce “possibly two to even three times” McCreedy West’s payable metal, which would make McCreedy West “our smallest mine within the next couple of years.” Magna’s first resource estimate for Levack (its estimate of the metal in the ground) found: → Contact deposits: 5.9Mt indicated at 3.2% copper equivalent (CuEq, which converts every metal into copper at set prices), mostly less than 750 meters deep. → Morrison footwall: 178,000 tonnes indicated at 15.5% CuEq, with the deposit continuing below the deepest drilling. → Total: 6.1Mt indicated at 3.54% CuEq and 5.2Mt inferred at 3.59% CuEq. Indicated tonnes come from drill holes spaced closely enough to support a mine plan. Inferred tonnes rest on fewer, more widely spaced holes, so their size and grade could still change with more drilling. Jessup says “the bulk of the PEA tons will come from the contact nickel zones,” so nickel matters far more to Levack’s PEA (preliminary economic assessment) than to McCreedy West, where it’s 10.3% of metal revenue. The PEA was due in Q3. On September 17, Magna pushed the PEA and Crean Hill’s pre-feasibility study to the first half of October to account for Canada’s proposed Productivity Mega Deduction. The deduction would let miners write off Canadian development spending right away, instead of deducting 30% of the balance a year, so both studies’ after-tax returns should come out higher. Jessup said of the PEA on September 24, “essentially it’s all done,” and he sees a “very high probability” of a restart declaration shortly after the PEA comes out.
@StableBread

Fajasy on X

McCreedy West had “a few weeks” of development (the tunnels that reach new ore) ahead of its miners and no stopes (the blocks of ore being mined) ready to go when Magna Mining $MGMNF (TSX: $NICU) took it over in March 2025. So Magna spent 2025 catching up and missed its H2 2025 grade guidance, shipping ore at 2.64% copper equivalent (CuEq, which converts every metal into copper at set prices) in Q3 and 3.41% in Q4, below the 2.9-3.4% and 3.8-4.4% it guided. 2026 has gone better. In Q2, McCreedy West set Magna-era records for tonnage (98,446 tons) and cash margin, and production costs fell to US$144/ton processed from US$156 in Q1. Through H1 2026, McCreedy West produced 8.62M payable pounds of CuEq (the metal the mill and smelter pay for after recoveries). It needs 7.4-9.4M lbs in H2 to land in the 16-18M lbs guidance range, so repeating H1 would put the year inside guidance. Costs are inside guidance too. H1 cash costs (operating costs plus smelting and refining charges, per payable pound) of US$3.63/lb sit within the US$3.40-3.80 range. All-in sustaining costs (AISC, which add sustaining capital and corporate overhead) of US$4.39/lb also sit within US$4.20-4.70. Both exclude the precious metals stream held by Franco-Nevada $FNV, which buys half the mine’s gold, platinum, and palladium at a discount. Magna says the stream adds US$0.78-0.92/lb at its 2026 budget prices. Magna’s first reserve estimate for McCreedy West, effective December 31, 2025, came to 987,000 tonnes of probable reserves, which Magna says supports three years of production at its 2026 mining rate. Three years sounds short, but CEO Jason Jessup says it’s “in line with the reserves that McCreedy West has operated with since being restarted in 2003 by FNX Mining,” and that Magna “could have extended” the reserves. McCreedy West’s Intermain nickel zone isn’t in the reserves or the guidance. Jessup wants nickel to hold “north of $8” per pound “for at least a quarter” before restarting it, and says Magna could be shipping Intermain nickel to Vale $VALE “within 8 to 12 weeks” of a decision. At ~$7.48/lb nickel, the Intermain restart waits.
@StableBread

Fajasy on X

Magna Mining $MGMNF (TSX: $NICU) paid US$6.5M for a package of assets from KGHM $KGHPF, the Polish copper giant, including McCreedy West, now its only producing mine, and Levack, its flagship restart project. It paid ~US$3.7M in cash and ~US$1.4M in shares at closing, with ~US$1.4M due on December 31, 2026. It could also owe up to US$16.9M in milestone payments as the mines reach commercial production, including US$4.2M for Levack. Counting the milestones at their US$4.7M fair value, Magna valued the consideration at US$11.2M against US$25.0M of net assets. That’s why its 2025 results include a US$13.8M “bargain purchase” gain (US$25.0M − US$11.2M). It also took on reclamation liabilities with a fair value of US$9.8M and a precious metals stream held by Franco-Nevada $FNV, the royalty and streaming company, which it booked as a US$22.6M liability at the acquisition. Here’s Magna’s pipeline, from production to exploration: → McCreedy West (producing): Run since March 2025. All of its 2026 guidance comes from the 700 Footwall Copper Zone. → Levack (restart study): Connected underground to McCreedy West and idle but maintained since KGHM stopped mining in 2019. → Crean Hill (permitted): Past-producing nickel, copper, and precious metals mine southwest of Sudbury, Ontario, with a pre-feasibility study (PFS) due in the first half of October. → Podolsky and Shakespeare (later): CEO Jason Jessup pencils in Podolsky as the fourth mine “probably sometime in 2029,” and says Shakespeare, which would need its own mill, is “probably 5 years down the road.” → Exploration: 584 km² of claims across the Sudbury Basin. Copper pays most of the bills. In H1 2026, copper made up 68.4% of McCreedy West’s metal revenue, nickel 10.3%, and platinum, palladium, gold, and silver 21.2%. So despite the ticker (NICU, for nickel and copper), Magna today is a copper producer with nickel upside. Magna doesn’t own a mill. It trucks McCreedy West’s crushed ore to the Clarabelle mill run by Vale $VALE, pays Vale a fixed price per ton for trucking and milling, and sells the ore to Vale on delivery. It also has an ore selling agreement with Glencore $GLNCY for Glencore’s Strathcona mill. Magna’s financial statements report just two significant customers, and with McCreedy West’s ore going to Vale, changes in Vale’s terms hit revenue directly. In Q2 2026, a retroactive adjustment to the Vale contract roughly doubled the smelting and refining charges taken out of Magna’s revenue, to US$2.9M from US$1.4M. Incoming CFO Greg Huffman expects the charges to normalize in H2 2026.

What I’ve Been Up To

Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Not So Fast

Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Updates

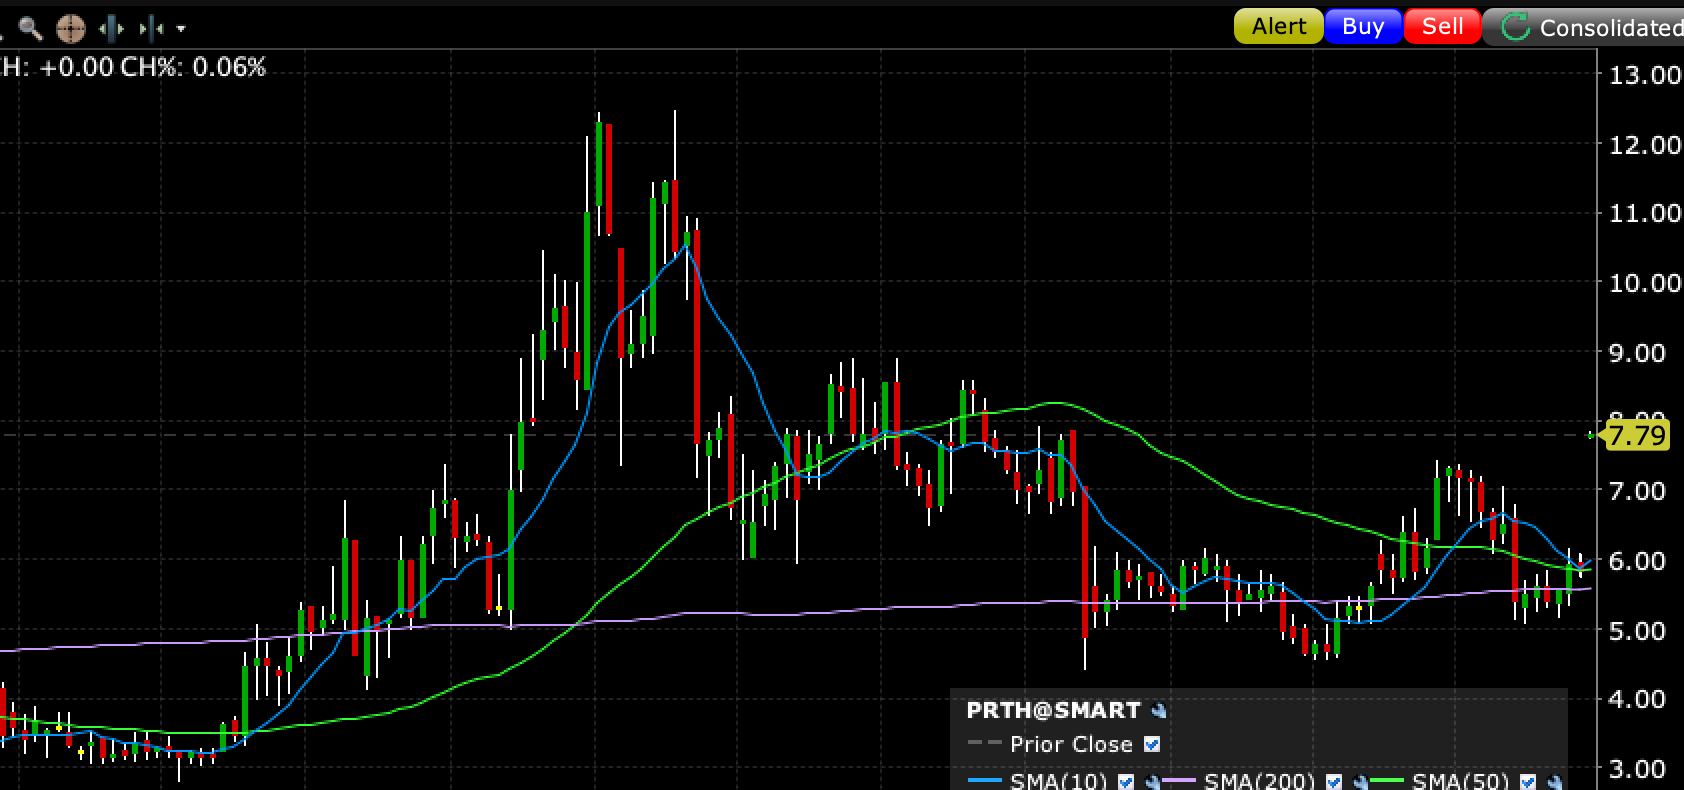
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
BNTC · long

Benitec Biopharma INC

Benitec Biopharma's BB-301 gene therapy is in a Phase 1b/2a trial for an ultra-rare muscular dystrophy.
Solid Power Still Has Promise

Solid Power reported a $0.11 Q2 loss and $419.3 million of cash, with its electrolyte pilot line and BMW and SK On validation central to…

Is The Bond Market Running On Empty?

U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
Publications we follow

Every publication on this site, hand-picked.

109 publications

Newsletters 92

X accounts we follow

Every account on this site, hand-picked.

74 accounts

Investor letters we follow

189 firms

Sectors

Ordered by how often our editor reaches for them.