Friday, October 9, 2026

Back to today

From X

@StableBread

Fajasy on X

The restart study due in the first half of October at Levack, the flagship mine of Magna Mining $MGMNF (TSX: $NICU), leaves out a zone where a hole reported in June cut 29.7% copper equivalent over 3.4 meters. Magna found the zone itself. In July 2025, a hole drilled into the footwall below Levack’s No. 3 orebody hit nickel-rich veins. Magna calls the area R2, short for “Rob’s 2,” and says R2 resembles the top of the Morrison deposit, where the nickel-rich veins of Rob’s Zone gave way to copper- and precious metal-rich veins at depth. As of June, R2 spanned ~300 meters vertically and ~150 meters north-south, and all 14 holes Magna had reported hit metal-bearing rock. The June hole’s 3.4 meters included 57.0% copper equivalent (CuEq, which converts every metal into copper at set prices) and 44.3 grams per tonne (g/t) of gold over 1.5 meters. In September, another hole extended R2 ~30 meters toward the No. 3 orebody. The veins are narrow. Magna reports lengths along each drill hole and estimates the veins’ true widths at 30-80% of those lengths, so the June hole’s 3.4 meters could be a vein 1.0-2.7 meters wide (30% × 3.4 and 80% × 3.4). In August, Magna finished a 2950 Level drift (a horizontal tunnel) that stops ~300 meters short of R2. CEO Jason Jessup said on September 24 that Magna plans to extend the drift to R2 “sometime in Q4.” From there, Jessup says Magna could start mining along the veins “as early as Q1 of 2027” and ship the ore to Vale $VALE, ahead of a resource estimate “potentially by the end of 2027.” Jessup says R2 can’t go into the restart study, a preliminary economic assessment (PEA), because it isn’t in a resource estimate yet. Once it’s added, he expects R2 ore to “displace some material in the PEA,” meaning replace some of the plan’s lower-grade tons, since it’s “much much higher margin.” Even after mining 1-2 tons of waste rock with every ton of vein (100-200% dilution), Jessup expects R2 ore to grade “10 to 15% copper equivalent,” 3-4.5x the 3.3-3.4% at McCreedy West, Magna’s producing mine (10% / 3.4% and 15% / 3.3%). Jessup also says “there are no streams or royalties on the precious metals” at R2. Franco-Nevada $FNV, the royalty and streaming company, holds a precious metals stream on two areas of Levack, but the technical report doesn’t publish their boundaries, so for now, investors only have Jessup’s word that R2 sits outside the stream.
@StableBread

Fajasy on X

Q2 2026 was the first quarter of positive FCF at Magna Mining $MGMNF (TSX: $NICU), but only because cash from March sales arrived in April. The quarter set Magna-era records for revenue and cash margin: → Revenue: US$21.5M, after the precious metals stream and higher smelting and refining charges. → Cash margin: Record US$6.4M, or US$1.41/payable lb, up from US$4.3M in Q1. → Operating cash flow: US$6.4M, including US$4.8M of March sales paid in April. → Free cash flow: US$3.7M, even though operating cash flow absorbed US$3.8M of exploration and evaluation spending, mostly at Levack, Magna’s flagship restart project. Adjusted for the US$4.8M of March sales paid in April, Q2 FCF was an outflow of ~US$1.2M, and H1 2026 as a whole was a US$10.5M outflow. At the mine level, McCreedy West (Magna’s producing mine) generated a US$10.8M cash margin in H1 2026, covering its US$3.6M of sustaining capital almost three times over. But Levack, corporate costs, interest, and working capital kept the company as a whole cash-negative. As of June 30, 2026, Magna held US$28.2M of cash. With net proceeds from Alpayana, the Peruvian mining group that bought 19.9% in August, the September deck puts cash at ~US$124M. Magna’s only debt is US$16.9M of unsecured 10% convertible notes due March 5, 2029, a third of which Dundee Corporation $DDEJF, a Toronto investment company, bought. They convert at CAD$2.00/share into 11.98M shares, or 3.8% of the current share count. Magna has funded itself mostly with equity, so the share count rose from 163.4M at the end of 2023 to 313.35M after Alpayana, up 91.8%. Options and share units add more. At June 30, Magna had 12.35M options at a weighted average exercise price of CAD$1.21 and 1.73M restricted and deferred share units. At CAD$2.45, 9.64M of the options are in the money, and exercising them would give Magna ~US$5.1M of cash. Counting the in-the-money options, the share units, and the notes, the diluted count is 336.70M (313.35M + 9.64M + 1.73M + 11.98M).
@StableBread

Fajasy on X

Half the gold, platinum, and palladium in ore from McCreedy West, the producing mine of Magna Mining $MGMNF (TSX: $NICU), goes to Franco-Nevada $FNV for $1,200 per gold-equivalent ounce, 29.0% of the average gold price in Q4 2025. Magna inherited the deal, a precious metals stream, when it bought McCreedy West from KGHM $KGHPF, the Polish copper giant. A stream is a deal where a financier pays a miner upfront for the right to buy part of its future metal at a discount to market. Magna’s stream gives Franco-Nevada 50% of the gold, platinum, and palladium in ore from McCreedy West and “certain areas” of Levack and Podolsky, until the deposits run out or 2048. Franco-Nevada pays 60% of the monthly average gold price per gold-equivalent ounce (platinum and palladium converted into gold) from McCreedy West, capped at $1,200/oz once gold tops $2,000. In Q2 2026, the stream cut net revenue by US$3.9M, so revenue would have been ~18% higher without the stream. CEO Jason Jessup called the stream “a bit of an overhang” on McCreedy West, and in April said its terms are “definitely open for discussion” with Franco-Nevada. The higher gold climbs, the more the stream costs Magna, and I wouldn’t count on Franco-Nevada softening the terms. Crean Hill, Magna’s permitted nickel mine, carries no Franco-Nevada stream, and Jessup says R2, the high-grade zone Magna found at its flagship Levack mine, has none either. At Q4 2025’s gold price, Magna kept 64.5% of the value of McCreedy West’s gold, platinum, and palladium (50% + 50% × 29.0%). That means a stream-free ounce from Crean Hill or R2 is worth 1.55x as much to Magna as one from McCreedy West (100% / 64.5%). The stream also covers two areas of Levack, including the Morrison deposit. Franco-Nevada’s filings set the price for its Sudbury streams at $400/oz, rising 1% a year from July 2011, and its later increases applied to McCreedy West only, so Levack’s price would’ve reached ~$460/oz by Q4 2025 ($400 × 1.01^14). So at Q4 2025’s gold price, Magna would keep 55.6% of the value of Levack’s streamed ounces (50% + 50% × ($460 / $4,141.90)), less than the 64.5% it kept at McCreedy West.

Not So Fast

Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.

Updates

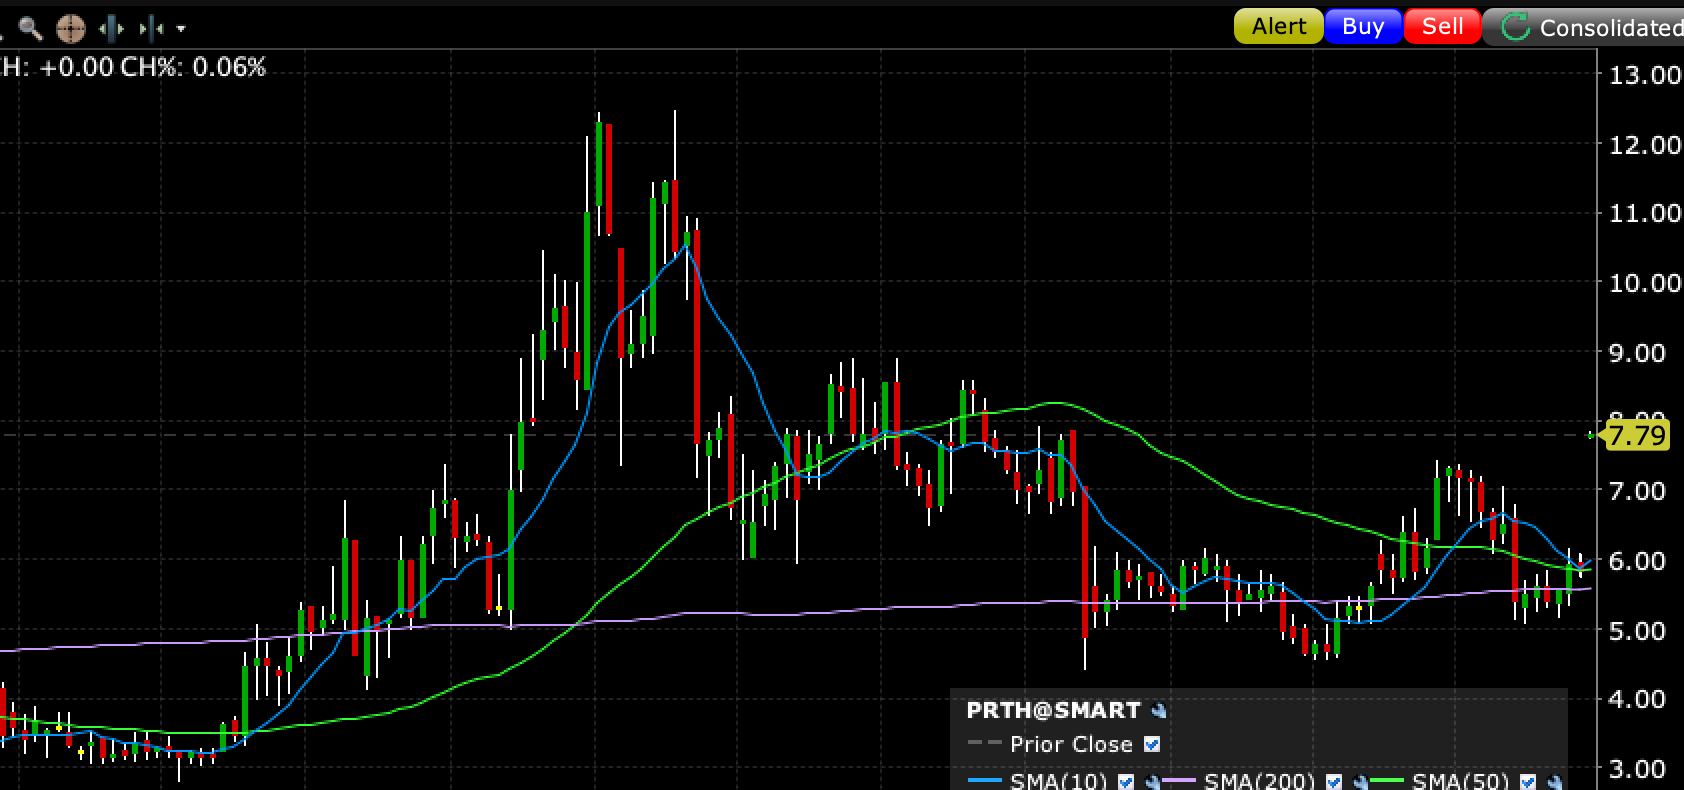
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.

Is The Bond Market Running On Empty?

U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).

Publications we follow

Every publication on this site, hand-picked.

109 publications

Newsletters 92

X accounts we follow

Every account on this site, hand-picked.

74 accounts

Investor letters we follow

189 firms

Sectors

Ordered by how often our editor reaches for them.