Not So Fast
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
What you need to know about the $BRUN news. https://t.co/ltboFSZJhC
Secondaries more likely with the reversal in bio discovery names this morning not less, they are coming --- almost all need money to fund their cash burning businesses $DNA $TXG $TWST $GRAL you are their liquidity if you want to fund them at 20-30x sales
Entravision $EVC down on the Univision deal as investors have completely forgot about the growing ad-tech business and are underwriting for a dying media company that plays non-stop Taco Bell ads.
Riley Exploration Permian raised oil production guidance after a Q2 beat, targeting 30% growth while trading at 6.52 times forward earnings.
 The Supercycle Investor
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
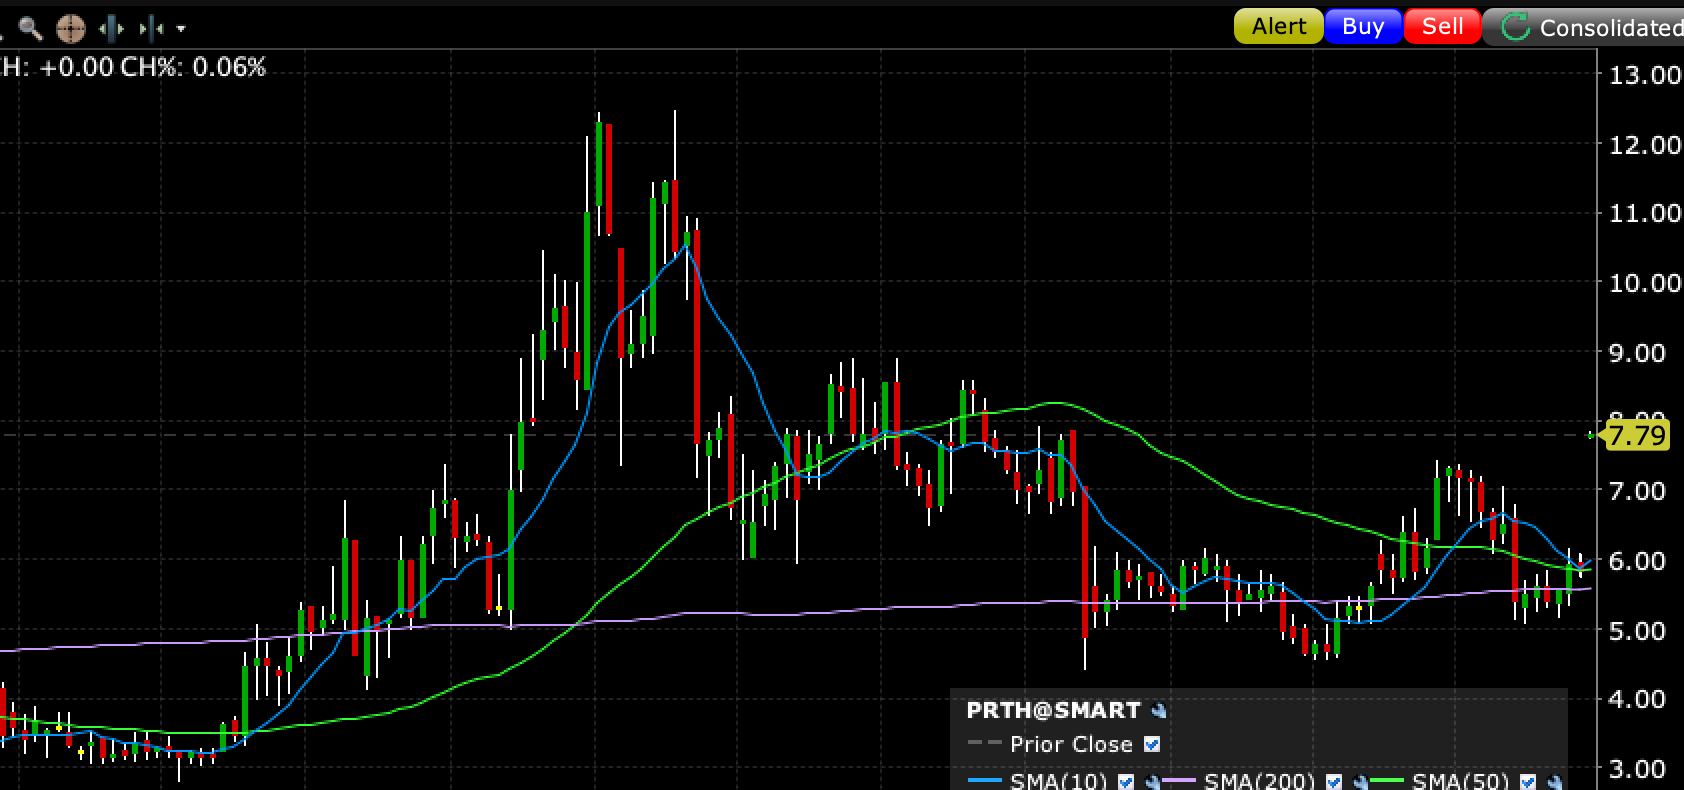
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
U.S. Treasury yields are testing credit and equity markets, while the discussion also targets recent changes at Glass House (GLAS).
Kronos Worldwide’s 27% inventory reduction added $120 million in cash inflows as chloride-based TiO₂ demand rises amid a sulfur shortage.
 Given Mahlangu
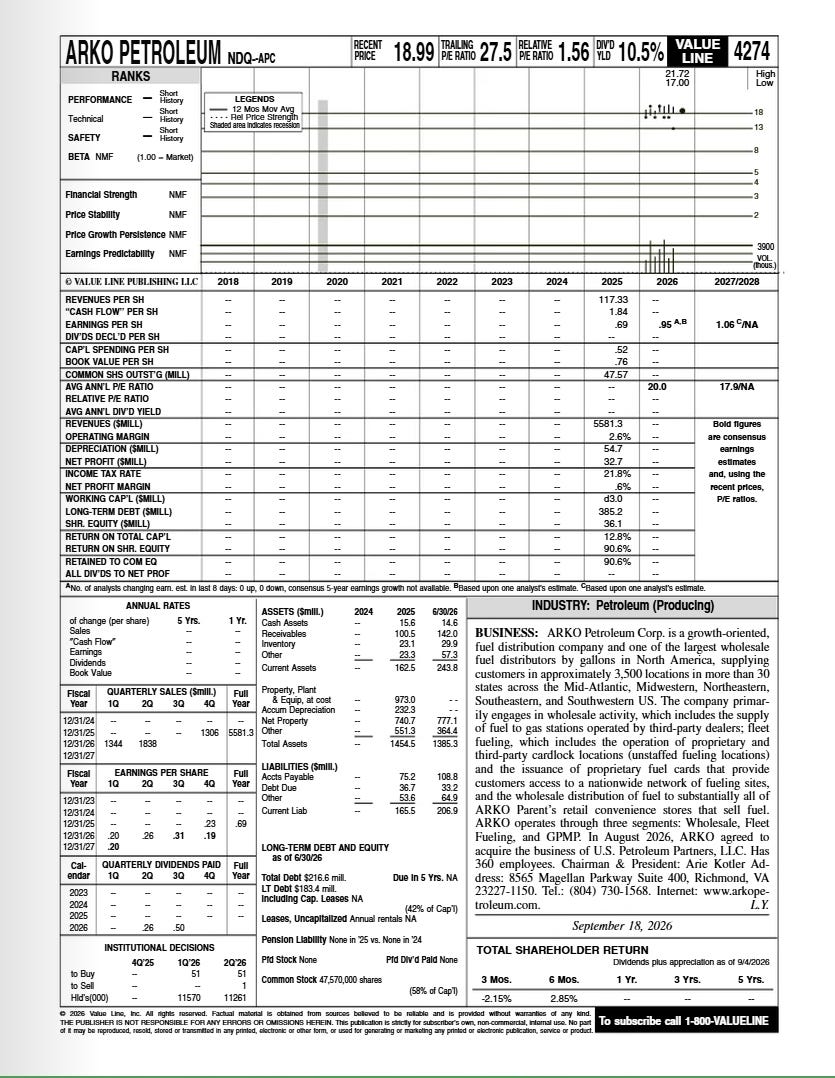
ARKO trades at 3 times estimated 2025 owner’s earnings, while its 73.6% APC stake exceeds its $473 million market cap.
Bumble trades at roughly 2x owner’s earnings and 4.76x enterprise value, with Whitney Wolfe Herd’s return central to a rerating case.
Evolus posted 21% quarterly revenue growth as U.S. facial-injectable spending bottoms, while making progress toward GAAP profitability.
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
Pioneer Bancorp’s acquisitions lifted loans 13.6% and Q2 net interest margin to 4.30%, but expenses, weaker profitability ratios and a…
 Crimson And Gold Research 4 clicks
 IMXI · short
International Money Express is shorted on the market pricing an 80-85% chance that Western Union closes its roughly $500 million…
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
GO Residential’s H&R REIT deal could trigger index purchases of 32 million units and re-rate its Lantower portfolio, despite related-party…
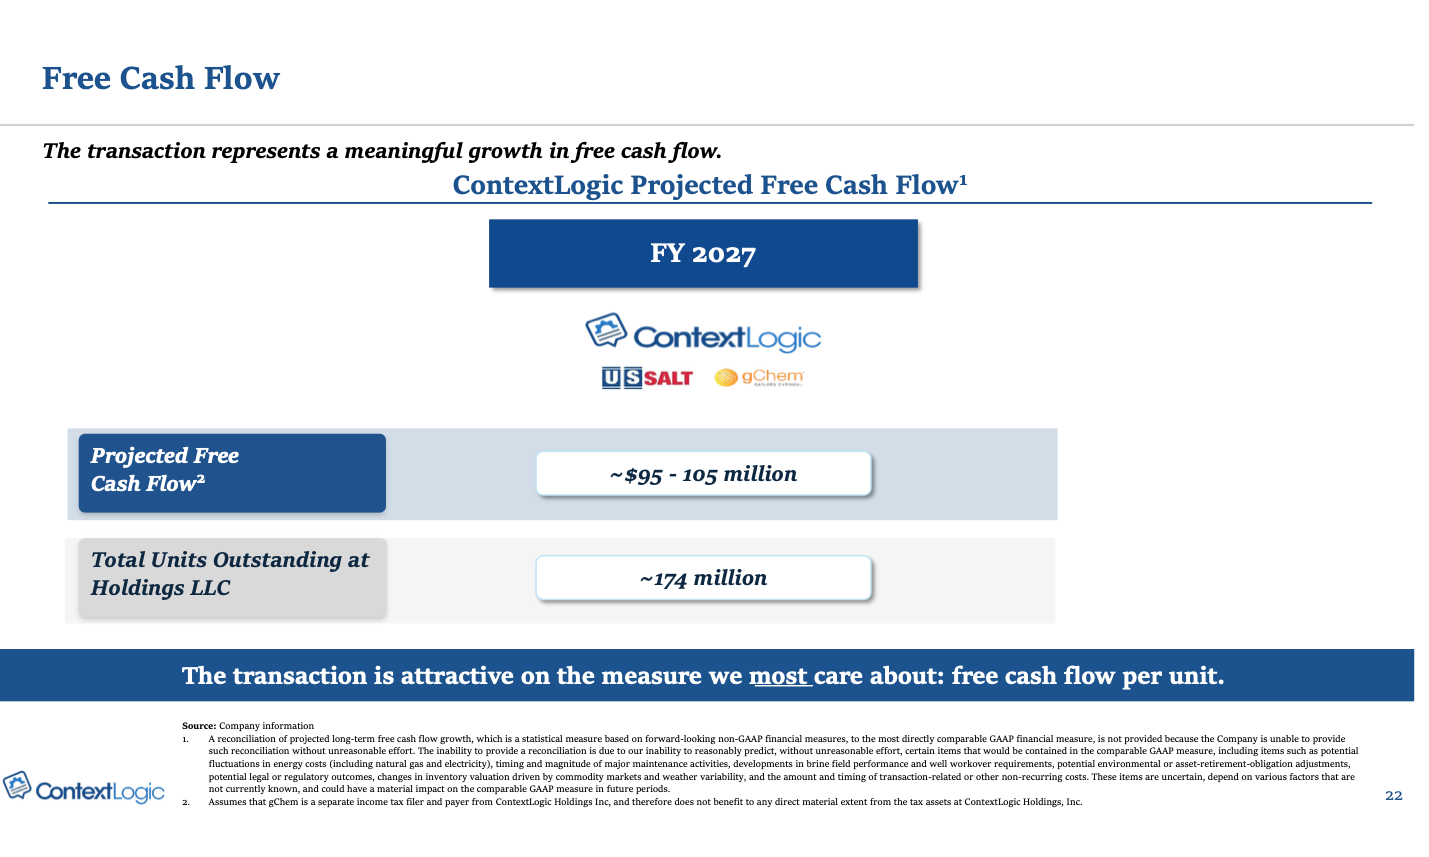
ContextLogic’s US Salt holds about 23% of the US and Canadian pharmaceutical-grade salt market, one of only two suppliers, supporting…
Jumia’s January 2028 $7/$15 call spread risks $1.15 for up to $6.85 if cost cuts and marketplace growth deliver adjusted EBITDA and…
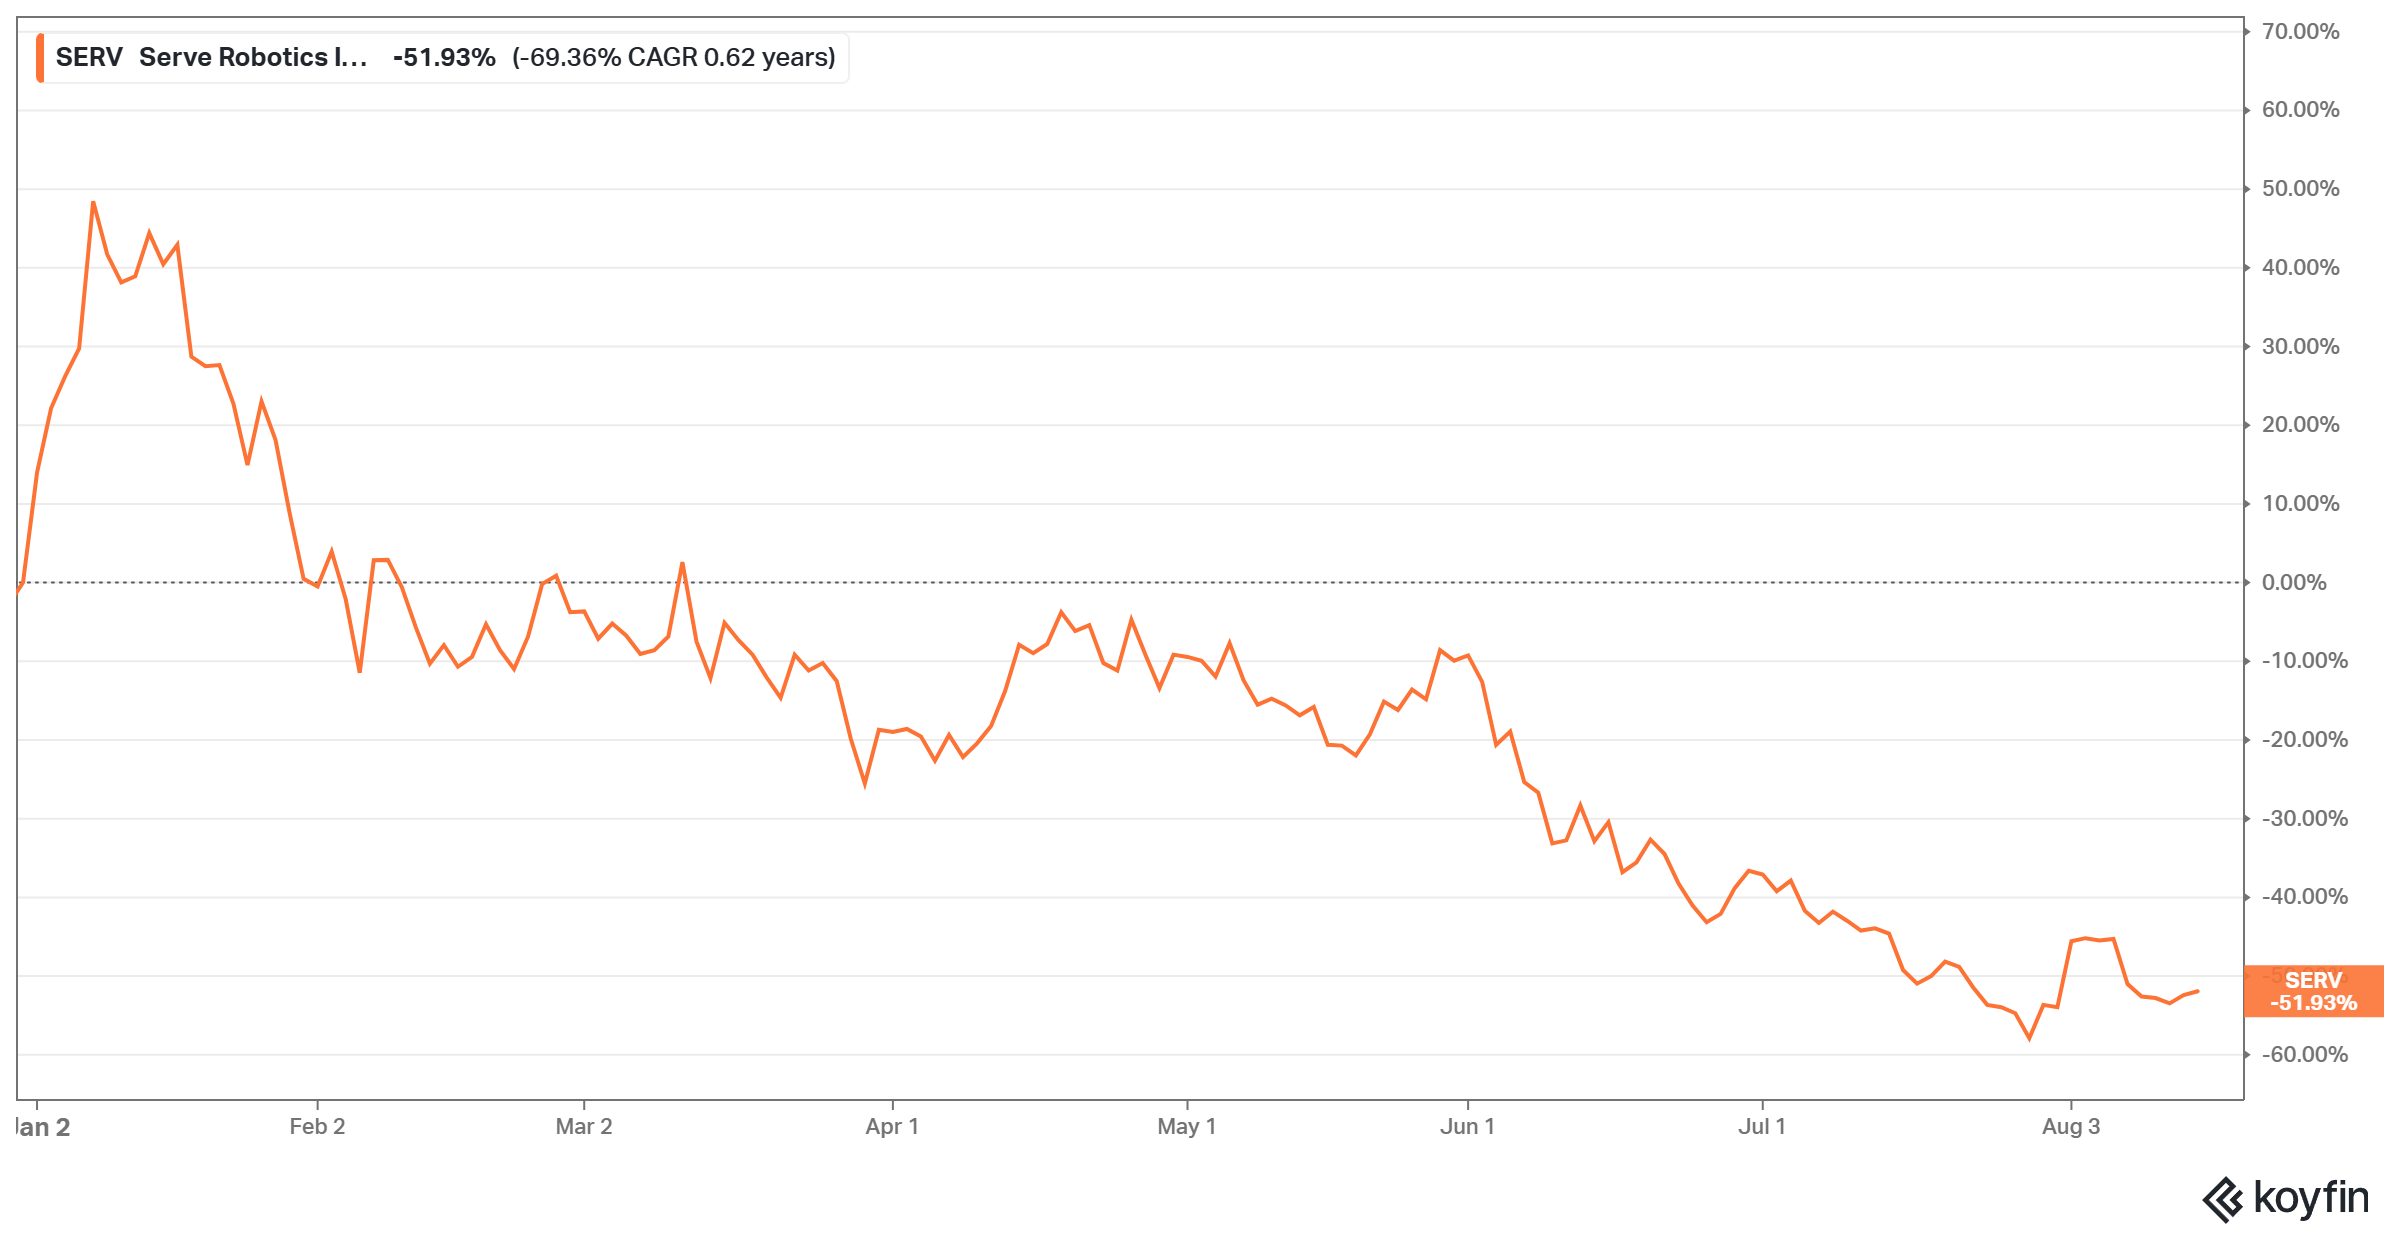
DoorDash’s integrated autonomous-delivery strategy contrasts with Uber’s 2026 divestment of Serve Robotics, its former delivery-robot…
E.W. Scripps, Team Internet, Monro, doValue and Inter & Co feature as special-situation trades involving mergers, asset sales, leverage and…
Entravision’s Smadex ad-tech unit grew Q2 revenue 230% year over year, underpinning a re-rating thesis despite its legacy Spanish-language…
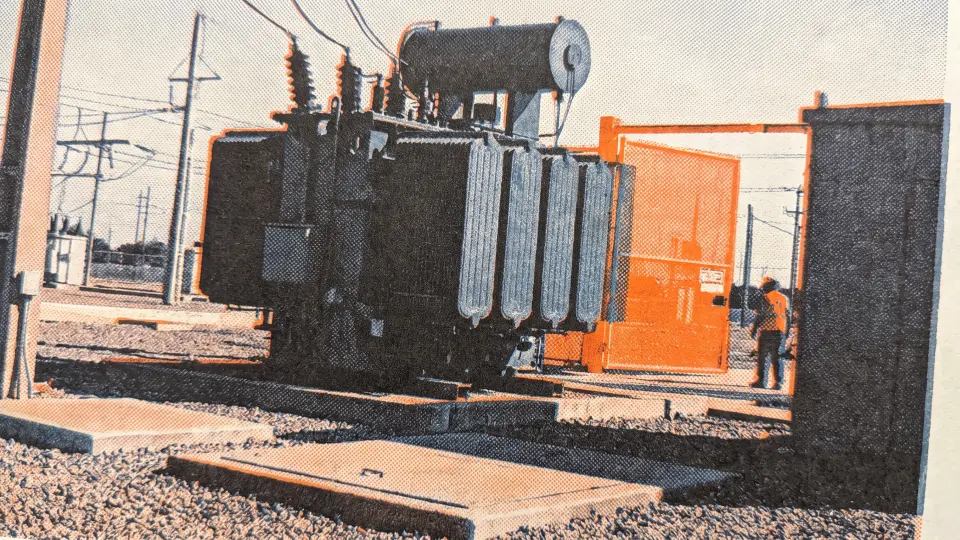
JinkoSolar sold control of its Florida solar plant to a Delaware entity run by China’s “Sun King” family, potentially sidestepping new…
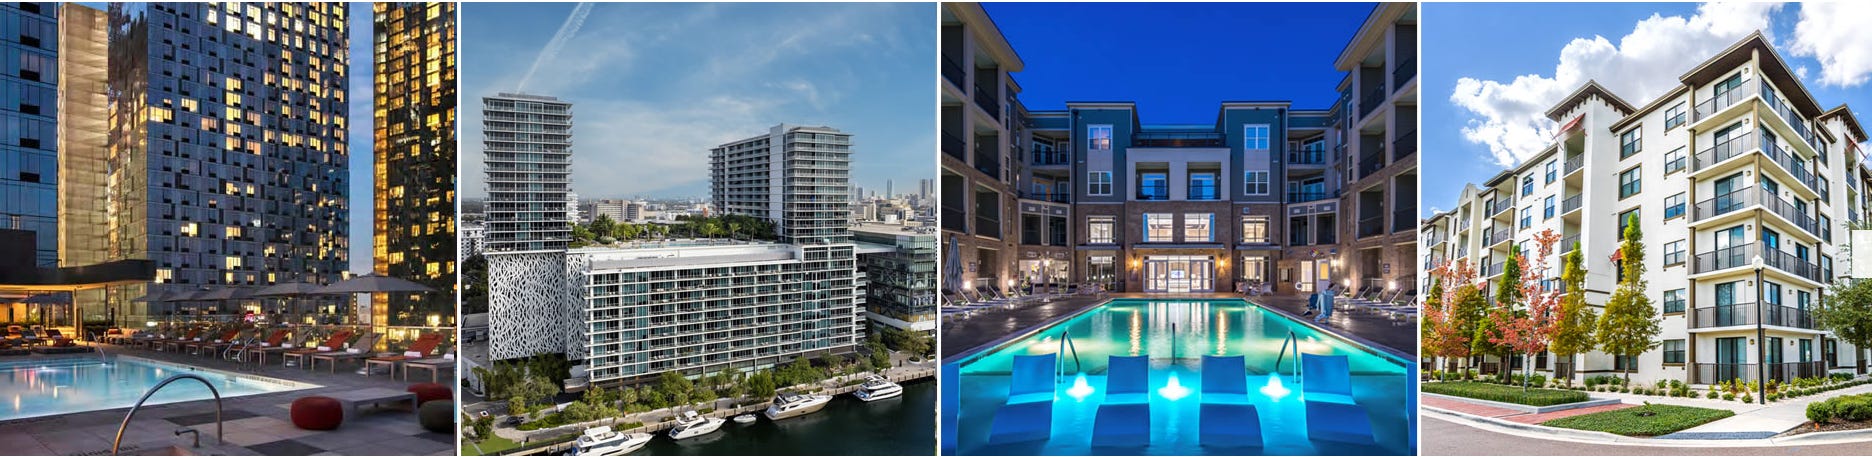
H&R REIT’s C$12 GO Residential deal gives unitholders 67% of the combined company, while CEO Thomas Hofstedter’s family affiliates cash out…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.