Applied Optoelectronics targets $1.1 billion in 2026 revenue as 800G and 1.6T data-center demand drives capacity expansion, despite…
SA Infinity Curve Sep 29 2 clicks Gentherm’s Oct. 1 Reverse Morris Trust with Modine adds commercial and off-highway operations, leaving THRM at 7.4x pro forma EBITDA with…
S Value Don't Lie Sep 28 3 clicks
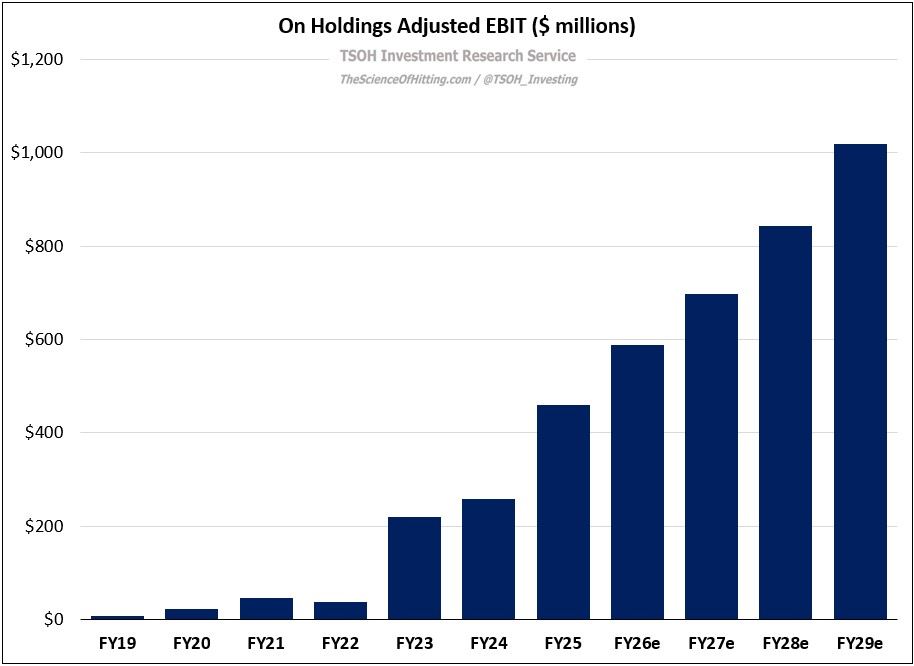
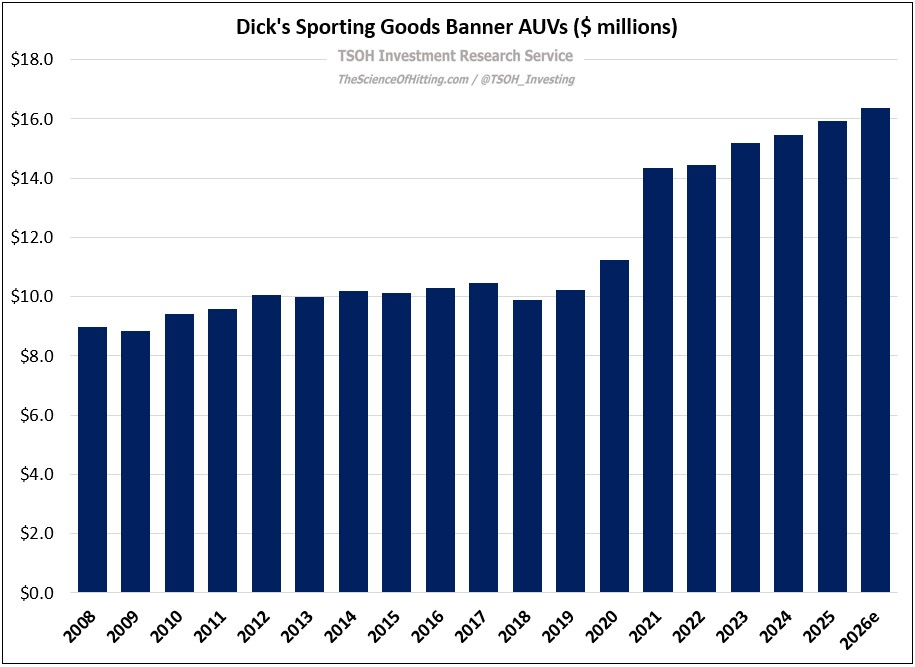
On Holdings targets premium growth through 2029, using LightSpray soccer cleats and higher pricing, with ASPs rising from $145 to $170…
S TSOH Investment Research Sep 28 4 clicks
NAIC oversight missed Delaware Life’s $13.34 billion affiliated-bond exposure and permits capital treatment that props up Brighthouse’s…
S Mispriced Assets Sep 27 1 click
BPRE trades 45% below NAV as Saba and Bulldog press for buybacks or a manager change, challenging Bluerock’s incentive to preserve…
S Investing 501 Sep 27 4 clicks
VersaBank uses cash holdbacks and put-backs to buy point-of-sale loan cash flows, with C$7 billion in assets and AI-enabled real-time…
S Substack von Philipp Sep 26 5 clicks
GitLab's Q2 FY2027 beat and raised guidance reflect large deals, paid consumption growth and AI demand, while valuation rests on revenue…
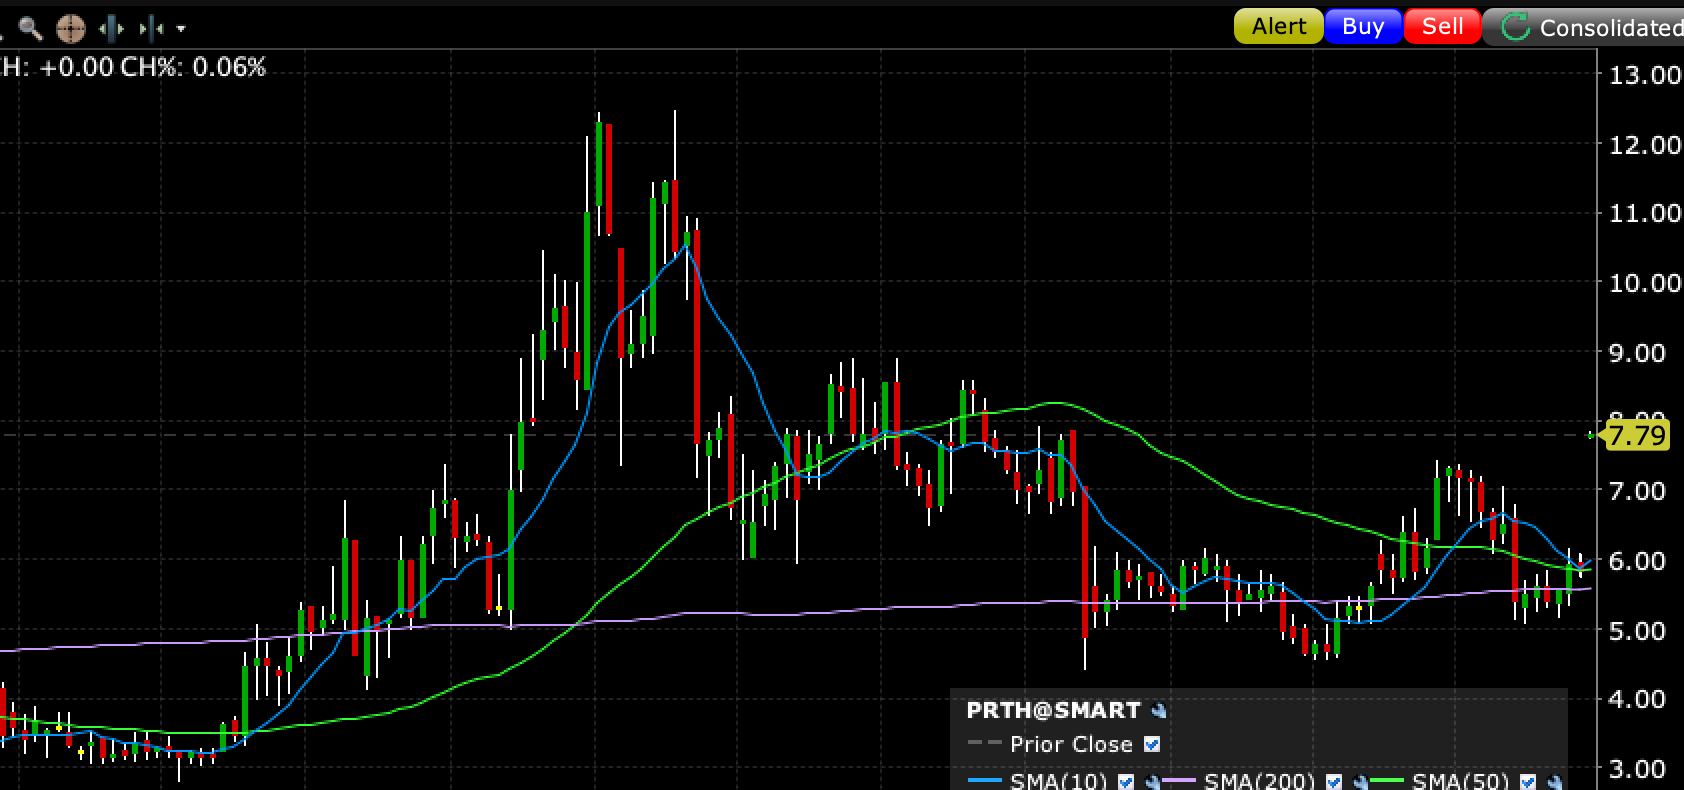
SA Research and Value Sep 26 3 clicks FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
S Nat Stewart - Stock Picking Newsletter Sep 25 12 clicks
Oklo shares have fallen 77% since October 2025 as commercialization slips beyond 2027, revenue estimates fall and dilution continues.
SA Ian Bezek Sep 25 5 clicks TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
S TSOH Investment Research Sep 25 5 clicks
SFIX · long Stitch Fix’s 2017 IPO rested on overly ambitious long-term growth expectations and an unrealistic definition of its addressable market.
BL Value Investors Club Jun 30 1 click
Mach Natural Resources' Q2 distributable cash fell to $60.1 million as development spending rose, prompting a distribution cut; its units…
S HFI Research Sep 25 4 clicks
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
BL Cestrian Capital Research Sep 25 7 clicks
AAON's BASX data-center cooling business targets $1 million to $1.5 million per megawatt, with new capacity and backlog conversion expected…
S Monte Independent Investment Research Sep 25 8 clicks
Firefly Aerospace ended Q2 2026 with $1.5 billion backlog and a 2.49x book-to-bill ratio, adding lunar, defense and launch contracts for…
S Monte Independent Investment Research Sep 24 16 clicks
Birkenstock targets 13–15% annual revenue growth through FY2028, driven by APAC expansion and closed-toe footwear, while trading at 13.44…
SA Roman Vitasek Sep 24 4 clicks ZIM’s proposed deal carries a claimed 23% spread and 110% IRR by Q4 2026, with Q3 and Q4 dividends potentially raising returns if closing…
S Calvin Blissett Sep 23 15 clicks
Turning Point Brands reaffirmed 2026 guidance after a CEO change, while ALP and FRE expansion has compressed margins through marketing and…
SA Caffital Research Sep 23 1 click Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
S Monte Independent Investment Research Sep 23 4 clicks
New Era Energy & Digital secured a 20-year Vistra power deal for 200 to 207 MW, reducing Phase 1 risk for its planned 1.4 GW West Texas AI…
SA Ryan Canady Sep 23