TSOH Weekly Roundup (09/25/2026)
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million refinancing, and Bob Chapek’s account of Disney succession.
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million refinancing, and Bob Chapek’s account of Disney succession.
To $FOUR credit, they've already been buying back lots of stock and recently killed the Up-C structure (which are terrible) https://t.co/0kRHGBybWV https://t.co/BBTKz873dC
@JJNews002 bought a little of it too $ABVX
$CXW got a new President/CEO today. https://t.co/7WpulDuHkg
@srg444 Me looking at $MGM trading at $32 when Osaka asset is worth 💰 https://t.co/jvVZZ37LP0
Vista Energy's Q2 2026 production rose 32% and revenue 89% as Vaca Muerta acquisitions expand its Argentine export platform and cash…
 Alan Galecki 5 clicks
Firefly Aerospace ended Q2 2026 with $1.5 billion backlog and a 2.49x book-to-bill ratio, adding lunar, defense and launch contracts for…
Birkenstock targets 13–15% annual revenue growth through FY2028, driven by APAC expansion and closed-toe footwear, while trading at 13.44…
 Roman Vitasek 4 clicks
ZIM’s proposed deal carries a claimed 23% spread and 110% IRR by Q4 2026, with Q3 and Q4 dividends potentially raising returns if closing…
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
ZIM faces Israeli review of Hapag-Lloyd’s $35-per-share bid, with $2.46 billion cash and elevated transpacific rates supporting potential…
 Melissa Tucker

Shift4 trades at 6.5x EBITDA despite 11% reported organic growth, with Shift4 Dine equipment leases cited as evidence of net-new merchant…
Texas Instruments, ON Semiconductor and Vishay are rated Accumulate on rising robotics demand for analog, power and discrete chips after a…
Cellebrite converts more than 110% of EBITDA into free cash flow and trades at 12.5 times free cash flow, with management targeting 15% or…
Innodata's new Meta contract for long-horizon agent personalization ties the data company to Meta's Muse AI assistant, despite Meta's Scale…
 GPK · long
Graphic Packaging (GPK) is pitched as a long with $22 fair value, implying roughly 100% upside, based on its low-cost paper-based packaging…

Haw Par combines Tiger Balm’s stable cash flows with property, leisure and healthcare operations plus stakes in UOB and UOL.
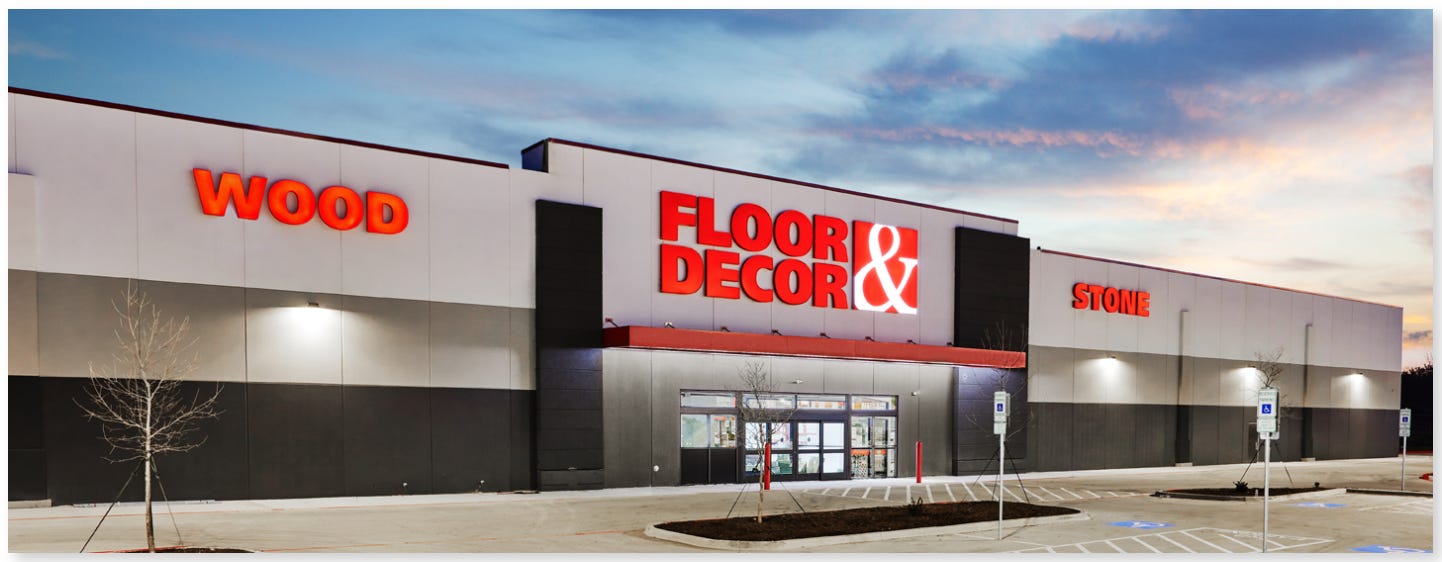
Floor & Decor operates 262 warehouse-format flooring stores, pairing broad in-stock hard-surface selection with design services as it gains…
Netflix’s Warner Bros. Discovery bid pushed Cinemark down 25% in two weeks, raising concerns that Warner Bros.
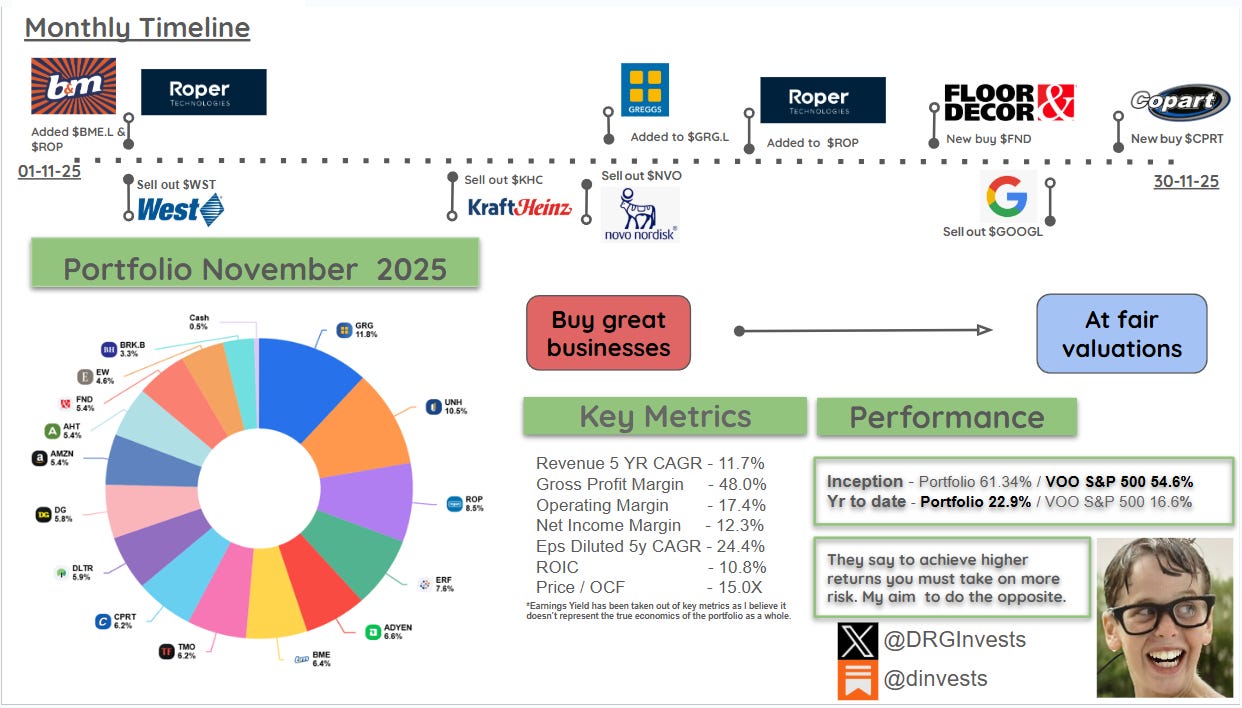
Portfolio gained 0.6% in November and 22.9% in 2025, adding Floor & Decor and Copart while exiting West Pharmaceutical, Kraft Heinz, Novo…

National Beverage’s rare share repurchase is framed as a buy signal, with 50% upside projected.
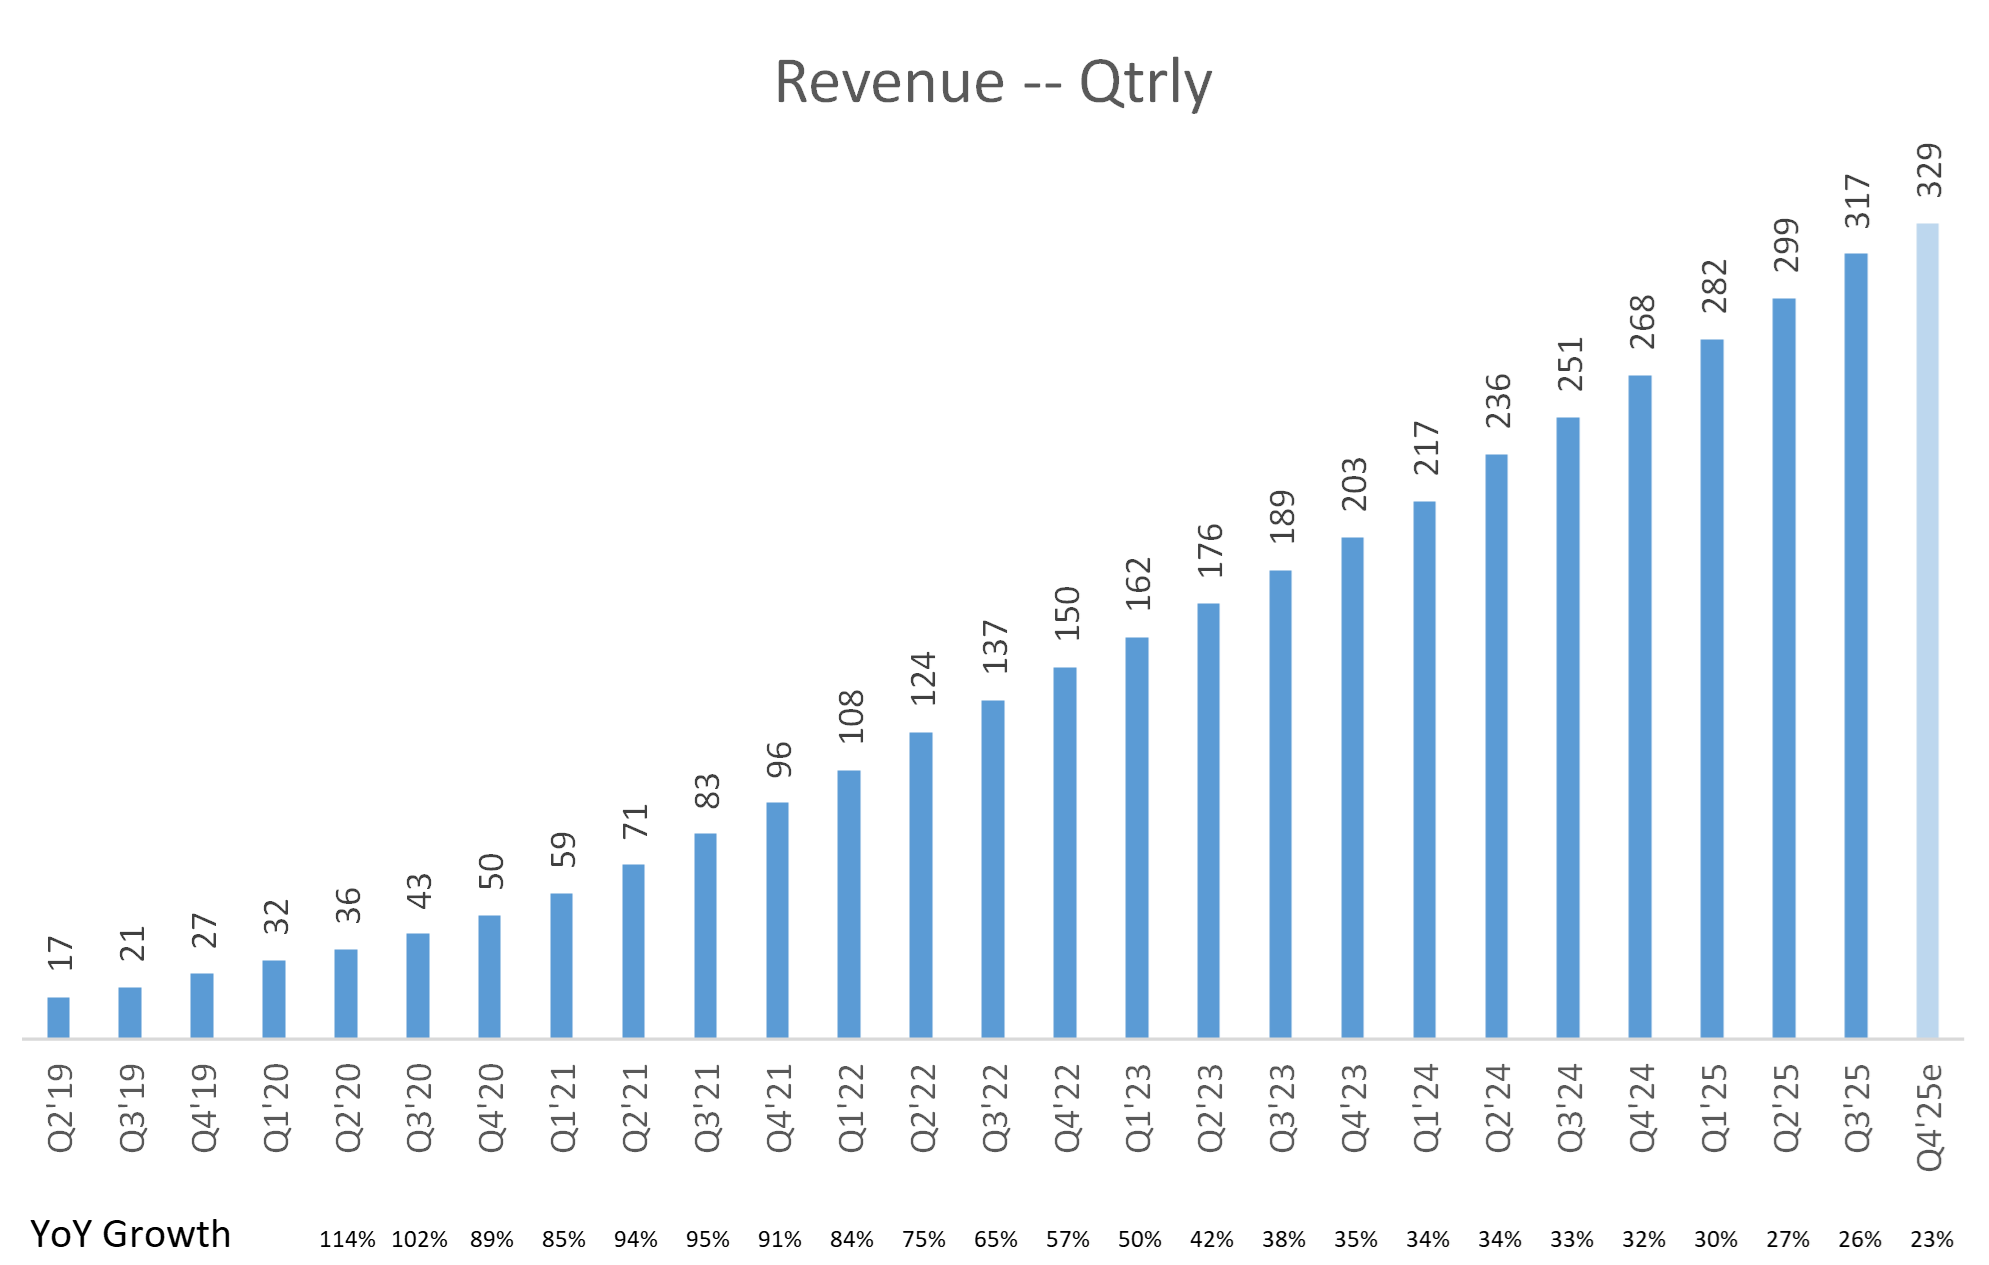
Monday.com combines work management, CRM, Dev and Service on a flexible core platform, with 90% gross margins and AI disruption risk…

Domino’s and Greggs carry 7% and 6.7% declared UK short interest as weak consumer spending pressures volumes, with Greggs’ valuation…

Argentine banks, tariff-exposed stocks and Customer’s Bancorp anchor an earnings-season watchlist after Milei’s election victory,…
Grindr received a non-binding $18-per-share acquisition offer.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.