Aggressive Portfolio Trades: Buy Vail Resorts, Buy ORR, Short GEO
Vail Resorts, down 60% since 2022, is pitched for an El Niño-driven ski-season rebound; the portfolio also buys ORR and shorts GEO.
Vail Resorts, down 60% since 2022, is pitched for an El Niño-driven ski-season rebound; the portfolio also buys ORR and shorts GEO.
Fantastic $NRP update from John. Particularly appreciate his capital allocation framework and view on why paying out 100% of cash flow makes the most sense. https://t.co/6LngKKV9hC
$LUXE keeps going no bid in this market, but I think the risk/reward here is excellent https://t.co/fCvW4k7PEI
$CENX is a non-AI bottleneck https://t.co/L0PvNNH4HK
Artemis is going to be a huge driver to $LUNR growth over the next 5 years. $2b market cap @ $13 / share kind of feels like early $RKLB at $2b @ $5/share. https://t.co/KaaQ7mFlSt
If you ever owned recently acquired $CRAWA, you might also follow $PKOH (family ties). It’s is up 138% this year. Logistics and supply chain solutions is a great trend to follow. So many stocks have seen their valuation re-rate, in what’s typically been a low P/E industry https://t.co/6xaCGQf5nF
Quantum Computing, QUBT, sold its first Dirac-3 system, added a second fab through acquisition and is building photonics capabilities…
 Marc Gerstein
Ultra Clean Holdings targets a $4 billion annualized revenue run rate by H2 2027 through manufacturing expansion and a broader…
Anterix’s 900 MHz spectrum could be worth $2.5–$7 billion, versus a $1.41 billion enterprise value, but insider selling and lumpy…
 The Market Auditor 2 clicks
Special-situations survey flags Cooper’s $3 billion buyback, Grab’s $900 million repurchase, and Beretta’s $44.80 partial tender for Sturm…
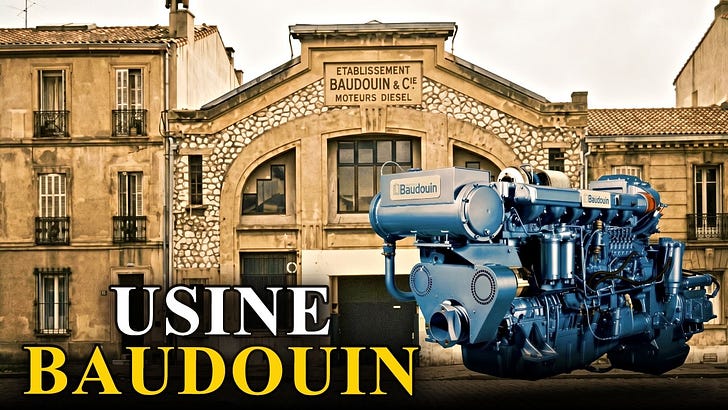
Weichai Power built a global engine group through Baudouin and a 46% stake in PSIX, positioning both for large-bore generator demand from…
STMicroelectronics, Navitas and Wolfspeed offer contrasting power-semiconductor cases tied to NVIDIA’s 800V AI data-center architecture,…
Diamond Estates Wines & Spirits plans to expand grocery and export sales, invest in six brands, and improve winery operations through FY29.
Vizsla Silver's Panuco project in Sinaloa remains shut after nine workers were found dead, delaying construction of a fully funded 17.4 Moz…

Copart’s 4Q26 revenue grew 2.4% as U.S. insurance volumes fell 7.5%, while a customer loss and higher yard costs pressured profits despite…
Kodiak Sciences expects Phase 3 DAYBREAK results for Zenkuda and KSI-501 in wet AMD, with durability and vision outcomes key beyond…
 Sam Mancini
 TPLKF · long
PVA TePla (XTRA:TPE) is presented as a long position.
Karman Holdings (KRMN) is upgraded after a 68% drop, with 24% organic growth, a $1.3 billion backlog and higher 2026 guidance offset by…
 Dhierin Bechai 1 click
Ethos relies on three carriers for 88% of revenue as TruStage payment failures triggered policy lapses and Family First Life publicly…
Talos Energy is raising standalone production guidance without added capex while using offshore cash flow to fund Shell acquisition and…
 Capital Connoisseur
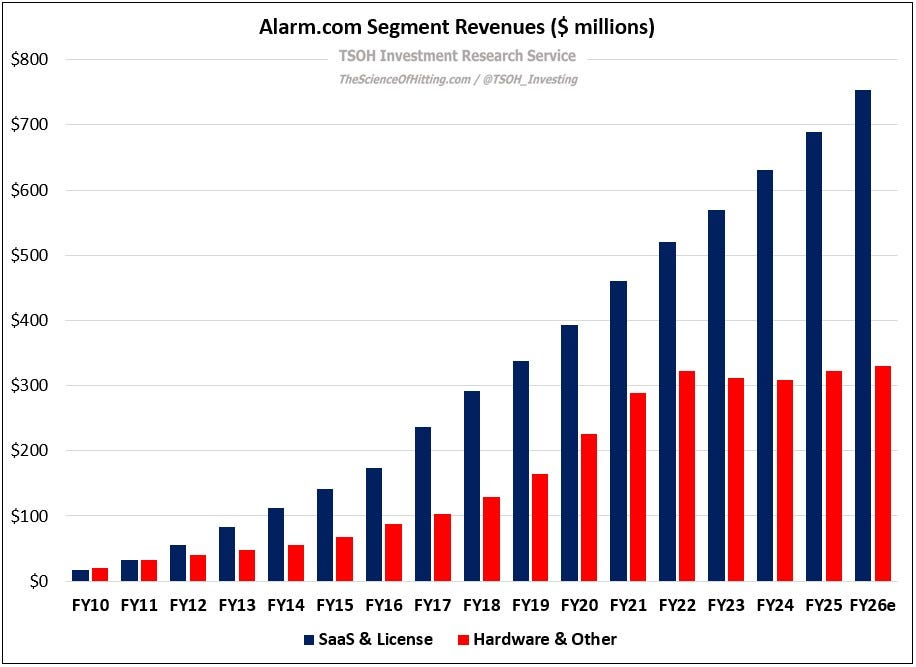
Alarm.com, founded after CEO Steve Trundle’s bad home-security experience, has fallen from $105 in 2020 to about $55, testing whether…
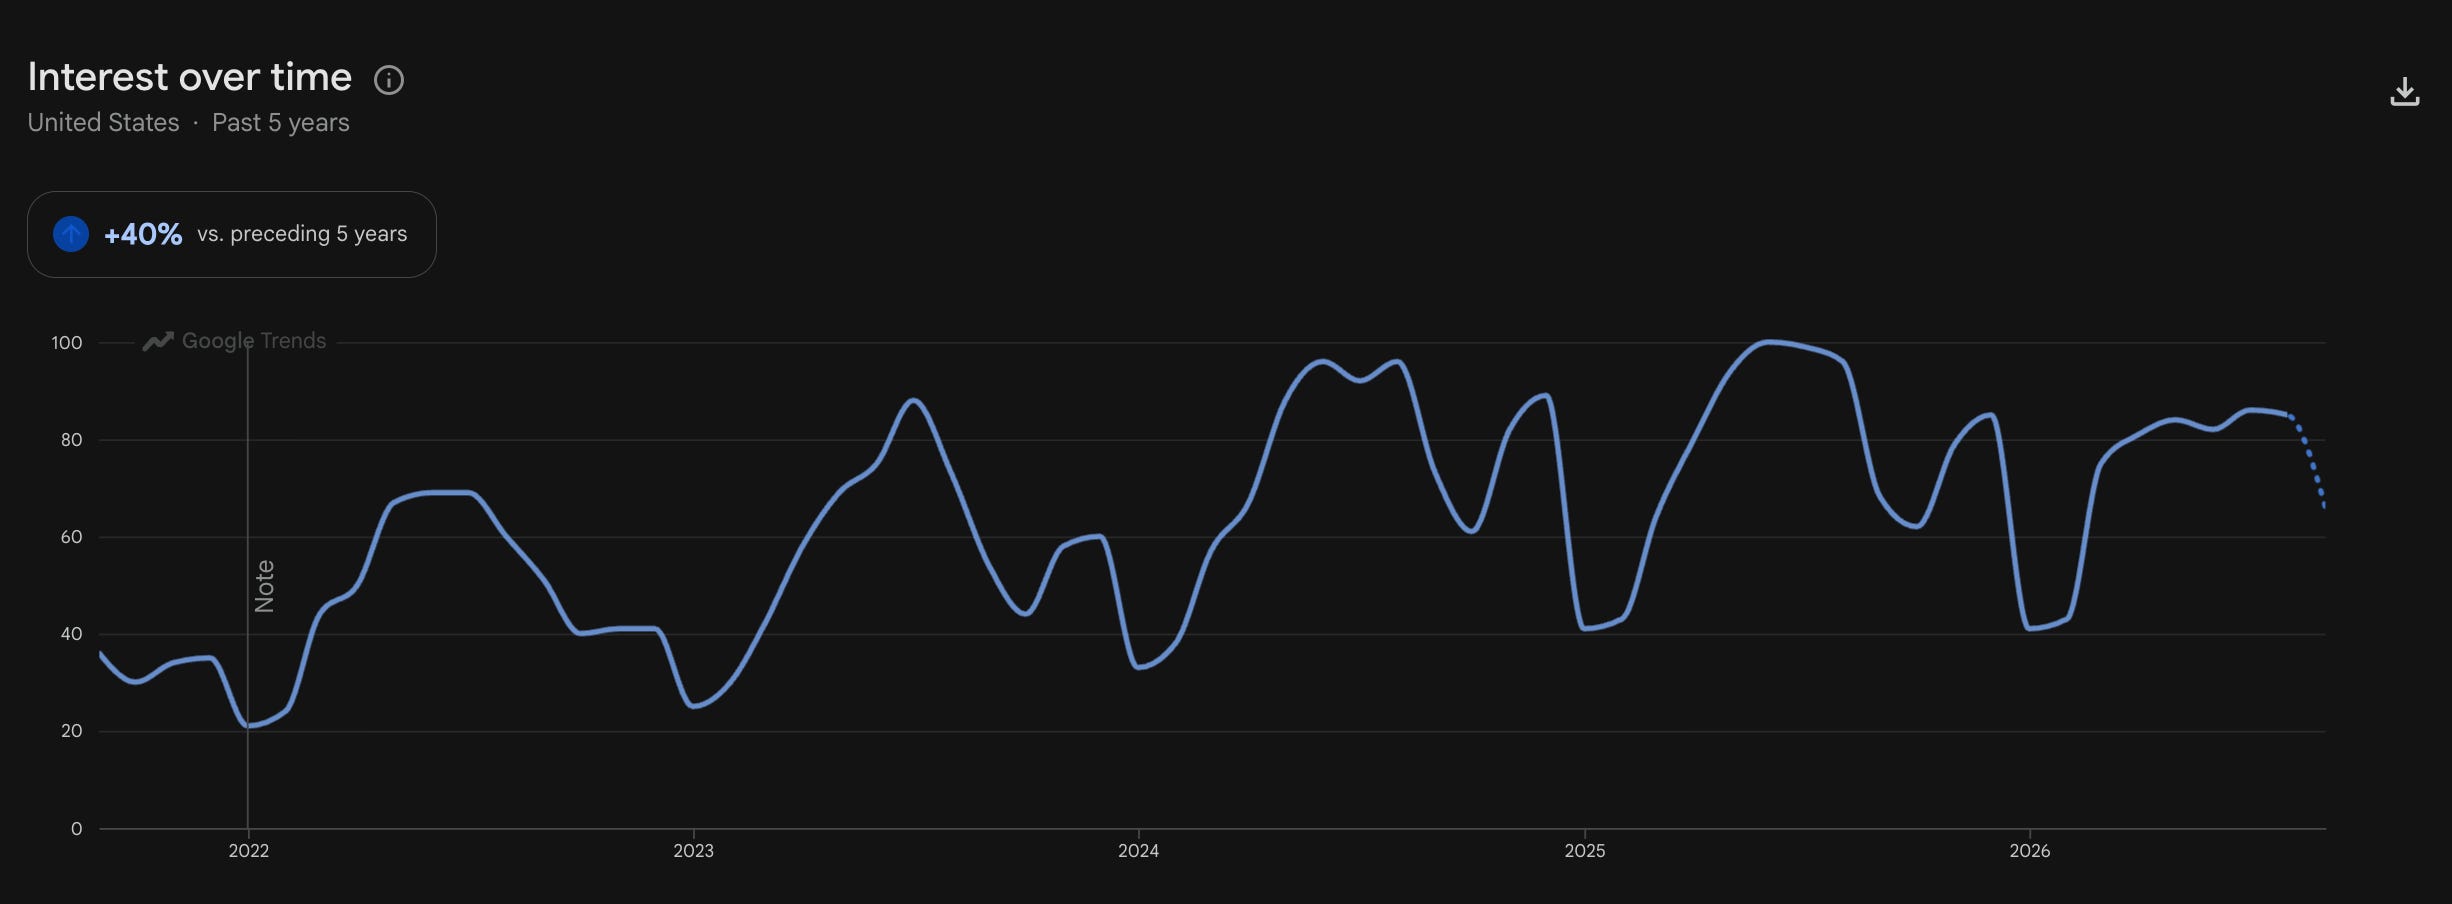
Genius Sports aims to turn official sports data into AI-driven, real-time advertising, with media and ads already about 40% of revenue.
Oak Bloke’s 2026 picks have returned 37% in GBP, with AltynGold, Geiger Counter, Silvercorp and China-focused trusts still rated buys…
Crocs’ core brand surpassed $1 billion in quarterly revenue, while HEYDUDE weakness, tariffs and 2025 impairments weigh on shares trading…

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
 Ron Ferrie 3 clicks
Groupon CEO Dušan Šenkypl and CFO Rana Kashyap discuss rebuilding the local-experiences marketplace with AI infrastructure, better…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas Capital Connoisseur Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.