Ethos' Biggest Distributor by Head Count Ranked It Last on Stage
Ethos relies on three carriers for 88% of revenue as TruStage payment failures triggered policy lapses and Family First Life publicly ranked Ethos last among insurance partners.
Ethos relies on three carriers for 88% of revenue as TruStage payment failures triggered policy lapses and Family First Life publicly ranked Ethos last among insurance partners.
$GPGI Stagnating credit card manufacturer (fka CompoSecure). Levered up 4x to acquire commodity plastic injection molding company Husky. Last month CEO departed, this week CEO and CFO of Husky left. Now rudderless with very ambitious guidance almost certain to get revised lower.
@cfrischer1 validation of what $NN CFO Tim Gray said at Seaport a few weeks back: https://t.co/OT4MFWbPxQ
$NN https://t.co/q3EOINP0pt
Think signal value for $NN is very high here. Ajit Pai, Brendan Carr’s mentor at the FCC, is Pres and CEO of CTIA. Execs from $VZ and $T are chair and vice chair. Unlikely they put Mariam on the board unless $NN future is bright. 💯% Pai knows what is happening behind FCC doors. https://t.co/4Jtm3aiAf9
Sounds like terrestrial GPS is being prioritized $NN https://t.co/EZoHuCydcB
$NN https://t.co/WSPZtvXkj1
Terrestrial backup to GPS is essential. $NN https://t.co/sCRxCPCldm

USA Compression targets nearly 30% full-year EBITDA growth as JW Power synergies, telemetry and maintenance reduce costs; its units yield…
 Ron Ferrie 3 clicks

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare…

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
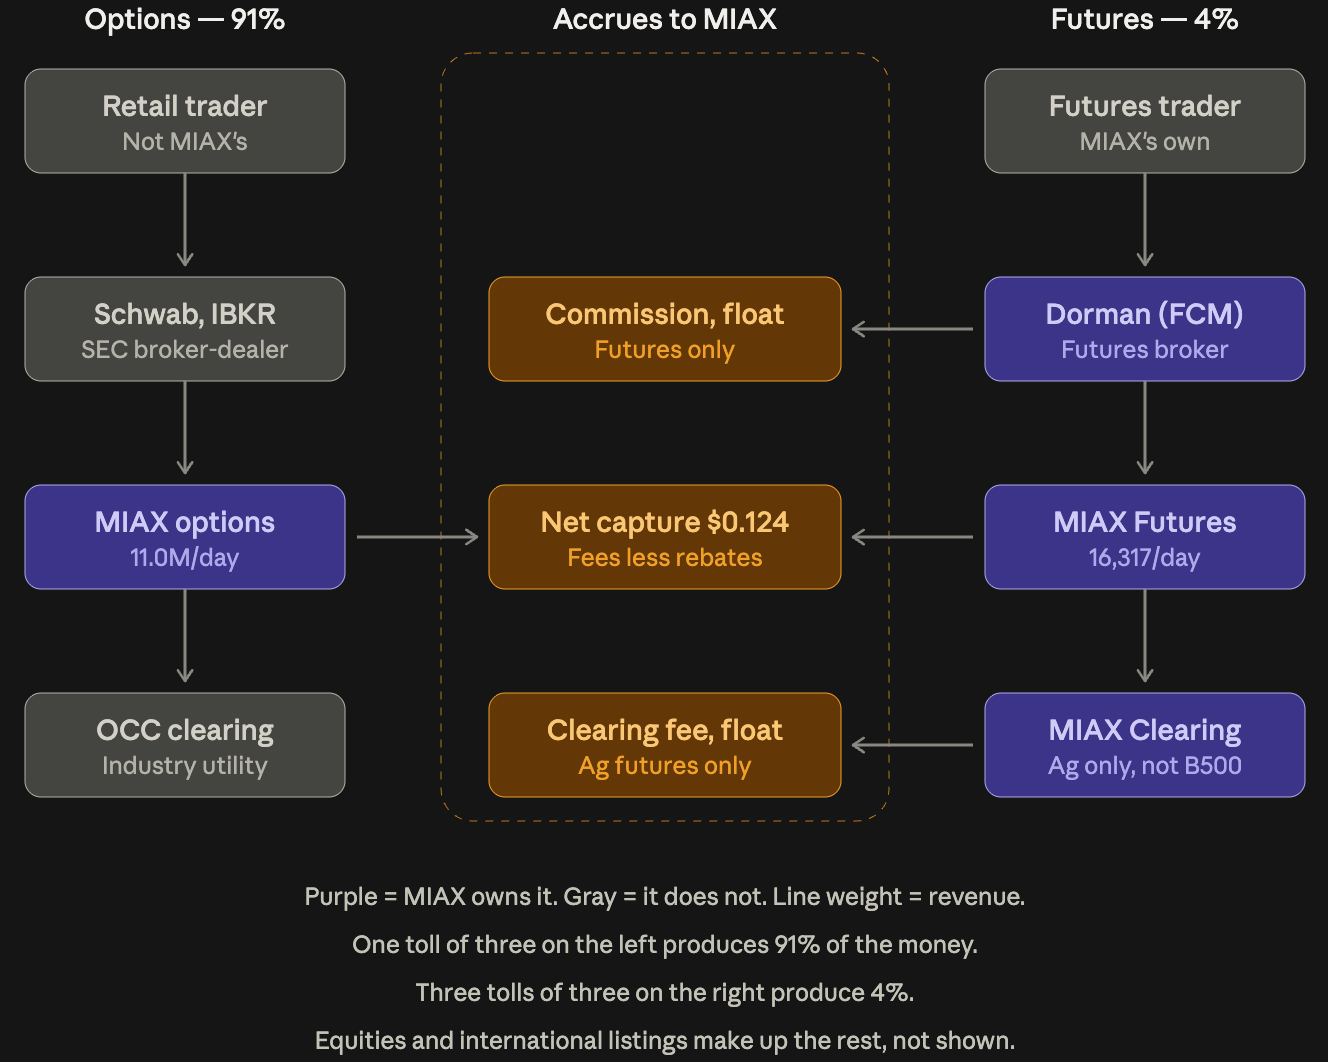
Miami International Holdings, the No. 4 options exchange with 17% share, trades at 12x forward EBITDA despite 35% revenue growth, 54%…
 TPC 2026-08-27
Tutor Perini’s Q2 revenue rose 19% to $1.64 billion as higher-margin megaprojects lifted construction income 54%, prompting higher 2026 EPS…
 The Curious Analyst
Cal-Maine, the largest U.S. egg producer, trades at 1.6x book versus a 2.1x 20-year median, with net cash and investments equal to 23% of…
STNE 2026-08-25 StoneCo's buybacks and special dividend produced roughly 39% H1 shareholder yield as Brazil's rate cuts slow and competition persists.
 IWA Research 3 clicks
Planet Fitness runs 2,930 clubs and 21.5 million memberships through an asset-light franchise model funded by $15 monthly dues, royalties…

El Al trades near 2x EBITDA after wartime near-monopoly profits, with $1.3 billion of net cash and owned aircraft weighed against…
 MGRC · long
McGrath RentCorp's conservatively financed hard assets, pricing growth and a struggling competitor, WSC, underpin the long thesis.
X-energy targets $1.8 billion in annual revenue and more than 42% gross margins by 2032 through reactor IP, project services and…
 Simple Investment Ideas 2 clicks
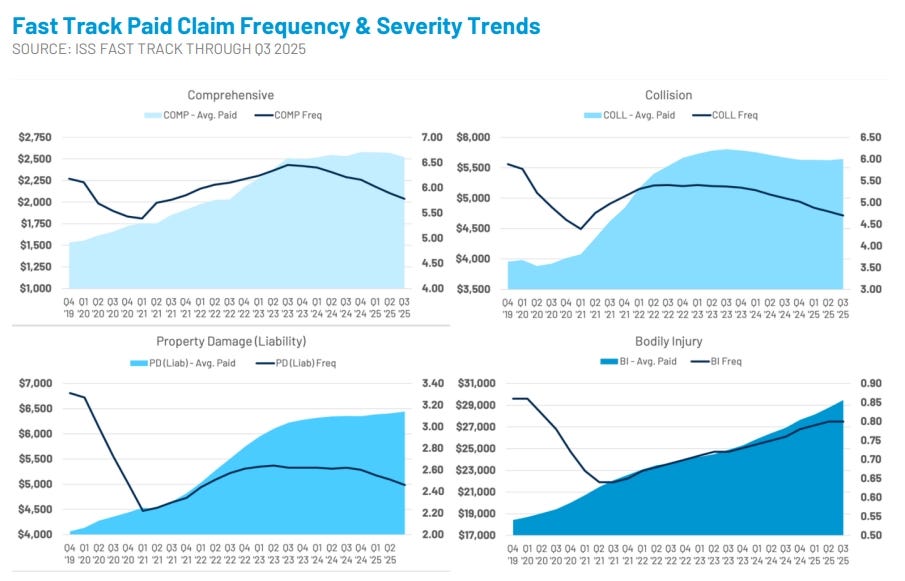
CCC, the dominant auto physical-damage claims estimator, connects 27 of the top 30 insurers with 31,000 repair shops as takeout rumors…
SA 2026-08-20 Seabridge Gold's KSM gold-copper project could re-rate on a joint venture, 2027 feasibility study and infrastructure progress, with gold…
 Redfern Research
ZhongAn Online trades at 0.57 times book after five profitable underwriting years, with a 95.8% combined ratio and ZA Bank’s first…

DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
Shift4 Payments trades at 6.9x EBITDA after a 50% five-year share decline, while leverage from acquisitions and slowing EPS growth weigh on…
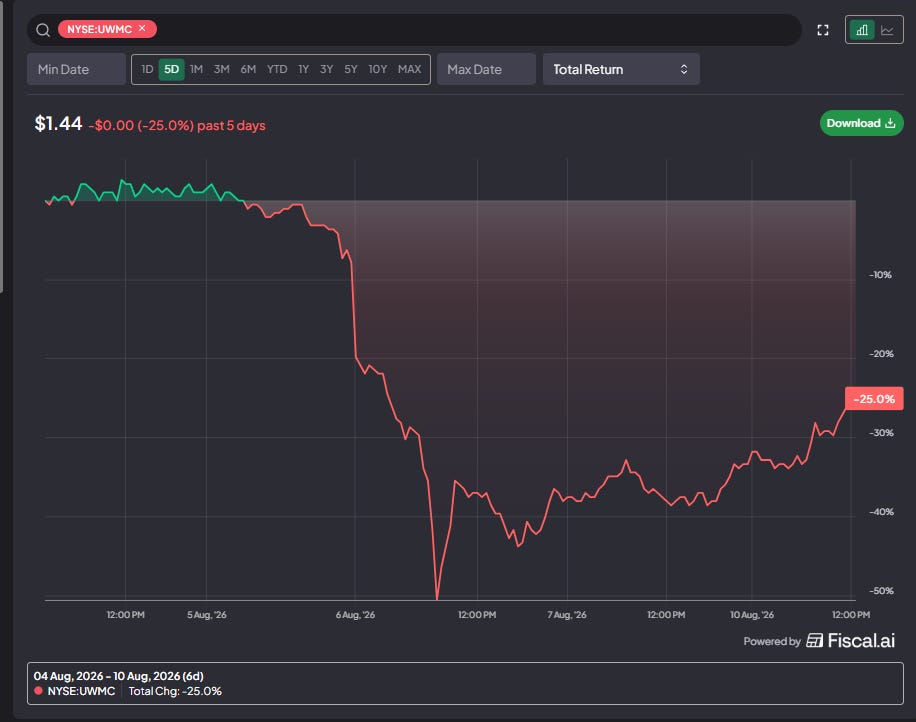
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.
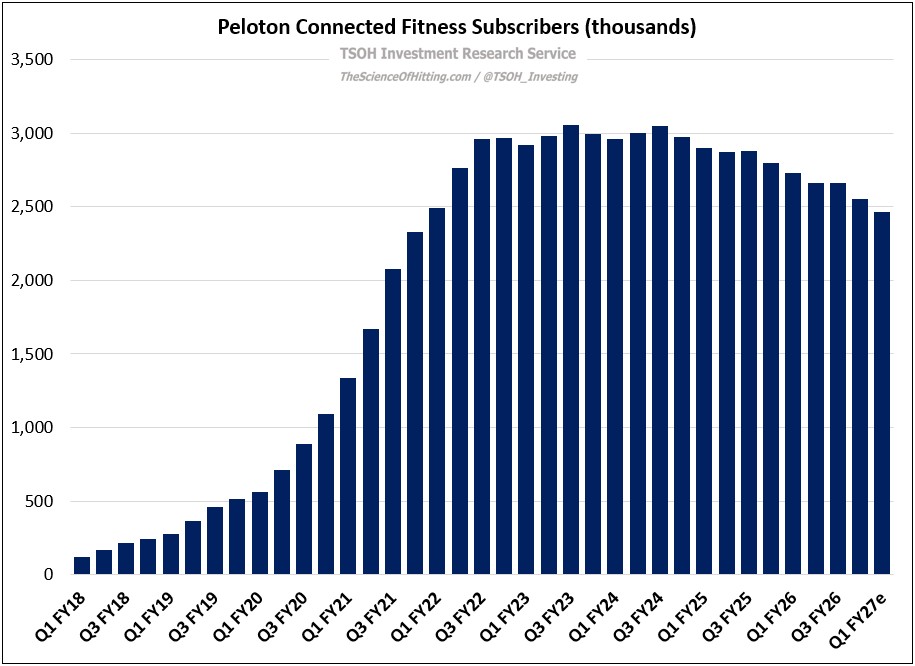
Peloton’s improved balance sheet has not stopped weak subscription trends or sharp volatility, prompting purchases near $3.70, a later…
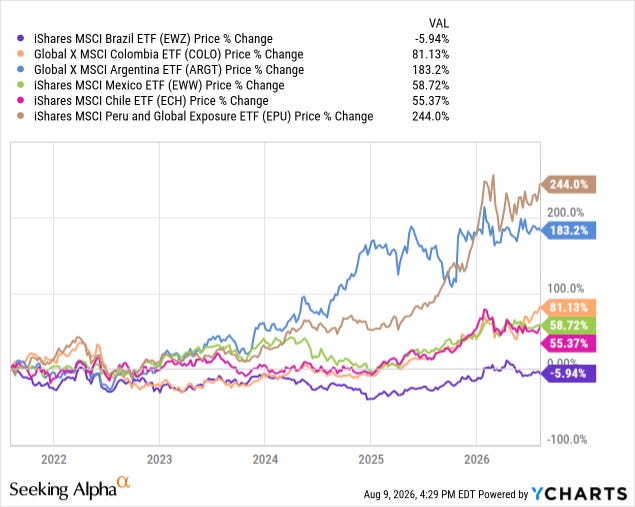
Colombia’s Abelardo de la Espriella signals tax cuts and an Ecopetrol revival, while Inter & Co.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.