NCLH or her grandma Saga?
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
Norwegian Cruise Line’s $15 billion debt and 2026-27 capex delay deleveraging, despite fuel-efficient new ships and stronger projected 2028 profit.
$PLUS Earnings on 8/5, expectations & stock disconnected from reality. Suppliers ($CSCO – 50% of product sales), competitors & customers all reporting sharp sales declines. Non-event PR today re a service they’ve been offering for 3 yrs is pumping stock; suggests mgmt is grasping
Meanwhile disintermediation by OEMs going direct is accelerating. See recent commentary from partners $CSCO, $PANW $DELL, etc. $PLUS has zero discernable benefit from $NVDA and AI.
Answer: aggressive revenue booking, financing sales, selling products at/ below cost to boost revenue and hoping to “then try to build it back up over time” per CEO. Contrast $PLUS performance w competitor and industry leader $CDW.
$PLUS Numbers don’t add up. 50% sales $CSCO product (sales -13% MRQ, guided -11%). MRQ $PLUS sales +13% (reported yesterday). Earnings call question: “OEM Cisco have talked about bottlenecks, weak orders. You’ve been unscathed…how are you outperforming the market significantly?”
$EXLS Highly innovative founder-CEO rapidly taking share w AI-based services. High-teens topline growth w expanding margins, higher value-add mix to attractive end-markets. 17x P/E yet to reflect business transformation. 100% FCF to buybacks. Winning customers from $ACN $DXC $WIT
$OII Niche leader in subsea robotics at 12x P/E. Offshore rig count accelerating (70% share), A&D growing DD, new autonomous tech a major growth driver in other end markets (lifts, etc). Investor day next week will showcase products and new LT targets. >50% NTM upside, IMO.
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$YOU Delta just significantly expanded its Digital ID program. This service is free, more efficient than Clear and now available in Clear's core markets. Other majors will have to follow in order to compete on service. Seems like this could kill $YOU in pretty short order. https://t.co/tgfebZZCWK
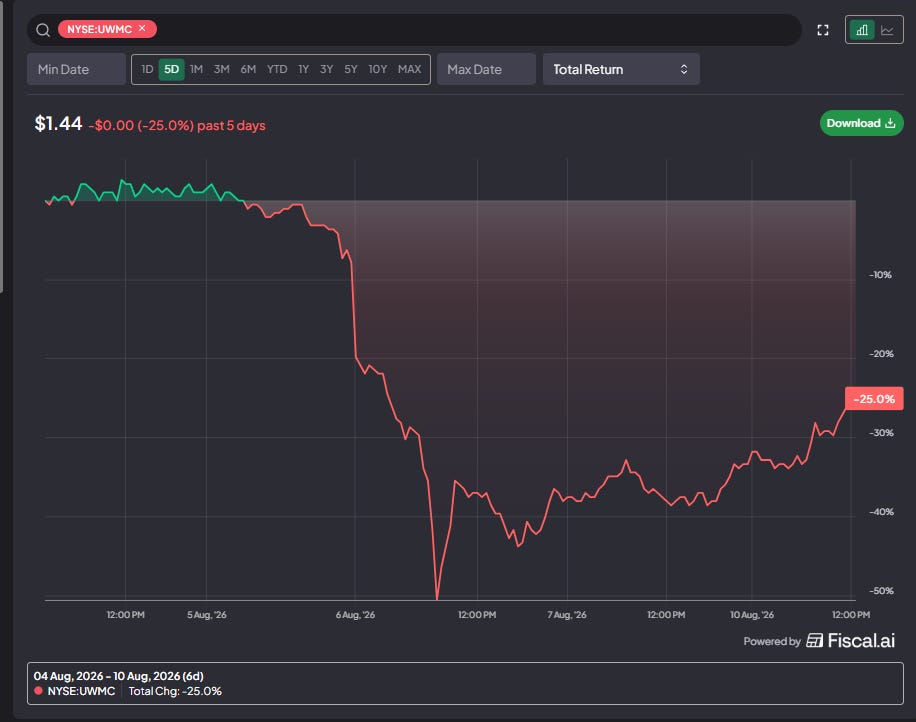
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Hims & Hers investor Paul Cerro is long again on lab and patient data driving retention and LTV, despite management concerns, GLP-1…

Perimeter Solutions’ 2Q26 revenue rose 31%, while operating income fell 11% as USDA pricing and DLA delivery timing hurt Fire Safety; it…

Floor & Decor’s same-store sales improved to minus 2%, while $45 million of tariff refunds lifted second-quarter gross profit and operating…
Builders FirstSource reported Q2 2026 sales down 9% to $3.9 billion as weak housing demand and aggressive competitor pricing cut EBITDA…

Floor & Decor held 2026 guidance after a 2Q beat, with comps improving through June; tariff refunds lifted margins and may fund pricing…

CBIZ activist Ryan Bunn urges ending buybacks, issuing equity and resuming bolt-on acquisitions to delever after the $2.3 billion Marcum…

Sprouts Farmers Market’s 483-store fresh-food format combines dedicated distribution, curated assortments and long-built site selection,…

VEON’s 84% Kyivstar stake and JazzCash underpin a sum-of-the-parts case for 4x upside, despite its sanctioned shareholder, capital…

MSA Safety’s Pershing Square Challenge finalists pitch gas-detection subscriptions, mandated SCBA replacement cycles and a 2023 liability…
 TDC · short
Teradata is a short as its on-premises analytics business declines while enterprises shift workloads to cloud-native platforms.
Wingstop generates most of its $697 million revenue from franchise royalties across a 3,153-restaurant, 98%-franchised system while…

A software powerhouse posts a record quarter while trading at a 52-week low, raising a valuation disconnect between its business model and…
Vidrala has grown from a Spanish glass-container maker into a multi-country packaging platform with expanding Latin American exposure.
Domino’s 99%-franchised model converts global retail sales into royalties and supply-chain revenue, but $4.8 billion of debt and mature…
Pool Corporation controls roughly 40% of US pool-product distribution, with maintenance representing 64% of sales as new-pool construction…
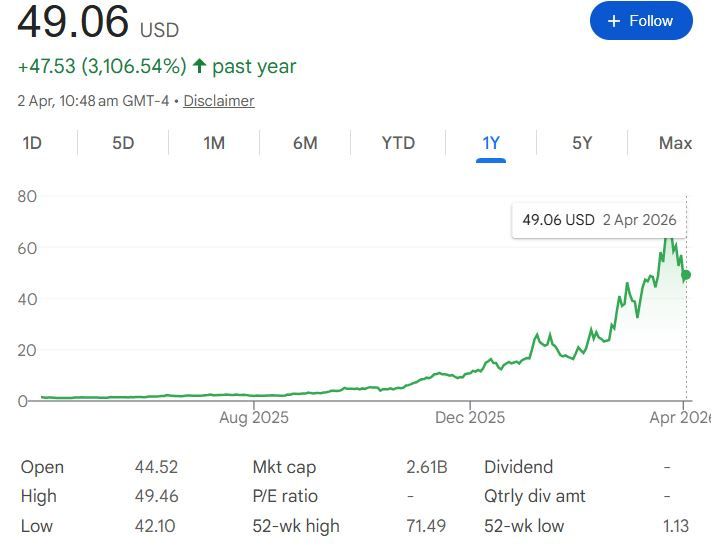
AXT’s 85.5%-owned Tongmei depends on offshore pricing, export approvals and transfer-pricing economics despite AI-optics demand.

LandBridge outlined $300 million in pore-space free cash flow within five years; its Permian data-center project remains proof of concept.
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…

Vaca Muerta’s $36–45-per-barrel breakevens, Milei reforms and $17 billion infrastructure buildout underpin the bullish case for Vista…
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.