$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
@lasse108 @ReturnsJourney $intr
$CENX is a non-AI bottleneck https://t.co/L0PvNNH4HK
Shelly Group $SLYG H1 '26 results: ▫️Revenues +26.5% ▫️EBIT +45.6% ▫️EBIT margin of 26% (vs. 22.6%) ▫️Net result +51.4% ▫️OCF +260.6% ▫️FCF +354.3% ▫️Cash +133.1% ▫️DSO of 147 days (-21) ✅ Guidance confirmed https://t.co/do39CfwTEk
@shortbus_ace @akeemcap @QuietProsperity $CAAP is 6x EV/EBITDA and no Mexico. But half of EBITDA is from Argentina, so that's its own can of worms (albeit the Argy fees are charged at a fixed USD rate not Peso)
UBS initiates $CENX conservatively: $60 at 4x EV/EBITDA > Oklahoma & shareholder return catalysts > best leverage to US MWP > Oklahoma and datacenter not priced in > 4x below normalized mid cycle https://t.co/MiKQD9rlFV
@House_Stark12 Think again. Arguably the only thing $OPEN is good at is issuing new stock. https://t.co/oUX7I8I2kY
Embarrassing press release. $OPEN Revenues fell 44% year-over-year. And they are still budgeting $110 million for SBC in Q3 alone. Absolutely shameful behavior. https://t.co/7vZtlVVy2j

VEON’s 84% Kyivstar stake and JazzCash underpin a sum-of-the-parts case for 4x upside, despite its sanctioned shareholder, capital…
Wingstop generates most of its $697 million revenue from franchise royalties across a 3,153-restaurant, 98%-franchised system while…

A software powerhouse posts a record quarter while trading at a 52-week low, raising a valuation disconnect between its business model and…
Vidrala has grown from a Spanish glass-container maker into a multi-country packaging platform with expanding Latin American exposure.
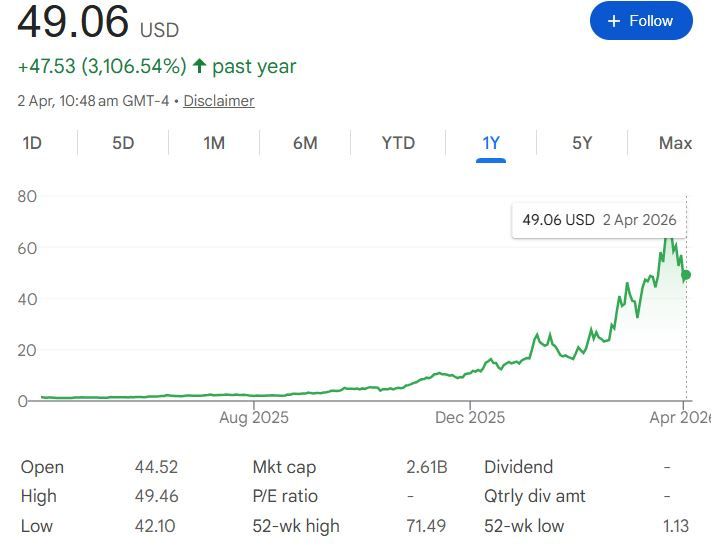
AXT’s 85.5%-owned Tongmei depends on offshore pricing, export approvals and transfer-pricing economics despite AI-optics demand.
Shift4 built its payments business by acquiring gateway nodes and migrating merchants to its processing platform; revenue has compounded…

A former value-investor darling, down 50%, pairs a monopoly with a recurring-revenue razor-and-blade business; debt paydown, margin…

Haw Par combines Tiger Balm’s stable cash flows with property, leisure and healthcare operations plus stakes in UOB and UOL.

National Beverage’s rare share repurchase is framed as a buy signal, with 50% upside projected.

Argentine banks, tariff-exposed stocks and Customer’s Bancorp anchor an earnings-season watchlist after Milei’s election victory,…
 SLGN · long
Silgan’s long thesis rests on roughly 10% historical EPS growth and a potential rerating as its end-market exposure evolves.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.