$DNOW: the boring distributor that could double on 2029 numbers | Firebird Management
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
DNOW’s MRC Global merger targets $75 million of synergies, with a 2029 bull case of $30 to $32 per share driven by cash flow and rerating.
$CENX is a non-AI bottleneck https://t.co/L0PvNNH4HK
UBS initiates $CENX conservatively: $60 at 4x EV/EBITDA > Oklahoma & shareholder return catalysts > best leverage to US MWP > Oklahoma and datacenter not priced in > 4x below normalized mid cycle https://t.co/MiKQD9rlFV
Timna on $CENX “early innings of broader FCF rebound.” “Hugely undervalued” at 1.5x their ‘27 EBITDA. $83 PT at 4x! Direction of numbers up, delta to street up, and lots of multiple rerate room imho https://t.co/8wkrmh5S83
“for the first time in over a decade, all Century assets should be operating at full capacity. I'm very proud to report today that our team has delivered” As expected, Q3 & Q4 will be when the real earnings power of $CENX is demonstrated. Still under-earning. Still bottleneck. https://t.co/Buw6H87Sed https://t.co/KyfyjMcJhq
Bought $CTRI ~$22-$22.50 into this post-earnings sell off. Margins were disappointing, but $CTRI is growing nicely given the tailwinds in energy and utility services. Margins should follow in time from greater scale & pricing power, and the balance sheet is vastly improved.
Any fundamental views on $RH here? I’ve been recently trying on the short as a trade into the $180 level with some success, feels like it has squeezed higher due to de-grossing/de-leveraging. Other building names are very weak with 10-year testing 5%.
Sold my $BILL on this 50%+ run off the lows, and continue to actively trade around core $HUBS and $WDAY positions by regularly writing calls or shorting puts (and sometimes boxing my longs). The volatility has been insane. Sold $ESTC for now. Also, I’m now short a small amount of $ADBE, $NOW, $TEAM, $CXM and $YEXT into July’s de-grossing/de-leveraging squeeze.
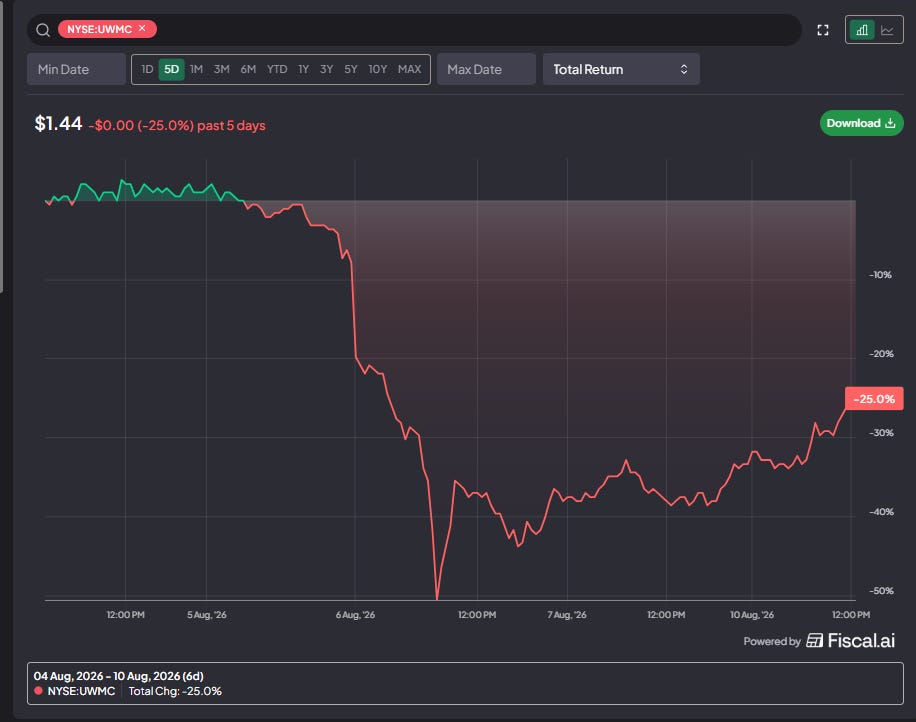
UWMC booked a roughly $600 million Q2 hedging loss tied to TWO months after the deal collapsed, contributing to an expensive capital raise.

Navient trades near 40% of tangible book as Gator Financial Partners argues private student-loan growth and restructuring can reverse its…
Diversified Energy cut $233 million of debt in 1H26, repurchased $93 million of stock and sold $273 million of land and assets while…

Perimeter Solutions’ 2Q26 revenue rose 31%, while operating income fell 11% as USDA pricing and DLA delivery timing hurt Fire Safety; it…

Vistance Networks plans a large post-Ruckus-sale dividend, leaving Aurora Networks valued below 4x guided EBITDA after $1.88 billion of…
OTC Markets gives smaller, distressed, and lightly disclosed companies a trading venue outside NYSE and Nasdaq, with lower listing barriers…

A debt-free American manufacturer now trades at roughly 7x annualized Q2 EBITDA, with $7.35 per share in net cash and a tender floor 18.5%…
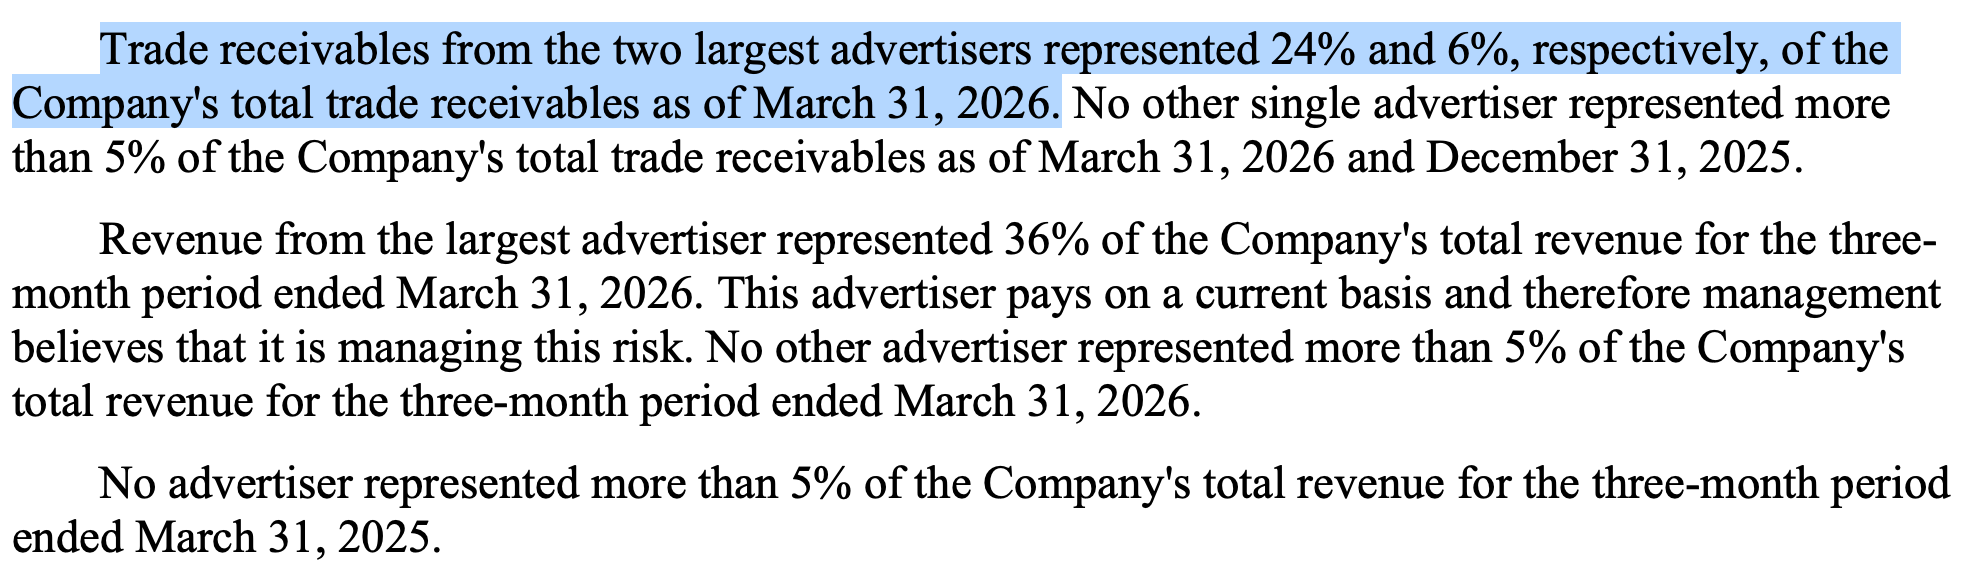
Entravision’s Q1 filings contain a new footnote disclosure pointing to a potential second large advertiser beyond its Hong Kong customer,…

United Parks trades at 8x EBITDA with an 8%+ unlevered cash yield, aggressive buybacks and roughly 80% effective short interest, while…

Diversified Energy (DEC) has paid $21.84 per share in dividends since June 2017 and trades at $13.35 amid a bullish U.S.
 HHH · long
Howard Hughes Holdings is pitched as a long in the $60s, with a near-term $90 target and a projected 20%+ IRR.
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.