Updates
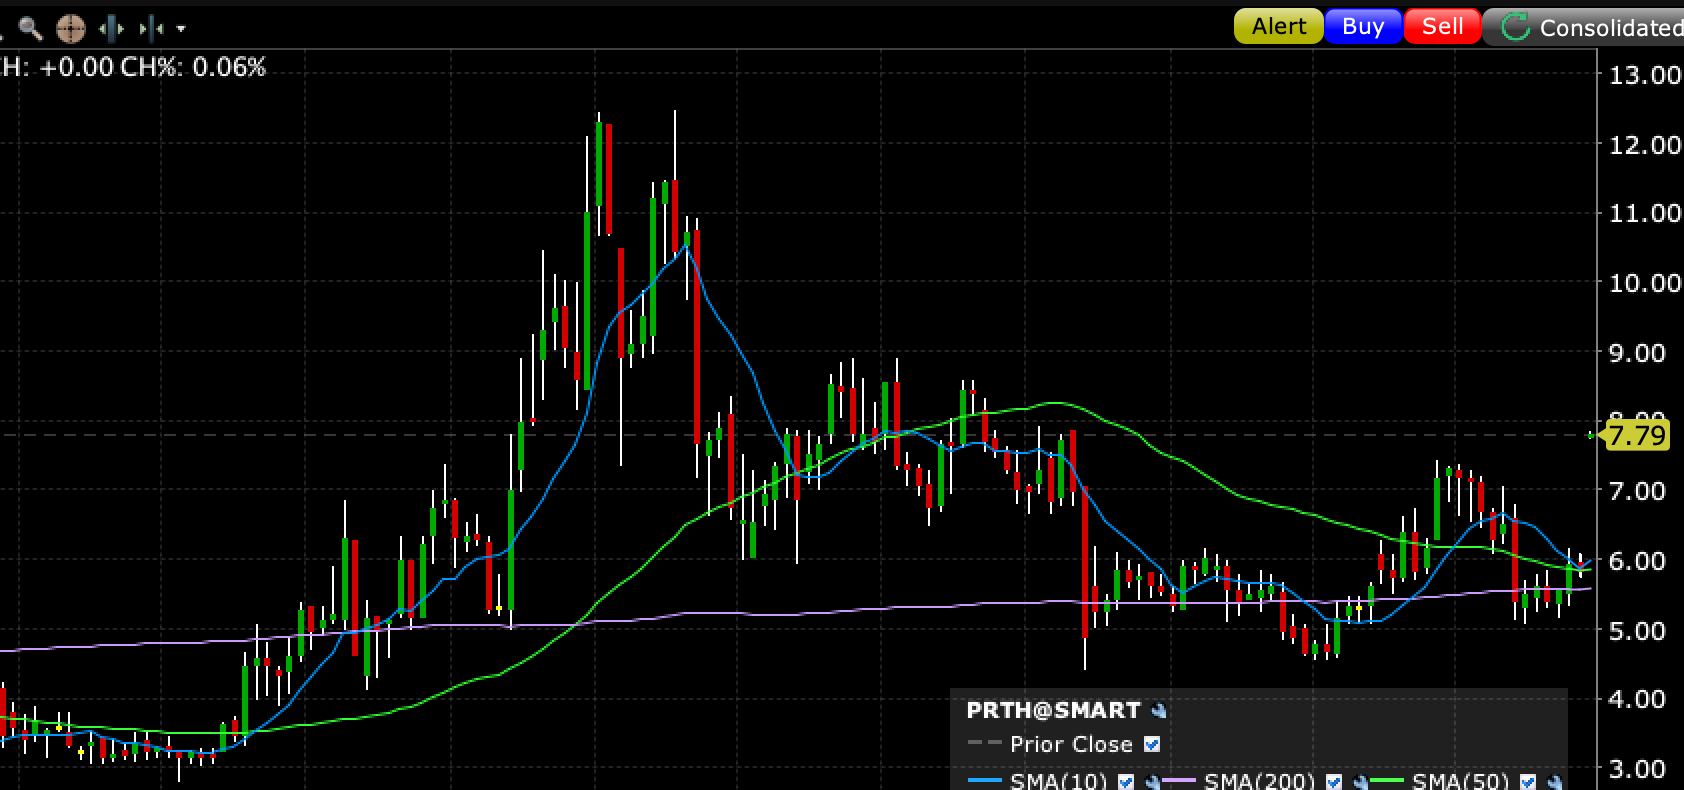
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
FGPR remains on track, PRTH's management buyout is set at $8.05, and microcap RAVE is described as cheap.
Clearly not the main headline from $CCB's earnings yesterday, but still likely of interest to some readers https://t.co/07bcFN06pR https://t.co/1hdpGgNIPH
I just published my Portfolio Update for July '26. It includes: ▫️My current Portfolio & position sizes ▫️Earnings Update about $EVO, $BRM.V, $ALENO.PA, -undisclosed- ▫️Recent news & information about $LEAT, $CIRC.MI, $SLYG, $4058, $EVO Link for the blog in Bio 😊 https://t.co/7eVa84MGbr
$cour did not realize this. not a great look, especially after its new 100m investment :/ https://t.co/wj1wPvgFof
$ALTO $GPRE E15 👀👀 "Senate Republicans will include language to permanently allow year-round sales of E15 fuel in the farm bill they plan to mark up next Thursday, according to two people familiar with the plans."
Ouster began coverage at Accumulate as lidar revenue rose 56% in Q2, while annual cash burn near $80 million has driven an 86% share-count…
AAON's BASX data-center cooling business targets $1 million to $1.5 million per megawatt, with new capacity and backlog conversion expected…
Vista Energy's Q2 2026 production rose 32% and revenue 89% as Vaca Muerta acquisitions expand its Argentine export platform and cash…
 Alan Galecki 5 clicks
Firefly Aerospace ended Q2 2026 with $1.5 billion backlog and a 2.49x book-to-bill ratio, adding lunar, defense and launch contracts for…
Birkenstock targets 13–15% annual revenue growth through FY2028, driven by APAC expansion and closed-toe footwear, while trading at 13.44…
 Roman Vitasek 4 clicks
ZIM’s proposed deal carries a claimed 23% spread and 110% IRR by Q4 2026, with Q3 and Q4 dividends potentially raising returns if closing…
Turning Point Brands reaffirmed 2026 guidance after a CEO change, while ALP and FRE expansion has compressed margins through marketing and…
 Caffital Research 1 click
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…

Shift4 trades at 6.5x EBITDA despite 11% reported organic growth, with Shift4 Dine equipment leases cited as evidence of net-new merchant…
Texas Instruments, ON Semiconductor and Vishay are rated Accumulate on rising robotics demand for analog, power and discrete chips after a…
 GLIBA · long
Liberty Capital Corp, GLIBA, is pitched long following its July 2025 spinoff from Liberty Broadband.
Kronos Worldwide’s 27% inventory reduction added $120 million in cash inflows as chloride-based TiO₂ demand rises amid a sulfur shortage.
 Given Mahlangu
Firefly Aerospace grew backlog to $1.5 billion, won two 2028 lunar missions and acquired Space-ng for autonomous navigation across its Blue…
Cellebrite converts more than 110% of EBITDA into free cash flow and trades at 12.5 times free cash flow, with management targeting 15% or…
Innodata's new Meta contract for long-horizon agent personalization ties the data company to Meta's Muse AI assistant, despite Meta's Scale…
Undercovered Dozen spotlights 12 lesser-covered stocks, including Rithm Capital, Sterling Infrastructure and Corning.
 The Undercovered Dozen
Shift4 trades at 6.5 times EBITDA despite 11% organic growth, with Shift4 Dine equipment leases reaching a $400 million run rate as…
Copart’s $1.9 billion ACV Auctions acquisition targets renewed growth, with EPS accretion expected by fiscal 2028 as insurance…
 Robert J. Lake 2 clicks
Corteva will spin off its Pioneer seed business, Vylor, on October 1, leaving crop protection RemainCo that could trade at 6.5-8.5x 2026…
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.