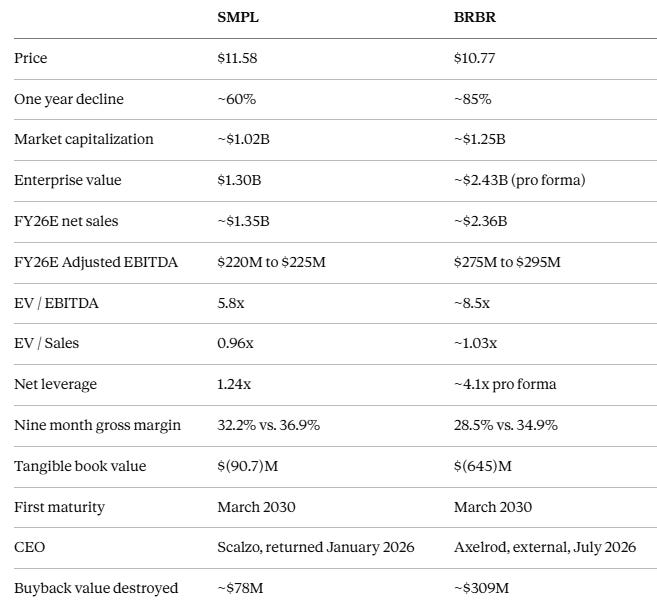
A Busted Businesses or a Cyclical Bottom?
Two U.S. protein-snacking companies lost $6 billion in market value as impairments, inventory growth and margin pressure test whether the category has reached a cyclical bottom.
Two U.S. protein-snacking companies lost $6 billion in market value as impairments, inventory growth and margin pressure test whether the category has reached a cyclical bottom.
$RAVE “The ‘I ate at Pizza Inn’ restaurants experienced a 30.6% year over year sales lift and a 34.7% traffic lift for the final eight weeks of the fourth quarter… have completed eleven reimages and the reimage results continue to be very positive. We opened new…” 1/2
$DAKT Just won the massive jumbotron project for the new Titans stadium. Estimated to be $180M. Will be the largest set of displays in the NFL. Bills, Browns stadiums to be announced soon. Wouldn’t be surprised if Mitsubishi acquires them given interest in the category.
With contract disputes and litigation set to surge, I believe Burford is well positioned to benefit. Struggling firms will increasingly look to shore up capital—Many cannot afford to wait 2+ years to see the case through. $BUR
Burford’s value prop is high to these firms, and the significant supply spike puts them in a fantastic position to capitalize on the demand for cash. Additionally settlement with Argentine government seems highly likely at this point. Long $BUR
$NX 5% of COGS/ direct input costs sourced from China. Tariffs + zero pricing power, high fixed cost structure + only 30% GMs = 25-30% hit to EBIT. Add 4x leverage, declining volumes, ambitious mgmt guidance while integrating a large acquisition is a setup for a trainwreck.
$DAKT CEO departing, new high-quality CFO (temp) w very attractive secular tailwinds in digital display demand + activist involvement = increased likelihood of takeout. Optimal business for PE. Multiple logical strategics. +75% upside.
Tectonic Therapeutic's TX45 CpcPH-HFpEF program gains support from Merck's CADENCE data; Phase 1b hemodynamics and cash through Q1 2029 set…
 Equity Eagle 2 clicks
EVC reported a solid second quarter and outlook.
Limbach's EBITDA fell 30% as organic revenue declined, but 1 Main Capital calls the weakness temporary and views CYMCOR as its first…
GoPro rushed out its Starman Optical merger after Markiplier-driven buying sent GPRO up roughly 90% premarket, offering shareholders $1.14…
Shattuck Labs pivots to DR3-targeted IBD therapy SL-325, funded through a Phase 2b readout as it competes with anti-TL1A drugs.
Equity Eagle 
Emerge Commerce's $44 million COVID-era acquisitions produced losses and impairments, while modestly improved Q2 liquidity leaves its…
NTG Clarity’s $18.6M of Q2 service revenue sat in contract assets, while $4.6M cash burn cut cash to $2.85M and raises liquidity concerns.
 INMB 2026-08-28
INmune Bio's Ebstrocel targets recessive dystrophic epidermolysis bullosa with UK, EU and US filings planned by early 2027, while XPro adds…
 Tejo Strategy Investing

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
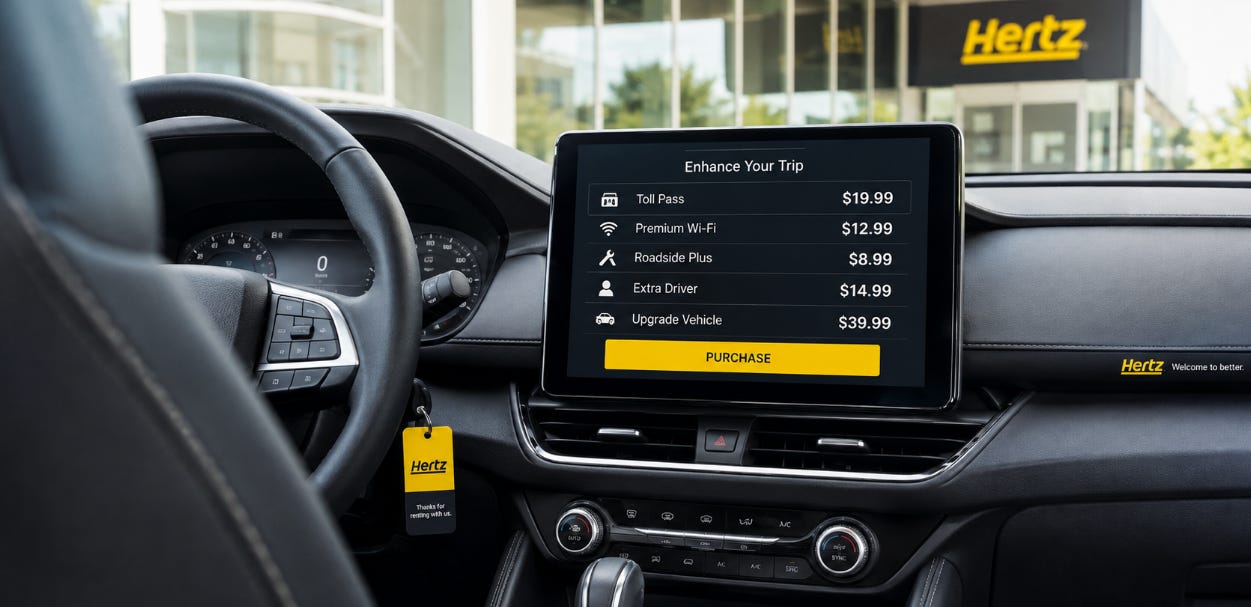
Verra Mobility renewed Hertz tolling management for five years. AutoKinex lets rental customers buy tolling, fuel and protection products…
 TOYO · short
TOYO CO LTD is the target of a short thesis.
Hydreight Technologies' Q2 revenue rose 12% sequentially to $28 million, while gross margin fell to 19.4% and cash burn stayed elevated,…
 Fernanda Galvez Jalil 1 click
Domo’s $400 million sale to Progress would leave a cash-rich public shell with $900 million of NOLs; January 2028 $5 calls cost 22 cents.
FUFU 2026-08-27 BitFuFu’s $93.4 million unexplained long-term payable equals 57% of liabilities, overshadowing sharply higher self-mining and hosting…
 Dorine Cherop
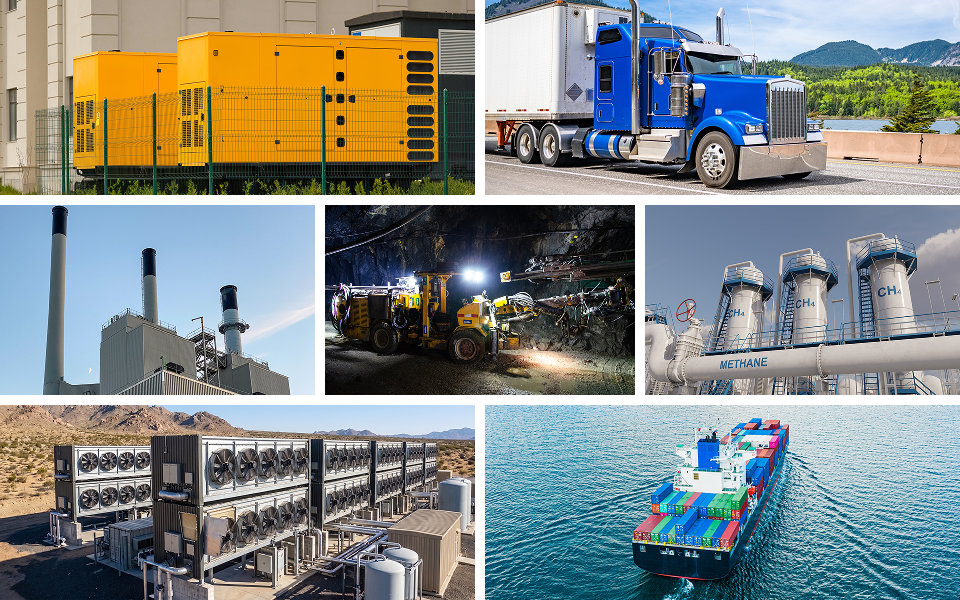
CDTi Advanced Materials has $804,000 of cash, roughly 12 months of runway, and unproven maritime methane technology despite ExxonMobil and…
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and…
US-Canada tariffs impose 50% duties on $20 billion of Canadian goods, lifting US steel makers while pressuring Canadian exporters and…
Star Equity’s $5 per-share Harte-Hanks acquisition offers $2.50 cash plus 0.25 STRRP per share after proration, against a $2 break price.
RCEL 2026-08-24 AVITA Medical’s more predictable reimbursement, RECELL GO rollout and PermeaDerm economics support adoption, with cash flow breakeven…
 Myriam Alvarez 4 clicks
Verra Mobility's new seven-year Avis agreement replaces a customer worth over 10% of revenue on materially worse economics, exposing…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai Equity Eagle
 Eudaemon Research Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Bullionaire
 The Curious Analyst
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.