Thursday, September 24

Thursday, September 24, 2026

Everything we published on this day.

99 stories — the front page that day →

@aleabitoreddit

Serenity on X

If you're curious about the random $SPY / $QQQ candle: Just now, “US and Iran discuss phased deal to reopen Hormuz and end US blockade" - Reuters - "A deal before the midterms could benefit Trump, as reopening Hormuz could ease tensions in the Gulf, contain ​oil prices and help bring down politically sensitive US gasoline prices." - "Trump has said he thinks the US and Iran could reach a deal after midterm elections to Congress on November.” Would make sense for Trump to want markets as strong as possible during Midterms elections…
@aleabitoreddit

Serenity on X

$AAOI has finished a $500m ATM In April.. $600m ATM in June. Then filed another $600m in August. It's out of my control if management wants to abuse this trash repeated ATM structure. Instead following $AXTI like LTA prepayments and using that to fund buildout. Or taking private placements like $NVDA + Nebius for $2B and using that to fund buildout. Or convertible notes at 40% premiums. It's really hard for the stock to break out of $100 or $150 or $200 if there's $600M of selling pressure at those levels (and maybe expectations of future ATMs). I had the same criticism with $IREN with their $6B ATM, which is why it's been rangebound for half a year. And I'll say the same thing with my own thesis names too. I see $AAOI operationally very bullish for 2027, with $471m/month transceiver revenue. 400k ELSFP units/month entering 2028. The revenue ramp is absurd and can compress to single digit forward P/E. But I find it hard to get excited over funding infinite ATMs during the buildout, when you're sacrificing opportunity cost with names currently profitable like $SNDK or Samsung. I think a lot of retail investors conflate stock performance with how a company is doing operationally. $AAOI is capitalizing on a bottleneck with high demand visibility, but stock has been going nowhere near-term with repeated ATMs. I do expect AOI to strongly outperform (especially in 2027) if they stop issuing these stupid ATMs.
@aleabitoreddit

Serenity on X

I would have a much more favorable view on $IREN after they finish their $6B ATM in terms of stock performance (I think they're like 41.5% through). I think Mirantis acqusition would materially shift a lot of perception of how they rank relative to $CRWV, $NBIS, Lambda, Tensorwave, and others in terms of cluster performance once they finish integration. I've always started software side of things is actually a moat (backing up what Coreweave CEO was saying), which was what $IREN lacked before. But M&A to get that gap fixed is probably the most bullish part of what they've done.
@aleabitoreddit

Serenity on X

Wow $NBIS relative outperformance is wild. Back in 2025 I wrote my Neocloud thesis on $IREN to $CRWV. But I made the decision months later to consolidate it all into Nebius... Despite the the hate from FinX back then. Very interesting to see Nebius up 6% even during sector drop… After Oracle was reportedly seeking payment protection if Project Jupiter misses its 2028 opening. With Oracle: "seeking to protect itself from potential cost increases related to a large DC ​project in New Mexico by sending a force majeure notice" per Reuters. Lot of new people like to piggyback after it’s up a lot, but there was a lot less people bullish back in 2025. Especially during the period with a ton of institutional short sellers back in December. I still think markets might be underestimating sum of parts growth, even if its core business grows like crazy 2027+ onwards.
@kevin__mak

Kevin Mak on X

At the risk of "trying to hard to read the tea leaves", when I saw the jury question, my thought was: "They're trying to aggregate the voting blocs" i.e. the jury is split between three possibilities a) $0 no breach b) $1 breach c) $XXX dollars breach and they're trying to figure out if the first two "should be the same group" or not. The real answer is it's impossible to know, it is directionally bearish/informative, but it's also an easy ~$250k PnL trade if you have someone in the courtroom relaying the info to you in real-time and you short off of it.
@kevin__mak

Kevin Mak on X

$NKTR Lots of funky action in this name the past few days, some specific to the ongoing court case and some from bio as a whole. Let's unpack it. The jury note, paraphrased as "Is there a difference between breach + $1 and no breach + $0?", spooked the market and sent the stock down sharply. Two sides to this. First, the note is informative, but only a little. It tells us at least one juror sees the $0/$1 outcome as part of their possible resolution space. Where I think the market (or at least fintwit) got it wrong is treating the note as the voice of the entire jury. It could reflect the whole panel, or it could be a single juror's question. It doesn't even tell us direction: it could come from a juror looking for a way to find breach despite doubting the damages case. The price action implied the whole jury is now choosing between $0 and $1, which I think is a big overread. Second, this is NKTR: a retail/fintwit-heavy, relatively illiquid SMID-cap biotech that moves 5% on a random Tuesday with no news. A 10% move on this headline looks extreme, but near-term price action here mostly reflects value-agnostic traders playing local news and liquidity flow, not a considered repricing of long-term value. The bigger picture: the case is largely a distraction from the real value, which is Rezpeg. I'm not a biotech expert, but the sell side and most biotech specialists I respect see it as a likely viable commercial product that's underpriced here. If anything, the case matters mainly as an overhang. An uncertain $0-to-$1B+ claim is hard for any acquirer or partner to price, so resolution in almost any direction clears the path for corporate action. The distraction is creating the opportunity. Disclosure: Creek Drive and its affiliated funds holds a long position in NKTR. Views expressed are current opinions for information only, subject to change and are not investment advice or a recommendation to buy or sell any security. Investing involves the risk of loss and past performance is not indicative of future performance. See the disclosures link in my bio for more important information.
@calvinblissett 2 clicks

Calvin Blissett on X

Hey Drew I know you cover mainly big names which makes sense in terms of reach. I watch your videos even when I know I’m not going to buy the stock because the quality is that good. I think in terms of bigger names with potential value $SLM is very interesting and would be a good set up for you. $KNSL is another that also has a pretty good retail following. $FISV is the biggest size potential value I’ve found. Also a $FICO update with thoughts would be orgasmic
@calvinblissett

Calvin Blissett on X

To me that is not true and one of the common misconceptions on $BMBL, like someone insightfully mentioned word of mouth is a powerful thing. Especially in today’s day and age. Here is a real world scuttle butt example: I was talking to a girl about here boyfriend and how they met and how she meets guys. She said hinge, instagram tinder. She said hinge for dating, tinder for hook ups. If she mentions Bumble for dating that is a huge endorsement and whoever hears it is virtually certain to try Bumbls. If $BMBL is continuously successful at providing quality matches (Whitney’s goal) it will gain new users->leading to potentially more subscribers->leading to potentially more lost subscribers due to success->who will spread the word and create more inflowing subscribers than out flowing. Word of mouth may be the most powerful advertising force

IEH Corporation: Research Note

IEH booked $3.6 million in mobile-defibrillator connector orders, lifting its medical revenue outlook and diversifying beyond aerospace and…

@ActAccordingly 2 clicks

PAA Research on X

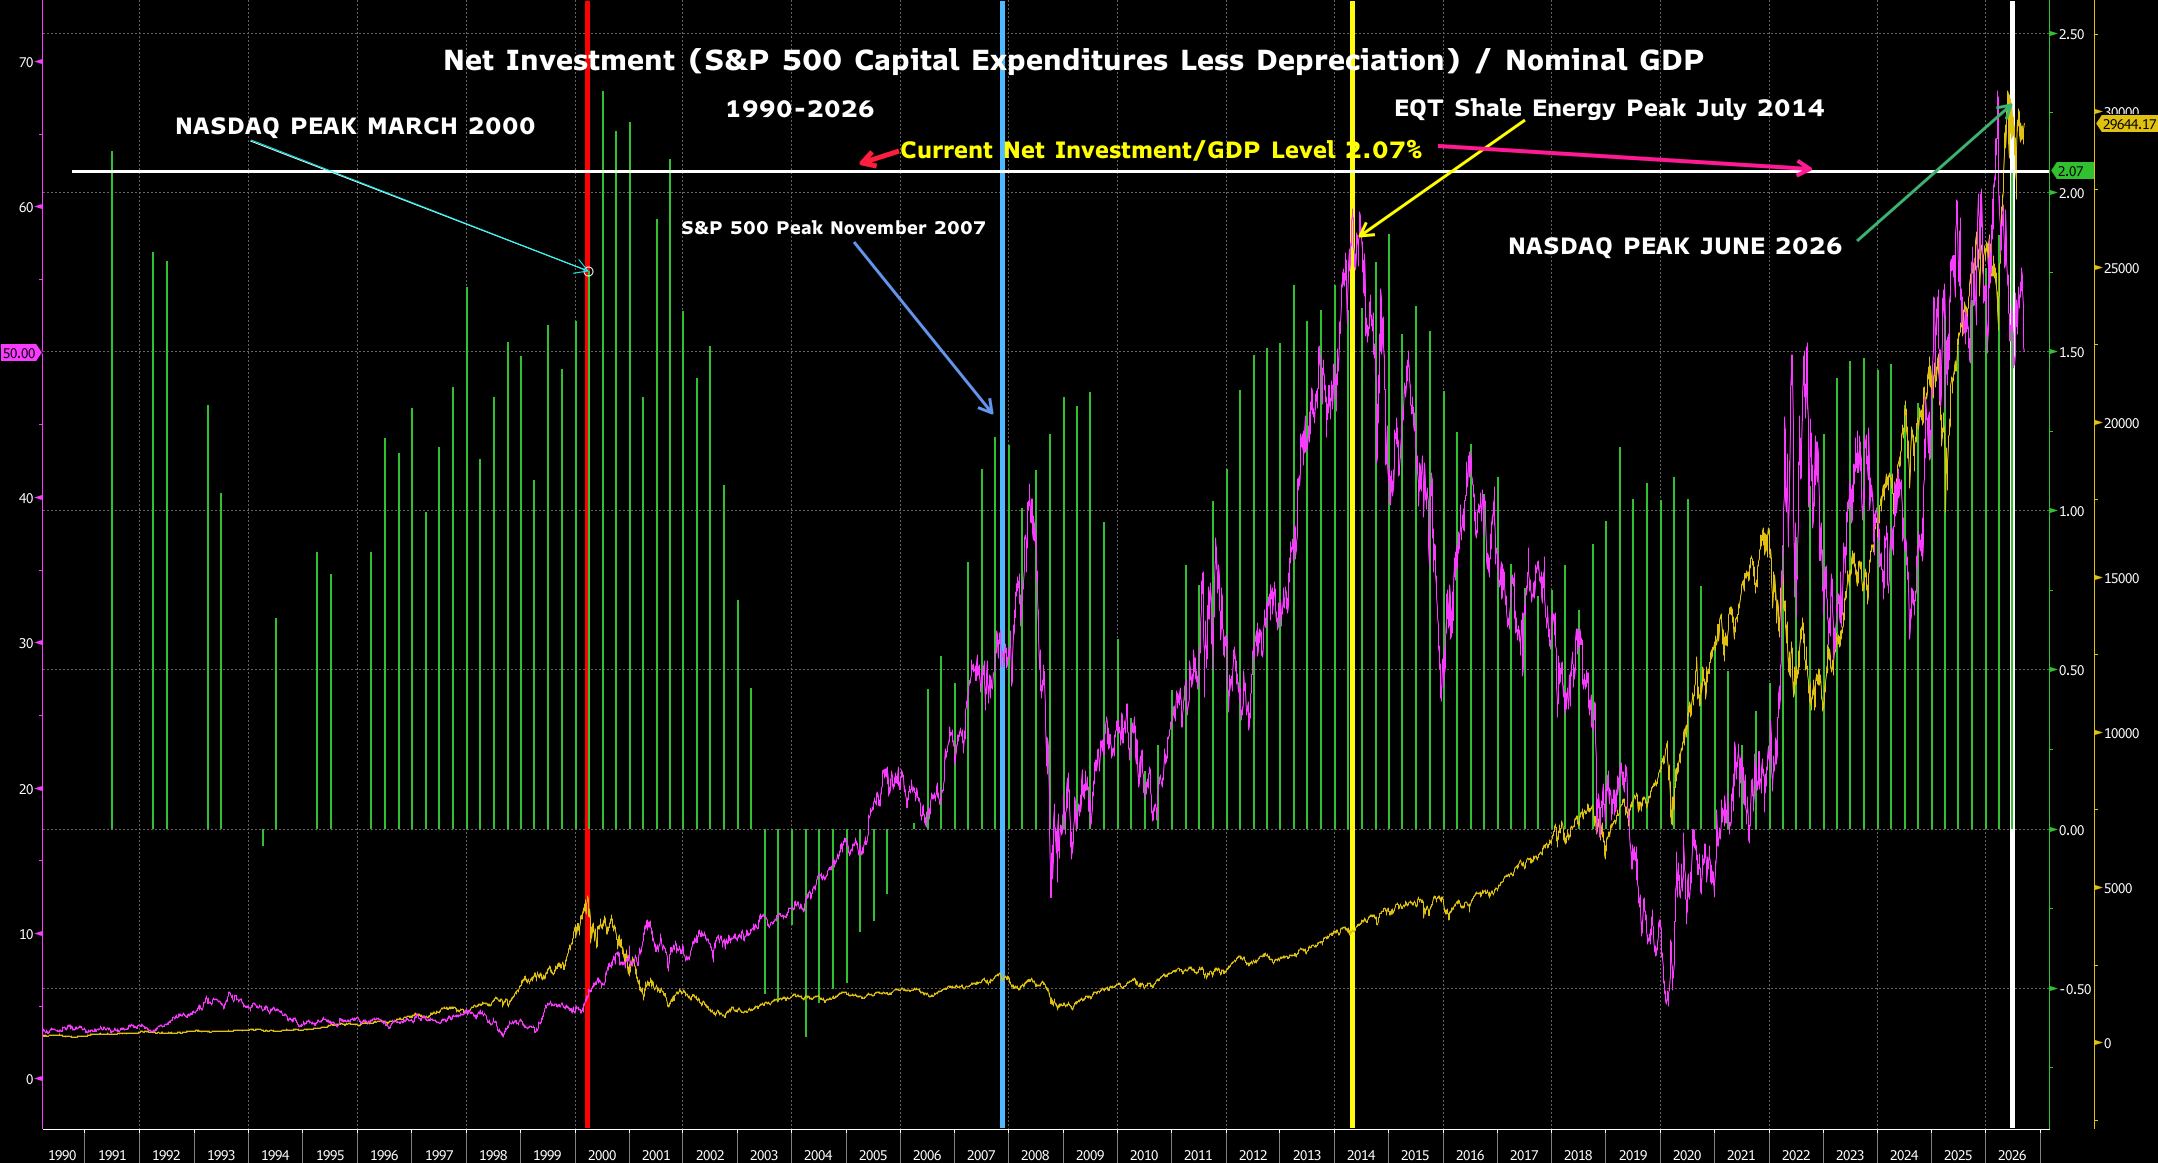
All trading below their 200-day moving averages right now: - Dow transports ($DJT) - Industrials $XLI - Retail $XRT - $GS Right at the 200-day MA - $KRE. $RUT seems destined to test the 200-day. Normal late September action, but it doesn't feel good. I guess we're setting the state for some golden crosses come late October/November or we're going lower. $MAGS carrying the day like 2024 when we dreamed of lower deficits and lower rates....
@leevalueroach

Lee Roach on X

Disclosing a large short position in $META. Thesis: Muse is offered free of charge with no meaningful cap on inference consumption. Meta is absorbing the full cost of compute, memory, and power on every query in pursuit of user growth. We believe this subsidy is unsustainable under adversarial usage. Position: We have deployed 10,000 endpoints running maximally compute-intensive workloads on a continuous basis. Deployment is scaling at 10,000 units per day. Unit economics: Our marginal cost per endpoint is approximately $300, incurred once. Meta's cost per endpoint is recurring and uncapped. We view this as a highly asymmetric trade. Channel checks: Retail sources confirm unusual laptop demand in the region. We are the source of that demand. Risks: Rate limiting, supply constraints at our primary vendor, and rising operating expenses on our side. Outlook: We expect material margin compression, a miss on next quarter's earnings, and elevated data center thermal risk. This is called activist investing.
@Fierce__beast 1 click

Fierce_beast on X

I am short $INMD. The stock will go lower i think if the business continues to deteriorate. Unfortunately, the guidance changes and results have caused me to essentially lose a lot of trust in anything the management says. I have been following this company for years. Sparing you the details, my view is not that I think fair value is significantly lower, but rather that there is just very small chances it recovers its core business. I think the most likely case is that it languishes and underperforms the market over time. Short interest collapsed to low single digits after the deal was announced and it remained low even after the deal ended last week.
@ActAccordingly 2 clicks

PAA Research on X

This is one of my favorite charts. It's amazing how small caps went from modestly overbought to NEARLY VIOLENTLY oversold. The picture below tells the story. In general buying when the percentage of Russell 2000 stocks trading above their 50-day moving average drops below 20 has been a massive driver of returns. Conversely selling when the percentage exceeds 70% has preserved capital. The headline here: We're oversold in small caps following the spike in interest rates and crude oil prices. We're not at a clear buy signal yet, but it's close. $IWM
@junkbondinvest 2 clicks

junkbondinvestor on X

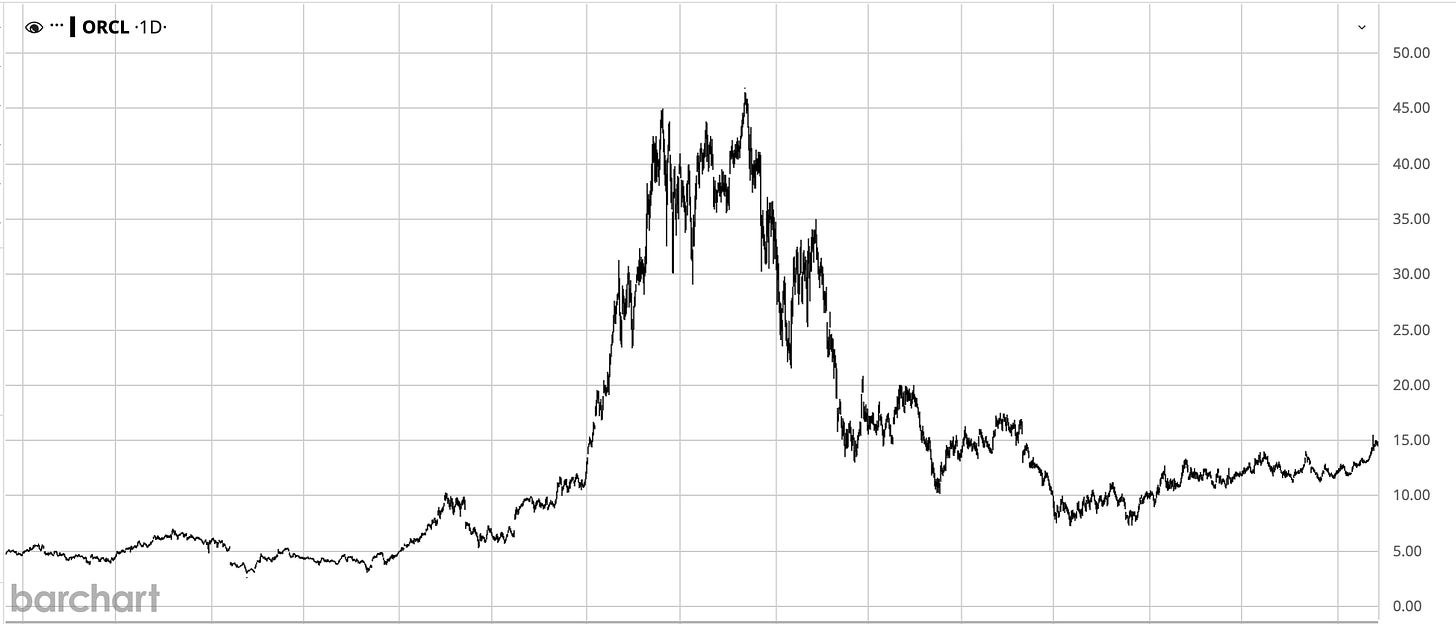
The typical argument for data center project debt is that the tenant is IG and therefore unlikely to default. That may be true...if the project is actually finished. $ORCL JUST sent a force majeure notice to Stargate campus, trying to defer payments when/if the buildout gets delayed. This is the $18bn construction loan that FT reported is offered at ~89-91. Remember, construction risk doesn't care if your tenant is IG. You gotta build the thing on time.