
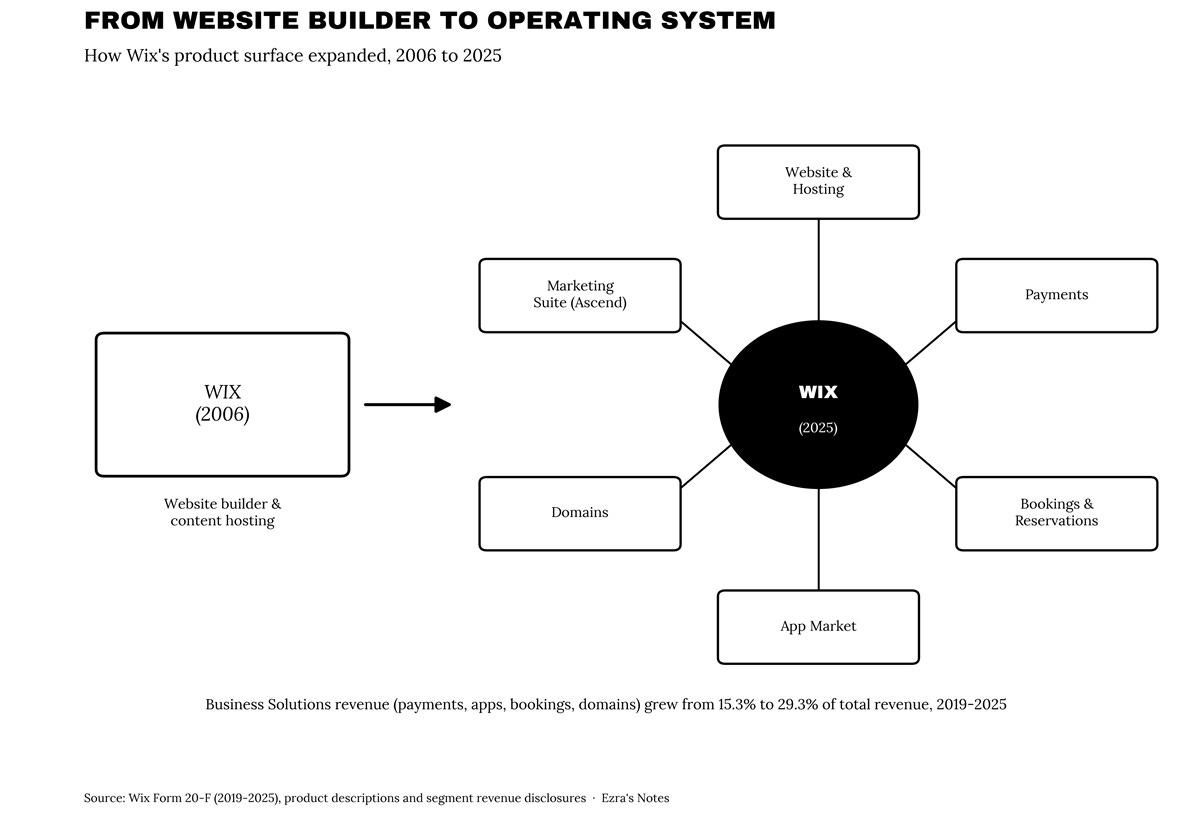
Why I Agree With Rob Vinall on Wix
Wix’s paying-subscriber conversion fell from 2.72% to 2.01% since 2019, while Business Solutions drove growth and activist-led cost cuts…
Thursday, October 1
Everything we published on this day.
100 stories — the front page that day →
Wix’s paying-subscriber conversion fell from 2.72% to 2.01% since 2019, while Business Solutions drove growth and activist-led cost cuts…

Based on Hunterbrook Media’s reporting, at the time of publication Hunterbrook Capital is short $LIFE and short bonds issued by Sammons Financial Group. Positions may change at any time. This article is not investment advice or any recommendation. See full disclosures on our website.
Ethos ($LIFE) claims to sell life insurance in minutes online. Behind the website, Hunterbrook found multilevel marketing agencies, pressure to spend recruits’ last $500, and agents with disciplinary records. Here’s how the business works.

@meidaoge Agility Robotics hasn’t gone public yet, I’m just waiting for listing announcement this quarter for $CCXI
"Potential FCC rules on optical transceivers more likely to come at 3.2T" - $LITE, $AAOI, $COHR, $SIVE. Morgan Stanley met with Washington officials: - Restrictions would likely start at 3.2T modules made in China (800g/1.6T would be left alone) - Potential restrictions would likely keep laser market tight (combining US DSPs + lasers could meet the 65% US value threshold per MS) - Chinese modules could qualify if 65% of bill of materials is US content. Chinese modules using US DSPs and lasers are already near that level - Analysts expect the positive impact on laser pricing... to be more important than any broad redistribution of transceiver market share. - Analysts don't expect this to bottleneck hyperscaler AI buildouts, they name InP substrate supply as the key variable to watch (hello $AXTI ) TLDR: Component suppliers in general are really positive. Like $SMTC probably winner here for TIAs/drivers (I don't think this was listed), maybe $MXL for DSPs too. $AAOI another large beneficiary. $SIVE is high-key alpha for laser beneficaries since they have "tremendous capacity" coming online, and that points to US foundries (they haven't formally disclosed location). Since previous slideshows show 2 US foundries 1 Taiwan foundry (Win Semi) in terms of their capacity partnerships. And it's process of elimination. From CIOE Channel checks it does look like they're starting to work with Chinese pluggable players, (so they'd avenues moving forward as US supply chain component beneficiaries). Of course $LITE / $COHR would be happy. TLDR: Western supply chains for Lasers / DSPs / TIAs / others are already bottlenecked but qualified capacity becomes even more important.
Indian bearing suppliers gain a US tariff advantage as SKF, Schaeffler and Timken build export capacity and source local rings, cages and…
Dynatrace completed its acquisition of San Francisco AI startup Arize as its CEO predicts humans will soon stop writing code.
FTAI Aviation is converting retired CFM56 jet engines into 25-megawatt data-center generators, supported by a $1.465 billion order likely…

I cannot reconcile the significant insider buying at $celh w/Bloom’s scanner data, clear shelf space gains, & social momentum. Plus freight headwind Alani LTOs (witches brew) are doing well/slight accel but core CELH doesn’t have accel potential until Q1 Too much risk I think
Mattel rose 19% on takeover speculation, but a potential $20-per-share bid, margin pressure and CEO transition leave its standalone…
 Seeking Profits
STAAR Surgical derives 56% of Q2 sales from China and trades near 3x EV/sales despite weak U.S.
 Stephen Ayers

On timber companies $RYN and $WY. If the long end keeps going up. 6-7% which I think is definitely possible. Then timber companies will get crushed. But my overall thesis remains and is happening in real time: energy-driven inflation, fiscal deterioration, failed treasury buybacks, the Fed losing the long end. Right now the market is repricing duration before it reprices scarcity. This gap can run for decades. Equities were destroyed in real terms through 1973 and 1974. But hard assets won the decade. I’m praying both of these timber companies keep going down. Land is my favorite asset to own. You can see it. You can touch it. You can hunt on it. You can fish on it. And you can grow productive timber on it. Huge swaths of land have massive optionality. Let’s hope Scott “I am the house” Bessent continues to lose the bond market. I want to see a bloodbath here.

“Good news. We got you your full $PSKY allocation.”

Keurig Dr Pepper Hires Kimberly-Clark President Torres to Helm Coffee Spinoff $KDP $KMB
McCormick Is Working to Win Over Value-Conscious Shoppers $MKC
Accenture Revenue Rises on Growth Across Geographies, Industries $ACN
$HAS also moved up Barbie-Maker Mattel Draws Takeover Interest From Authentic Brands Group $MAT
getting more interesting Nike Projects Sales Decline This Year After Lower First-Quarter Revenue $NKE
Raytheon Gets $24.4 Billion Navy Contract for Standard Missile-6 Interceptors $RTX
ON Semicondcutor to Buy Synaptics for Cash, Not Stock, in Downsized Deal $ON $SYNA

Would be more interesting if it was $QQQ, but something like this seems good for hedging the market melt up possibility. I'm curious to see if the margin requirement turns out to be the standard 15% on IBKR.

#1 report on $BMBL scuttlebutt in college Girl: “bumble is for old people and wierd” she used tinder for hu and hinge for “quality” Guy: “the gay one?” Went to go scroll on tinder

Is this bullish $PBI?? 🤣
Good god $WY is getting low here. My guess is rates keep going up and assets like this trade down as people pour into yields. But eventually these become a load the boat up buy. Massive inflation hedges and owning large swaths of land creates multigenerational wealth.
@JordanBoekel I have skimmed over $FINV, $LX made good money in $YUMC, looked at $PDD. I think management is even more important given regulatory risk and China and that is partly why I like $YB

Renting AI capacity protects Microsoft ($MSFT) if the AI buildout busts. It leaves Microsoft exposed if compute gets scarce. On Q2 2026 data, Microsoft's implicit and off-balance-sheet infrastructure commitments were 17 times its headline borrowings according to our AI Bubble Barometer. 1. Microsoft signs a multi-year deal to rent capacity. The partner, a specialist AI cloud such as $IREN or Nebius ($NBIS), typically raises the capital, builds the site, buys the chips and owns the assets. 2. Construction risk, the risk that the GPUs lose value, and most of the financing sit with that partner and its lenders. 3. Microsoft swaps capital spending today for rental payments later. Compare Alphabet ($GOOGL) at 10.2 times. Almost all of its off-book commitments are purchase orders, $811bn of them, for chips and equipment Google will own. We read Microsoft's choice as less than full confidence in the buildout, and Google's as the opposite. In our view the market underweights the risk that compute gets scarce. The partners own any capacity beyond their Microsoft contracts and can sell it to whoever pays more. Microsoft would then have to wait or pay up, as it owns fewer of the data centres and chips it uses. That means higher compute costs and tighter margins. On our reading, Microsoft wins if AI demand falls short, because its partners carry most of the asset risk. If compute gets scarce, Microsoft loses, because renting gives it less control of supply, and Google wins because it will own the chips it ordered.
First $Orcl insider buy of >$1m since 2022 $3.5m from board member Stephen Rusckowski

I think $MCD has a better shot of finding a bottom near these levels than $NKE does. People still need to eat. MCD, while not healthy, is still a popular go-to for relatively cheap food (I know its not as cheap as it once was - but its all relative). And MCD still has durable unit growth to point to. Don't think they have brand issues nearly as severe as Nike does. Not advice. Just my 2c.
I don't see an easy turnaround at $nke. Social media has lowered the barriers to entry on athleisure. I get ads all the time from no name upstarts with cool stuff in my Instagram feed. Clearly Nike is losing share in China. Hard to see what turns that around. Most abstract but maybe most important is that the brand no longer resonates as high quality and certainly doesn't seem "cool" at least from what I can tell. 20x on declining EPS. Not sure what turns it.
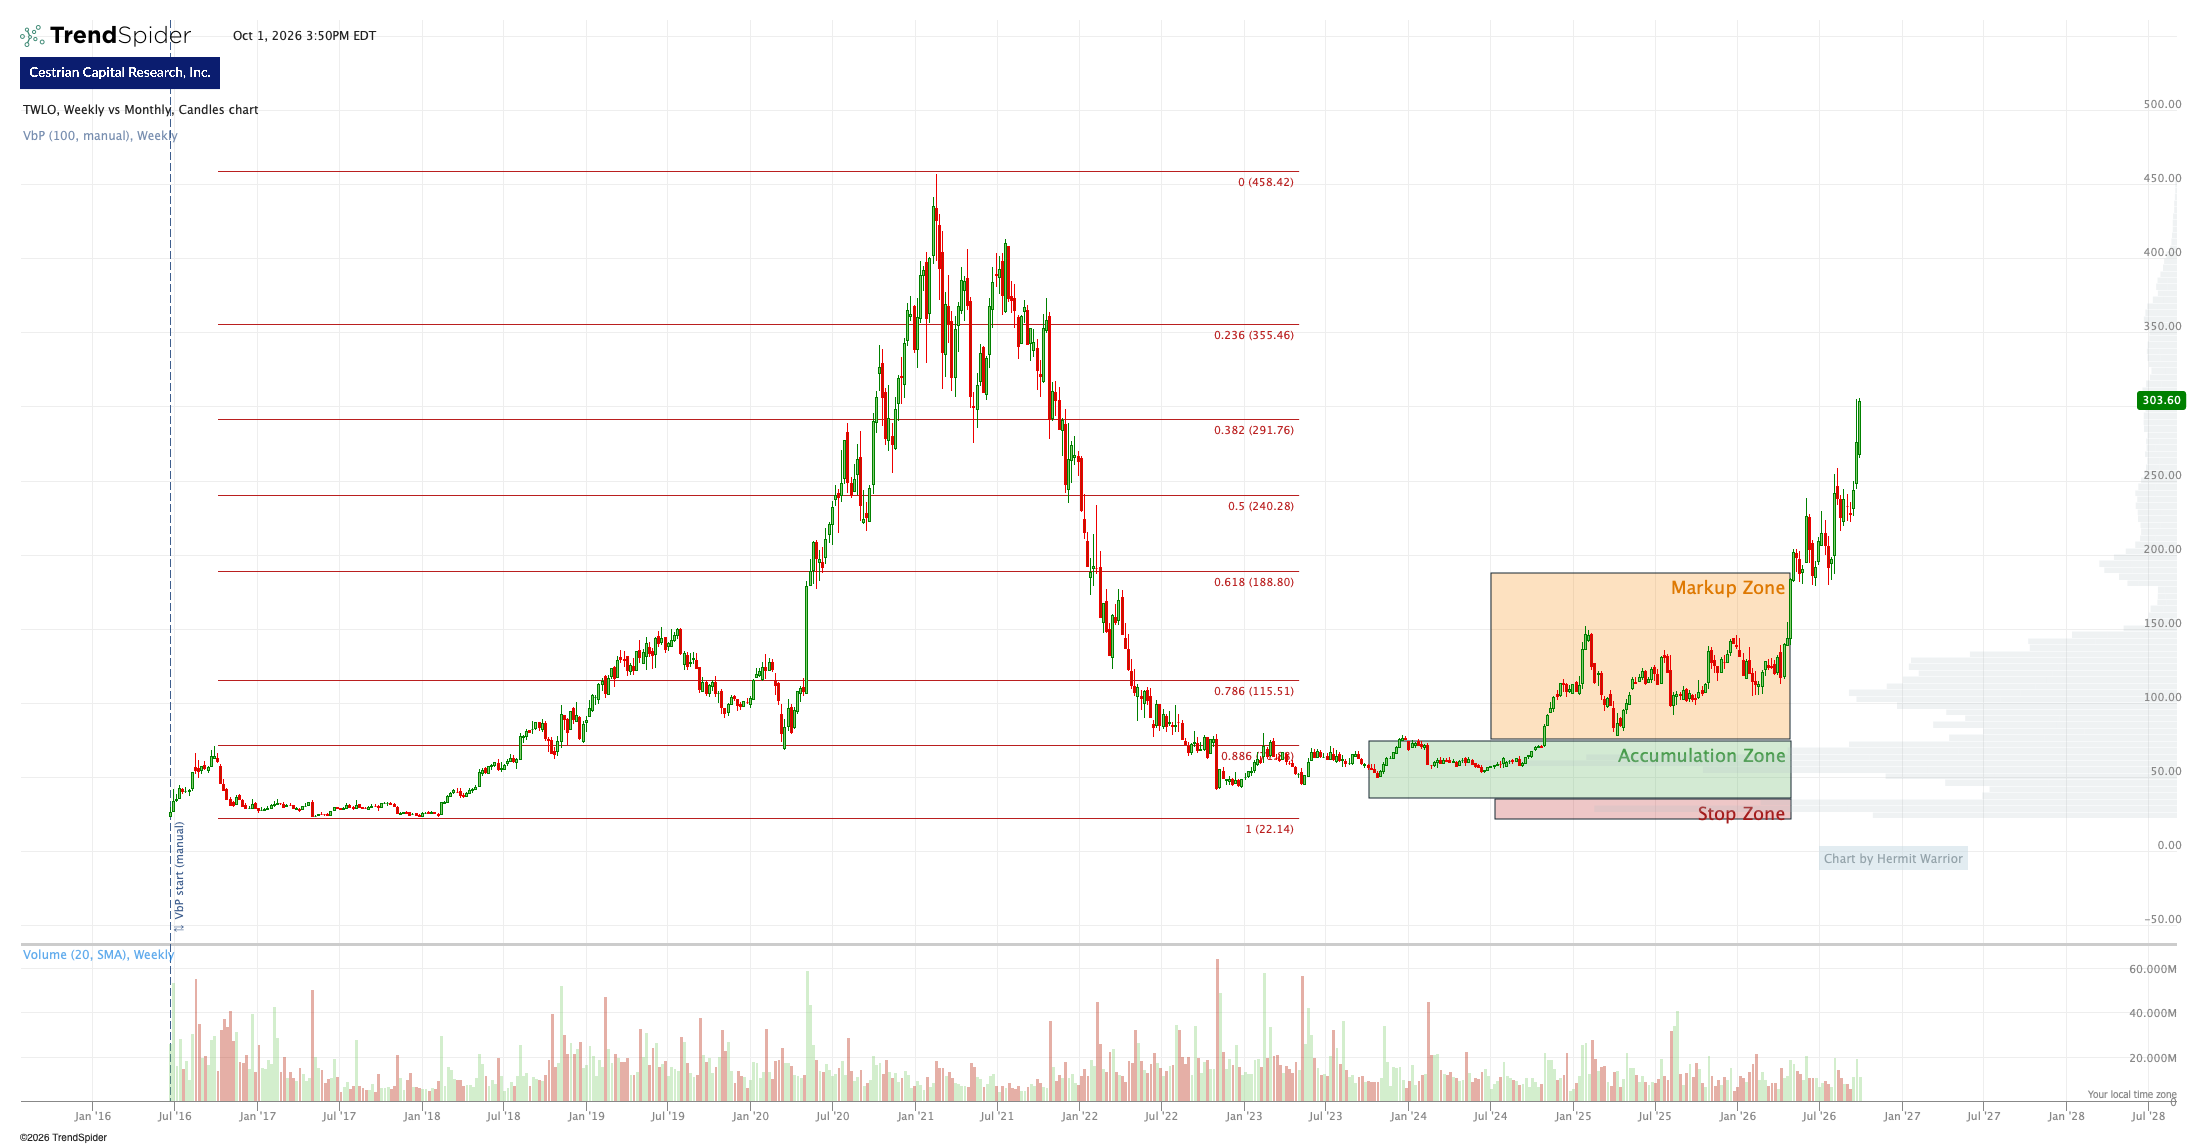
Twilio posted Q2 revenue of $1.50 billion, up 22%, and guided 16% Q3 growth; the note rates TWLO Hold at $305, with a $260 risk line.

$SEV shot-chaser 8k this morning boasts of slashing capital needs to $115m S-3 this afternoon says raising up to $250m anyways I'm naked short calls

At current rates and capital being consumed by AI, cant see the appetite from PE to pencil this out, let alone get the financing in place. There are only two other restaurant chains larger by market cap and that is $MCD which would be over 30% over their current market cap. And would be almost 50% of the other, $SBUX. So no, and markets not buying it either

Would you rather: A. $NKE at 13x EV / EBITDA B. $LULU at a 5x EV / EBITDA C. Chinese water torture
You look at $LQDA? Just received this letter. "Liquidia was on track to generate $1.4 billion in revenue in 2027. Half of the revenue so far has been from PAH and half from PH-ILD. Net margins are likely to be in the 50% range. If PH-ILD is removed, we assume $700 million in revenue and $350 million in cash flow. At a reasonable multiple, we would be looking at a stock value from that sales market between $44 and $55. If there is a 30% royalty on PH-ILD sales, we would have $350 million in cash flow from PAH and $245 million in cash flow from PH-ILD sales. At a reasonable multiple, we would be looking at a stock value from that sales market between $75 and $94."
1/ Went thru Leslie's first day declaration so you don't have to. The biggest US pool supply retailer JUST filed Chapter 11 yesterday with 900+ stores and $787mm of debt. $LESL
Anthropic spent $2.75 per revenue dollar in 2025 and committed $518 billion to compute, while AI debt at CoreWeave, Oracle and data-center…
@GardinerIsland also worth noting that $BWET is 90% one tanker route. It is not a clear reflection of global tanker margins.

@310Value @StockTalk416 It’s also not saying pinned because it’s not definitive. Look at the price action of the comps. Massive $GFL call buying $RSG $WCN

$GEN CEO posted thoughts around their acquisition process on LinkedIn

@kiwicarrotcake @valuedrift I own $KOF, $HERDEZ and $ALSEA so not really looking for more of this kind of exposure. But the company is fine.
Constellium’s widening feedstock-to-end-price spread supports 2026 EBITDA guidance of $980M-$1.02B and free cash flow above $300M.
 Andres Veurink
Looks like $APP and $EVC are doing some things together.

@trvsrdrgz2 no. I am loudly saying that you should borrow against the car you live in to buy 1000 more $AMC.
Regeneron and Sanofi expanded their antibody partnership, giving REGN $1 billion upfront, up to $7 billion in milestones and a 50:50 global…
I feel AI can answer this better than me, kind of just giving more context on my other response. 54 sources used. Good read for $YB investors: Acquisition tactics repeatedly described as traps Chinese media, Black Cat (Heimao) complaint records and consumer-association notices describe a variant of the industry “magic-cube” (魔方) funnel that regulators have tried to curb since 2020–2021: - Pop-up and short-video/mini-program ads offering “first month ¥0.6 / ¥1,” “free claim,” or “¥1 for high coverage.” - Low-friction flows (SMS code, minimal identity checks) that default or bury auto-renewal, password-free WeChat/Alipay debit and upgrade from a one-month “experience” policy to a full-price monthly plan (often ¥90–800+). - Terms, health declarations and price jumps placed in small print or behind easy “next” clicks. Elderly users in lower-tier cities are disproportionately cited; children frequently discover multi-month or multi-year deductions only when reviewing bank or Alipay statements. - Documented examples include continuous deductions totaling ~RMB 1,500–2,200 over months and one multi-year case claimed at ~RMB 22,400; several policies sometimes opened on the same person. Refunds are often obtained after platform or media complaints, sometimes with partial fees withheld until complaints are withdrawn. A 2022 Shaanxi banking-insurance regulator fine (RMB 10,000 on the brokerage entity plus warning/fine on an executive) cited failure to conduct internet brokerage business as required. In 2024 the Gansu Consumers Association publicly criticized a related agency (Shouxin) for enrolling and debiting a consumer without authorization. SEC 20-F risk factors discuss dependence on third-party traffic channels, evolving CBIRC/NFRA online-insurance rules (including limits on intermediary marketing of personal lines), reputation harm from complaints, and the need to retain consumers, but do not specifically disclose the auto-debit or “first-month” funnel controversies. Not unique to YB The same pattern is widespread among Chinese internet insurance intermediaries. Waterdrop (水滴保) has drawn larger complaint volumes on the same platform (reports of 2,300–3,200+ entries) and has received larger fines (including a RMB 1 million penalty tied to “first-month zero” sales). Zhonghui Mutual and other carriers appear in parallel cases. Regulators have repeatedly flagged “first-month ¥1,” default upgrades and unperceived auto-debits; a 2026 multi-agency network-marketing rule (effective 30 September 2026) adds mandatory reading timers, bans one-sided promotion of the first-period premium, requires one-click popup closure, and prohibits default bundled sales and unauthorized automatic charges. Management statements and evidence of change - 2022 company responses (Sina Finance and others) defended “first-month ¥1” products as carrier-designed and regulator-filed, said many listed complaints predated tighter rules or were mis-attributed, and claimed near-100% resolution of its own cases with relatively low complaint counts versus peers. - August 2026 responses to Pengpai/The Paper on a specific ¥0.6-to-full-premium case asserted that backend logs showed completed login, disclosure reading, health notice and bank authorization, called the enrollment compliant, and issued a full refund “to resolve the dispute and improve service,” not as an admission of fault. The company stated that 2026 flows added mandatory reading countdowns and stronger confirmation steps; independent media tests of the WeChat mini-program confirmed longer forced-read sequences and the removal of some ¥0.6 experience creatives. Quantitative signals are mixed. Black Cat counts cited across 2022–early 2026 cluster around 850 rising to ~1,200 and then largely plateauing while new policies scaled into the tens of millions (one outlier report cites a much higher cumulative figure under broader search terms). Absolute complaint volume is therefore small relative to 30 million+ annual policies, yet the cases that surface are concentrated on elderly users, multi-month silent debits and difficult cancellation—exactly the pattern that generates media coverage. Many disputes end in refunds once escalated. High marketing intensity continues, consistent with reliance on low-friction paid traffic. How large is the problem? It is real and recurring, documented in complaint platforms, consumer-association notices, small regulatory actions and consistent anecdotal patterns, but it is amplified by media focus on elderly victims and by the emotional visibility of “unknown deductions.” It is an industry feature of high-CAC internet insurance distribution in China rather than a YB-only practice; peers show comparable or higher complaint intensity. Upcoming 2026 marketing rules directly target the tactics described. Filings treat the issue mainly as general regulatory and reputation risk rather than a disclosed operational failure.
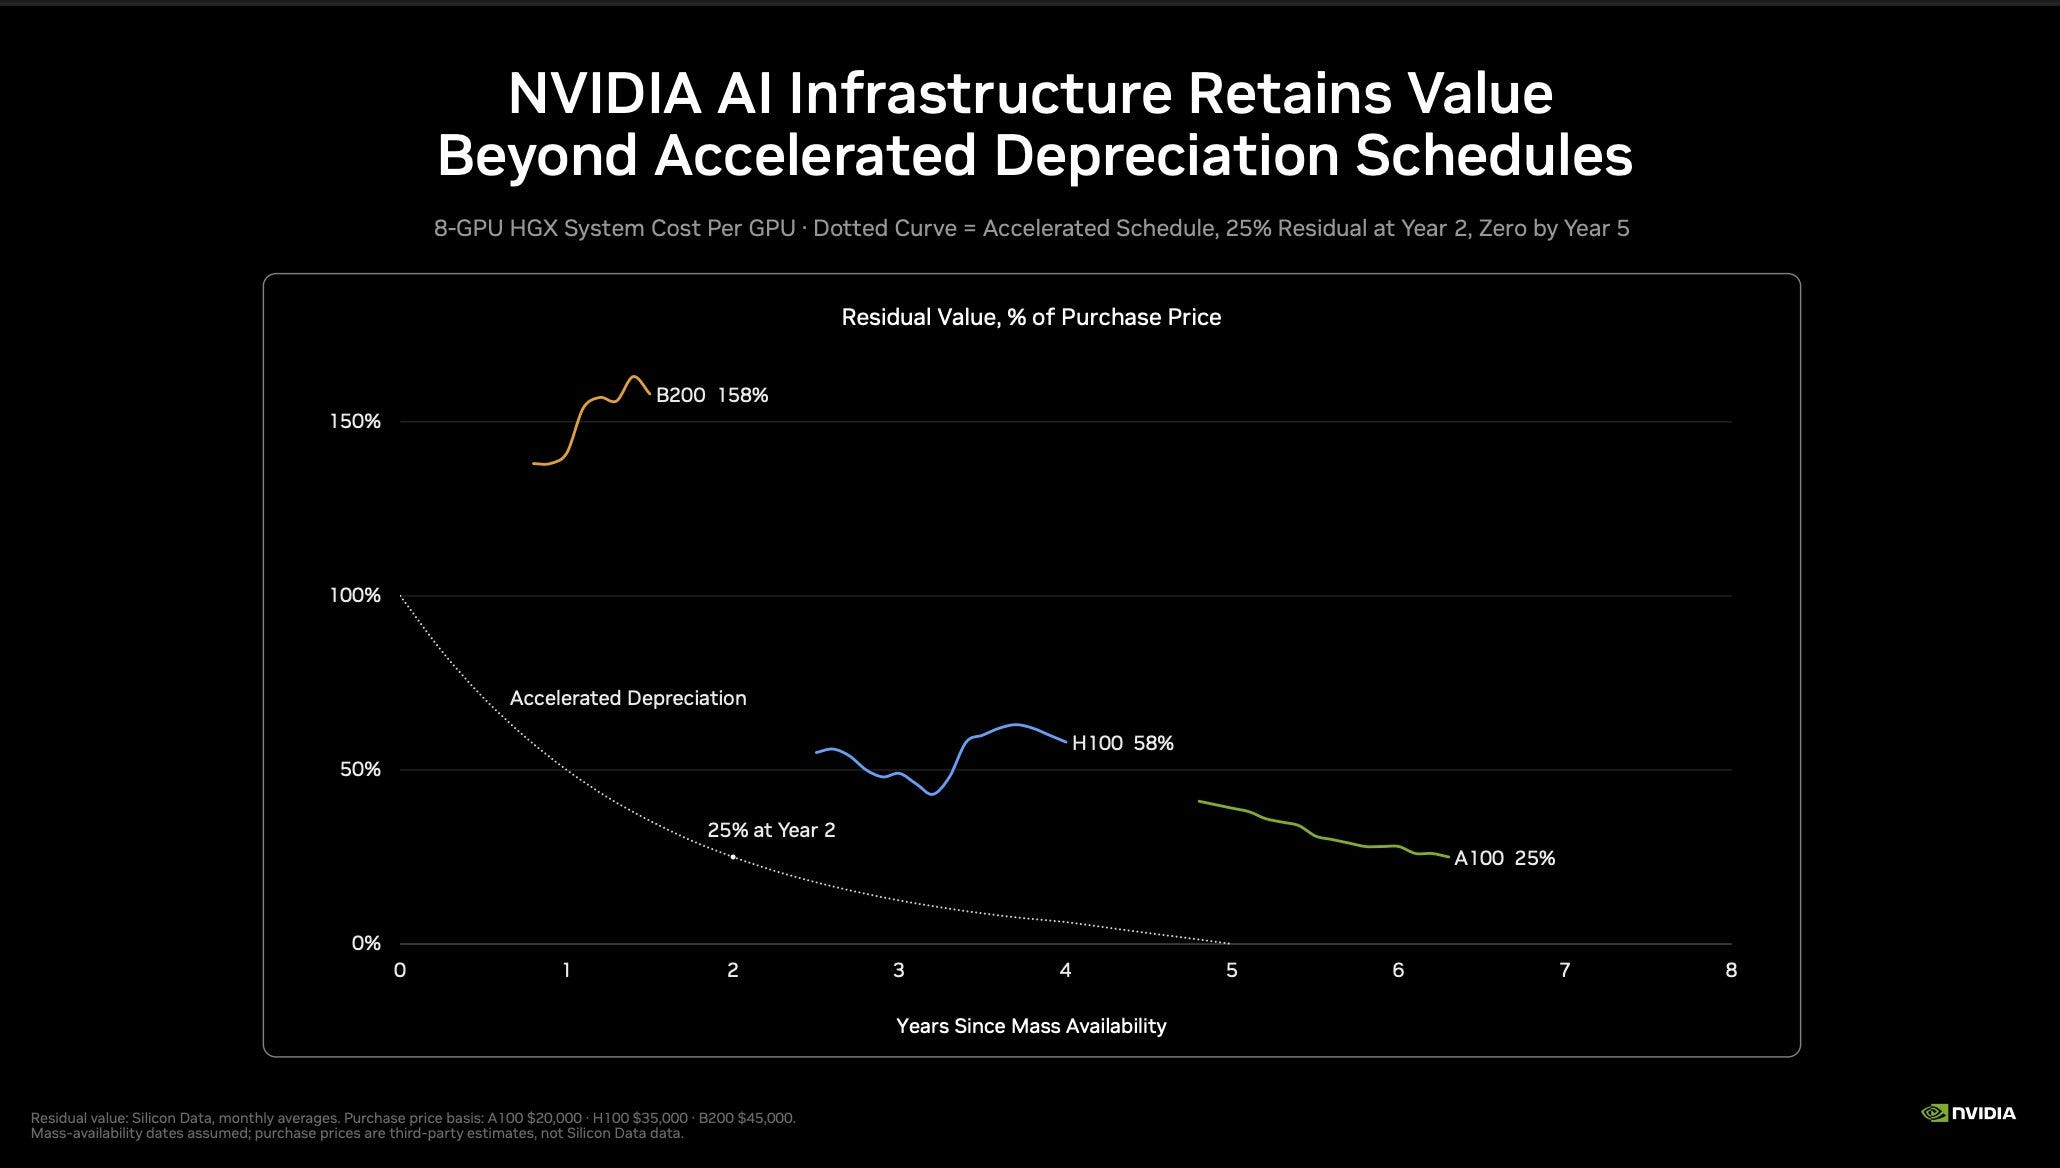
Nvidia argues A100, H100 and B200 GPUs retain value beyond five-year depreciation schedules, reviving comparisons with the 1960s…
$EVC is going to zero btw
@rinnecap Yes, $FSLR <$175 is a joke. Just like $TLN < $290… Patience, it will come back.
Muse could sidestep ads by becoming a neutral commerce agent, while DoorDash and Airbnb build proprietary agents that steer users toward…

Qiagen $QGEN has a new CEO (Jonathan Pratt) per Sept. 1. Let's see if he can bring some action. The company also recently confirmed it continues to evaluate strategic alternatives, with Goldman Sachs involved. There have been reports of takeover interest for a long time, with past reports linking Qiagen to Thermo Fisher, bioMérieux, and Bio-Rad. Qiagen is an interesting target given its leadership in nucleic acid prep, strong consumables-driven revenue, and growth areas like TB testing and digital PCR. The portfolio would fit well with major industry consolidators.
@LandlordWayne $ball $sack $nuts
@WiseAle2 of course $AMC is manipulated. Ken Griffin does it. Why do you think you can beat him? He owns a dinosaur!

No one is really talking about it but defense names, and in particular larger names, have sold off quite violently. $ITA is down 20% since mid August and is now red on the year. For names which aren't highly subject to programs which might get cut during CR debates post-midterms, there are really attractive valuations as many have just been caught up in the capital rotation. For these names, there might still be some delays w/ funding, but ultimately, it will flow, and quite a few delays have been priced in at this point.
$FDXF 👀
$FUBO 👀
$OWL 👀
$FSLR 👀
I probably could. And I am glad you are fighting naked short selling because I value market integrity. Someone has to fight the good fight. I would join you - but I am not suicidal. I do not like throwing my money away. You can't beat Ken Griffin. So long here is stupid. And if you can't beat them, join them. That is why you should short $AMC.
$CORZ 👀
Chipotle's Q2 revenue rose 9.3% as traffic and market share grew; the case rests on pricing catching inflation to restore margins.
 The Alpha Analyst
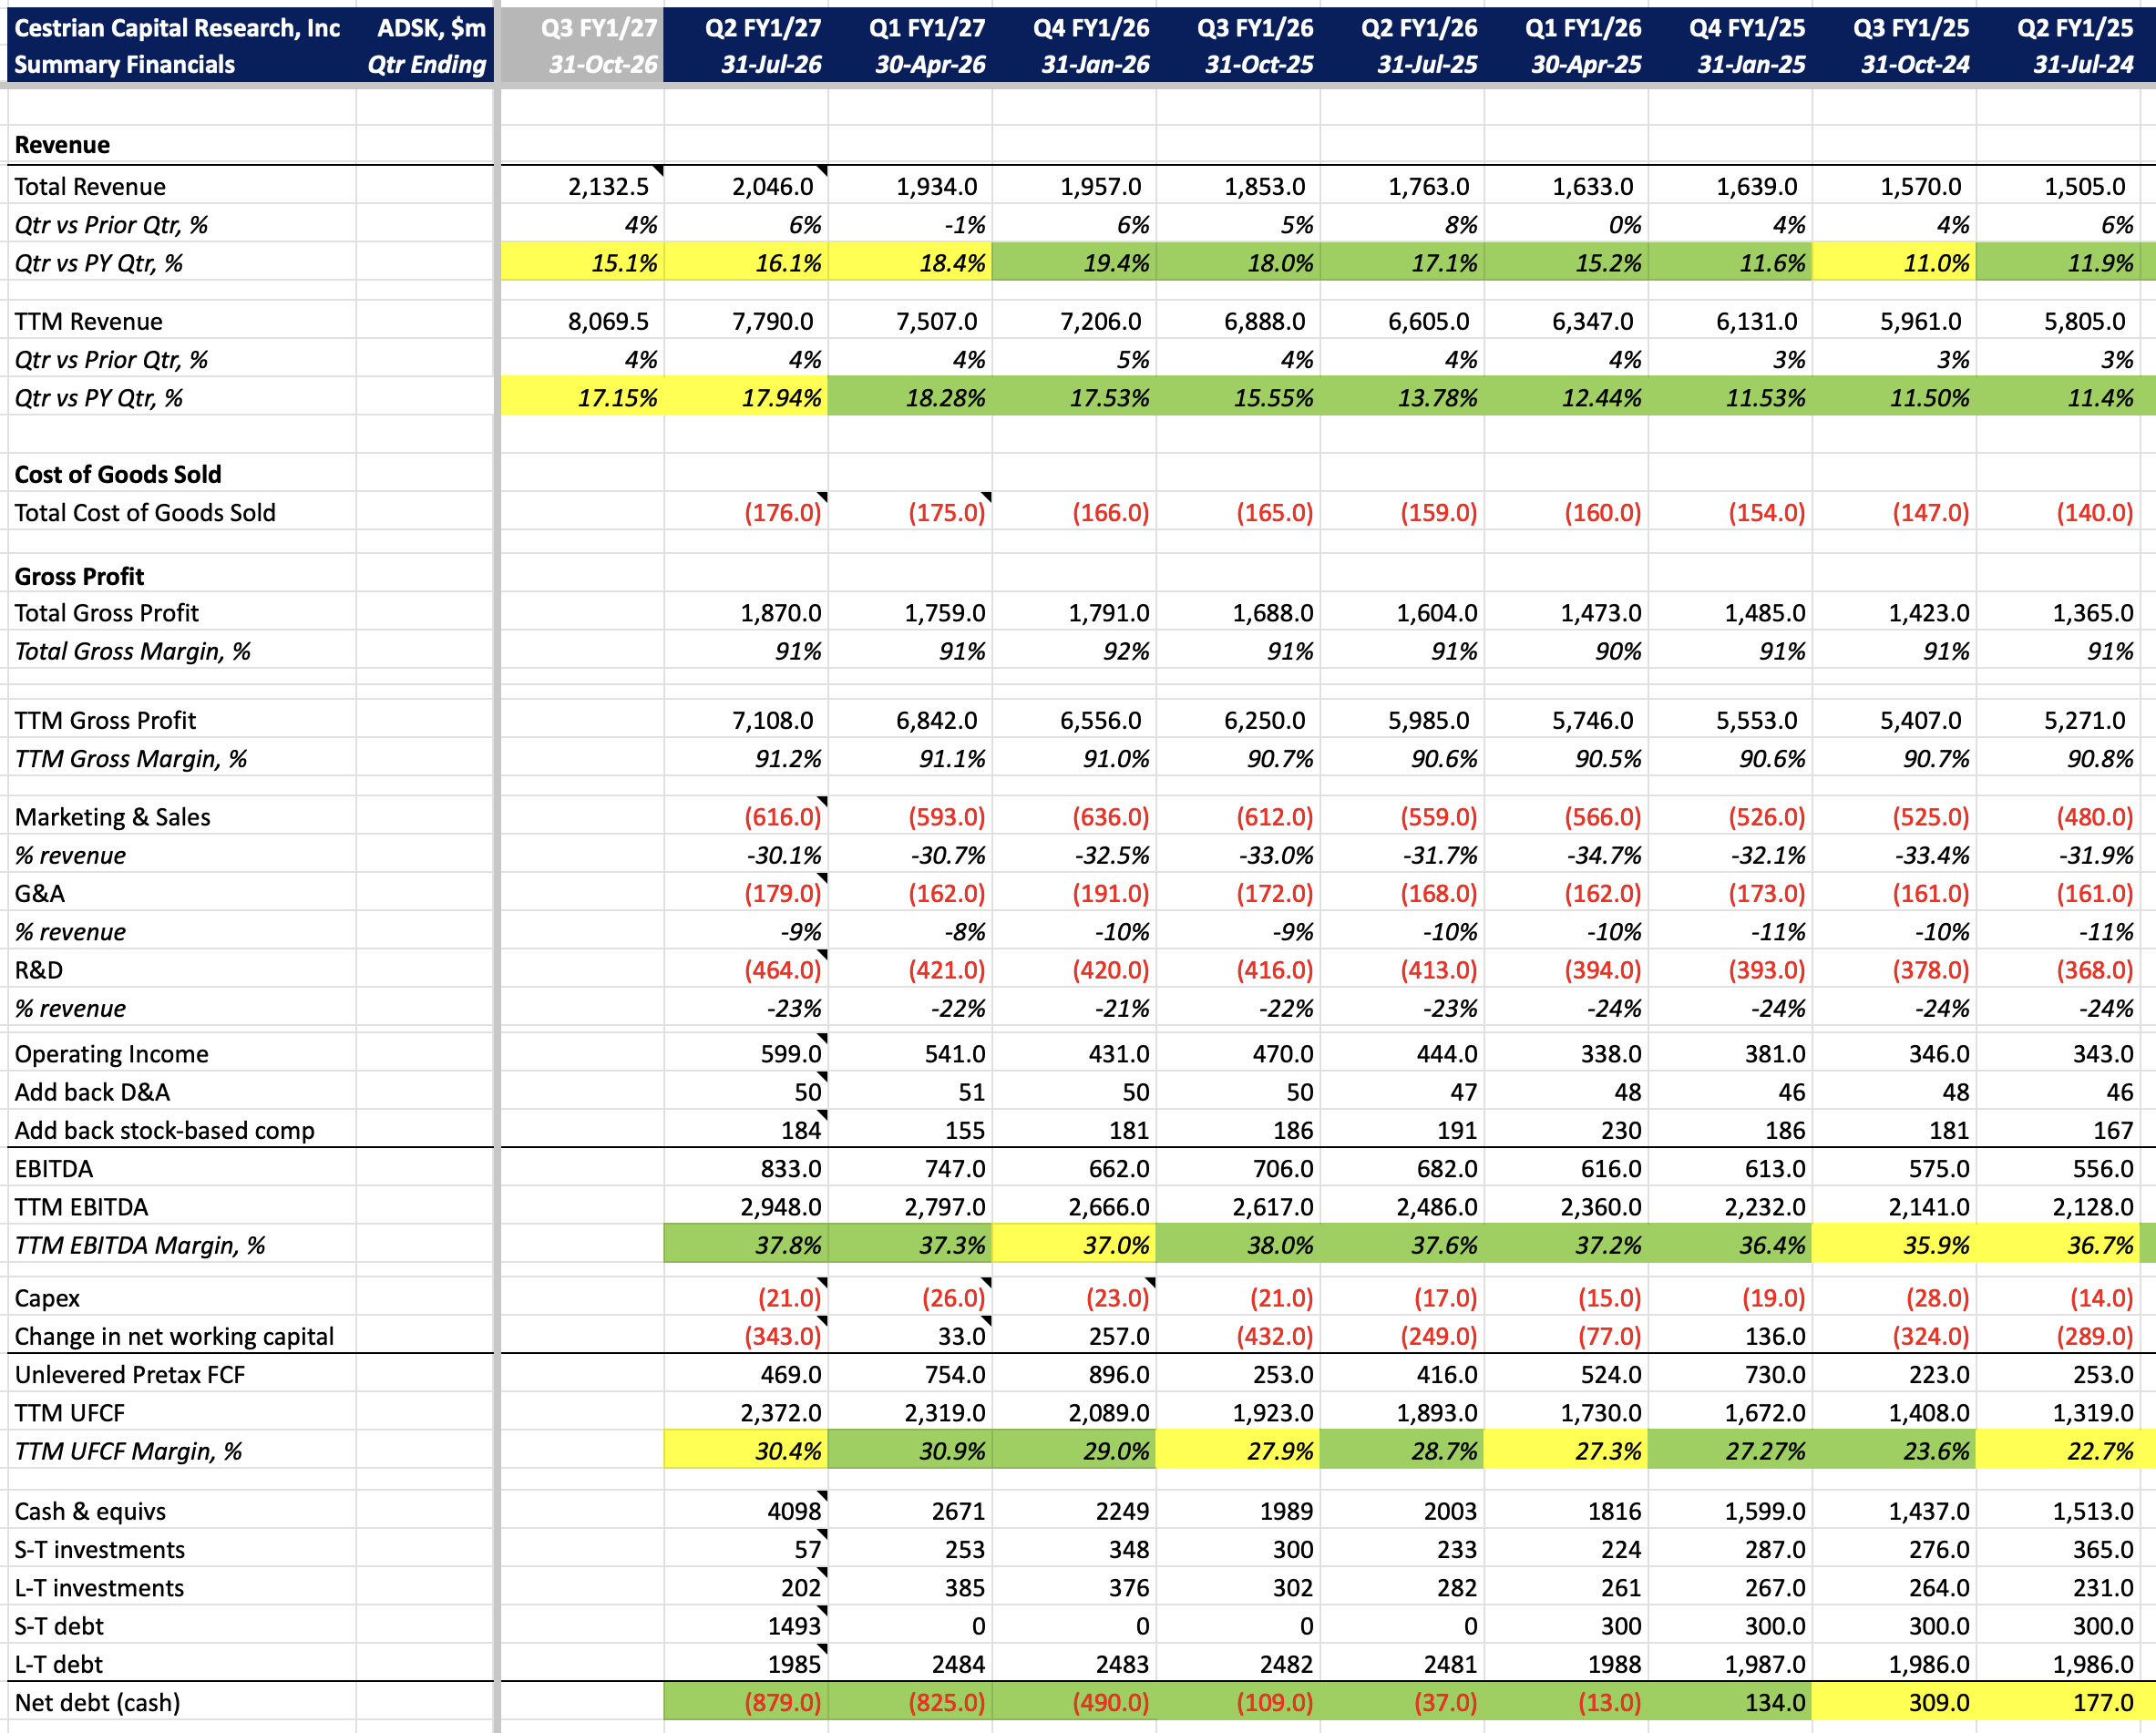
Autodesk reported Q2 revenue growth of 16% to $2.05 billion, while RPO growth slowed to 2%; FY2027 guidance calls for $8.30 billion to…
YieldMax HOOD Option Income Strategy ETF pays high weekly income from Robinhood volatility, but return-of-capital distributions and a 0.99%…
 Ivan Gaddari 1 click

Sign of the times department: $LRHC the one high flying residential real estate brokerage that grew to more than 3,000 agents as it tried a different version of the MLM model successfully implemented by $AGNT, has decided to PIVOT to.... You guessed it, a neo-cloud. The company announced that it acquired $NVDA B300s today and is pursuing strategic alternatives for its real estate division. If only there were signs....
Yes, obviously some nuance depending on what site but I see what you mean, one listing 1,217 complaints. They did have a 100% resolution rate which was nice to see. Also the article in June 2026 about a women’s complaint. This is a risk to watch as it mostly stems from them selling low priced first month policies (0-1RMB) which then go to say 100RMB a month that people get blindsided by. This is also a regulatory risk as regulators have mentioned against this. $YB

Turning Point Brands' FRE and Alp nicotine pouches aim to become a third C-store brand behind ZYN and Velo as PMTA rules limit new entrants.
Ethos Technologies ($LIFE) sells AI-driven life insurance while relying heavily on multilevel marketing agencies using aggressive cold…
Turning Point Brands targets third place in nicotine pouches behind ZYN and Velo, with FRE and Alp nearing half of revenue despite falling…
$EVC is deep value here. Market drunk at the wheel.
Karman Holdings reported 58% Q2 revenue growth, $1.3 billion backlog and margin expansion while replacing leadership and remediating…
The 10yr $PSKY HY bonds already down ~5pts on the break Thanks for playing
Software sentiment matrix from JPM’s Schilsky I guess Dreamforce with guest appearances from Jensen, Dario and Sama wasn’t enough to fix $CRM sentiment

$EFXT is like the little engine that could… announces a major data center fabrication deal.
Innodata's 45% pullback resets its valuation after two quarters of 50% revenue growth, though two customers still supply 71% of revenue and…
 Kurt Christensen
@DadInvest @baldridgecpa Pacifico Airports $PAC has 80% gross margins. Pretty good for a not tech biz. Not sure how to run the business without employees or customers though...
Inference repeatedly reads the same model weights, with far fewer writes than training. 1. In training, weights are constantly updated, so the memory sees heavy read and write traffic. 2. In inference, the dominant pattern is repeated reading of the same weights, and the key-value cache alongside them, with far fewer writes. That is the case for putting AI model weights on flash. Flash has traditionally been weaker than DRAM on write endurance and write speed. A read-heavy, write-light workload plays to its strengths and gets around exactly those weaknesses. Today AI chips sit beside HBM built from stacked DRAM, and it is the expensive part of the memory bill. High-Bandwidth Flash (HBF) is the product built on the read-heavy observation. It aims to deliver HBM-like read bandwidth at far higher capacity and lower cost by using NAND flash instead of DRAM. Two caveats. These are aims, not measured specifications. As of our early-August note, the first prototype from Sandisk ($SNDK), developed with SK Hynix, was expected later in the year. HBF is also more specialised than commodity NAND, where Chinese producers are expanding capacity aggressively.
$GOOG’s Gemini 4 gains

@7week_sunday Based on the last conference call, the $LEAT quarter should be good. There was some really great information arbitrage. @InfoArbMonitor Delta Sheets goes over some of it (full disclosure: this X is one of my projects)
Micron’s AI-driven memory demand lifted Q4 revenue to $54.23B and non-GAAP EPS to $33.42, while 26 customer agreements cover over 35% of…
 Tom Dorsey 1 click
A lot of cheap catalyst names out there... $OWL @ $9.00 $CMCSA < $22 $VISN < $6 $AKER.NO < 1,400 NOK $MGBL @ $17 $DRVN < $12 $FM.TO < $40 CAD
@teechongyen Terry Smith: Owned $ADBE much higher already sold. Recently bought $FICO and $APP just before they crashed. Man doesn't miss.
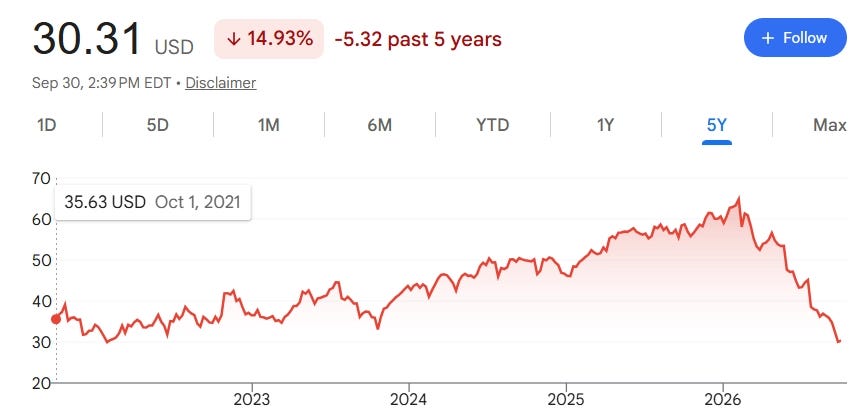
Rollins’ shares have fallen more than 50% from their peak, resetting valuation as route density, reliable service and pricing support…
Meta's Muse AI agent is presented as an early monetization catalyst, while heavy CapEx is framed as a moat despite near-term cash flow…
 Andres Cardenal, CFA
Pearson, CarMax, Talen Energy, KBR and Apollo Commercial Real Estate lead a 33-company survey of activist campaigns, buybacks, M&A and…

Portfolio end of September '26: Evolution $EVO Secunet Security Networks $YSN Parigroup $CEV.HM Leatt $LEAT BioRem $BRM.V Toyokumo $4058 -undisclosed- Shelly $SLYG Lindbergh $LDB.MI ErreDue $RDUE Enogia $ALENO.PA -undisclosed- Circle Group $CIRC.MI -undisclosed-
HubSpot trades at 18.4x forward earnings and 3x sales after the SaaS selloff; a DCF using 22% FCF growth values shares at $302.66.
 Bishop Research and Analytics 2 clicks
TWOD holders can tender at $26.3841, sell before October 2, 2026, or await roughly $26.7578 in final redemption proceeds.
 Colorado Wealth Management Fund
$KBR filed Form 10 for spin-off of "Trinzic" Investor day presentations scheduled for November
Ladder Capital trades below book value with high yield, but faces margin pressure and office-loan exposure despite diversified funding and…
 Albert Anthony
Group 1’s 19% ownership cap, tied to automaker franchise agreements, frames Conifer’s 1.9 million-share stake and potential buyback-driven…
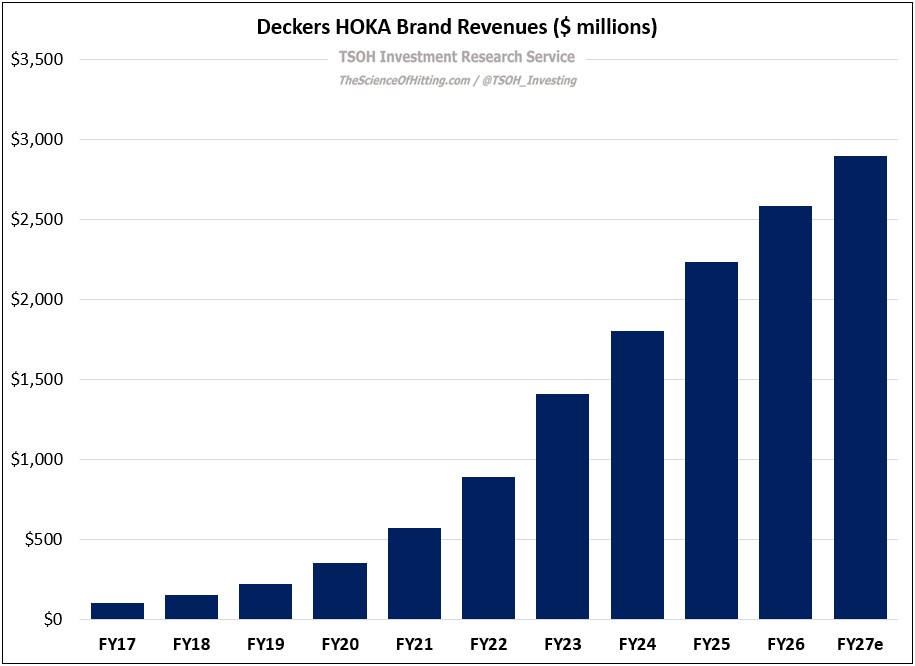
Deckers built HOKA into a brand nearing UGG’s scale, with HOKA revenue up about fivefold since FY21.

Q3 absolutely sucked, and my performance currently stands at 37.8% YTD versus 65.8% at the end of Q2, marking the worst drawdown from a high since I started sharing my buy/sell decisions on Substack. Apparently, the Market Gods decided this is what you get for calling your last portfolio update “Half-time Lead.” …I’m just glad I didn’t use a Buffett quote. That might’ve finished me off. While I barely felt the pre-2024 election volatility, the spring 2025 tariff scare, or the start of the Iran war in 2026, Q3 broke that pattern. $EVC, my largest position, fell more than 40% from its highs and made sure I felt this one. The portfolio’s relative resilience, something I’d come to appreciate, disappeared with it. Of course, I have plenty to say about Entravision, but I’ll save the fundamental developments for later in the article. Q3 was a season of portfolio pruning (wow, I never thought I’d use that phrase). I exited two winners, realized one loss, added to a large position, saw a rare billion-dollar-plus company find its way into my portfolio, and ended the quarter with 6% in cash versus 0% at the end of Q2. I ended Q3 with 11 holdings, with the top three accounting for 53% of capital and the top five for 70%. Portfolio beta also came down from 0.95 at the end of Q2 to 0.80 at quarter end. That is still elevated relative to the portfolio’s historical level, largely because my biggest position carries a beta of 1.68, while every other holding sits below 1. I’ll save the longer performance review for year end, when we can hopefully put what I still consider a satisfactory 2026 into proper perspective. For now, I think it’s better to focus on what actually matters for a concentrated stock picker like me: what has changed fundamentally, how those developments affect the risk/reward, and where my conviction stands today. As usual, at the link below I went through the portfolio from the smallest position to the largest.
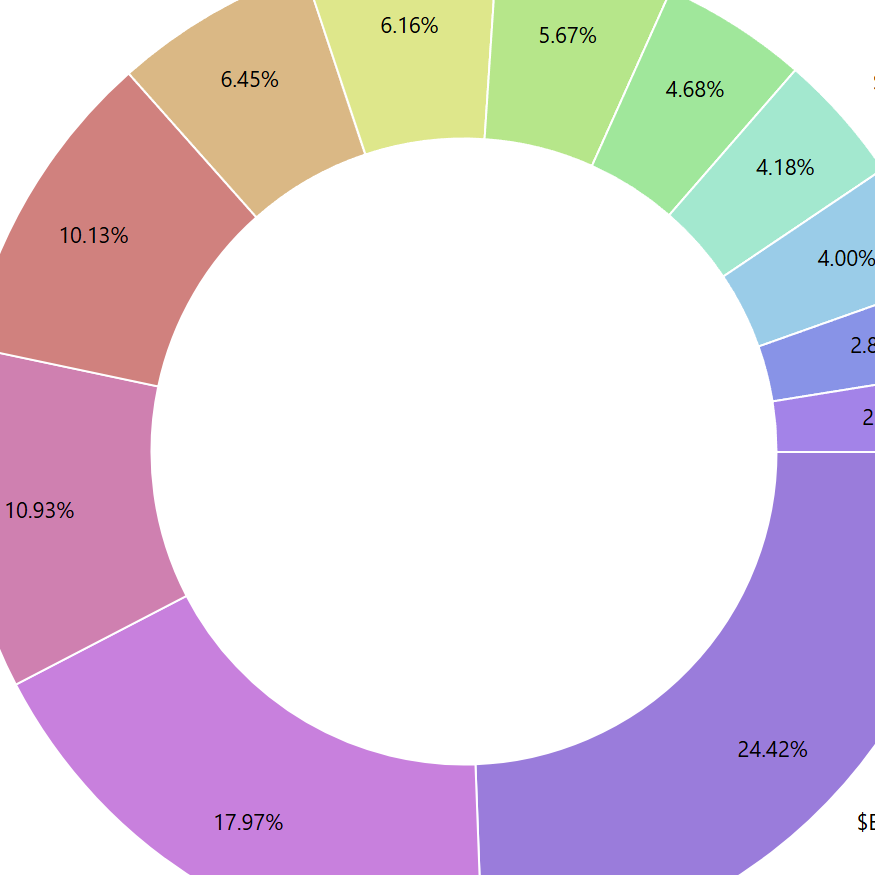
Entravision, the portfolio’s largest position, fell more than 40% from its highs as Q3 returns dropped to 37.8% YTD.
Irrational Analysis reports 51.55% outperformance versus a semiconductor ETF, adding Credo for SerDes and QMCO for AI-driven tape storage…
I just published the Portfolio Update for September 2026. It includes: ▫️My current Portfolio & position sizes ▫️Earnings Updates about $CIRC.MI, $RDUE, $LDB.MI ▫️Recent news & information about -undisclosed-, $CIRC.MI, $4058, $SLYG
LeMaitre Vascular’s shift to larger acquisitions lifted its success rate to 80% and gross margin to 72%, supported by $376 million of cash…
 Bruno Montoya Amador
A bit of surpsied to see OpenAI Dot's VM spec is so low: CPU: 9 visible logical CPUs; host reports AMD EPYC 9V74 at ~2.6 GHz RAM: 9.7 GiB total, ~8.7 GiB available; no swap Storage: 32 GiB workspace filesystem, ~30 GiB free Also uses Cloudflare $NET network as egress like Grok Bot does but the computer spec is so much lower than Grok Bot. Maybe OpenAI is just more resource constrained vs. SpaceX given a much bigger user base. The demand for traditional compute, networking and storage will grow crazy as more people start to adopt this cloud agent architecture.

Stock keeps falling, Greg Alexander keeps buying. $GPI skews towards brands doing well (Toyota/Honda (hybrids), Mercedes etc. > Detroit 3 (Stellantis, GM, Ford). Vertu PLC trading at ATH, wonder if there'll be a push to divest Group 1's UK operations at some point.
$orcl
Washington Trust Bancorp offers a 5.8% dividend yield, with C&I loan growth supporting ROE despite 40% commercial real estate loan…
 Sorrento Research
$orcl

