

SouthernValue on X
And yet $MSFT $AMZN $GOOG $AVGO often go down on days when AI or Anthropic specifically has positive datapoints 😆
Wednesday, September 30
Everything we published on this day.
76 stories — the front page that day →
And yet $MSFT $AMZN $GOOG $AVGO often go down on days when AI or Anthropic specifically has positive datapoints 😆
CareDx's rally rests on prior-period collection adjustments, while transplant test volumes grew 17% and competition, management turnover…

$GOOGL Gemini 4 Argon benchmarks got released. Against GPT-6 Astra + Anthropic Fable 5.1 / Opus 5.5. Still coughing nonstop, so will comment on $MU / $JBL earnings later. I've always thought Google's internal models were stellar, but anecdotally, they seem to get hard nerfed shortly after public release... Maybe because of compute constraints? But yeah, looks like Google is back.
@DavidJang0620 I actually thought $JBL earnings were great. But usually if you disagree with how markets reacted, that just means there's a buying opportunity.
Bro, $AMZN semi ETF portfolio is probably going to end up more compelling than what $NVDA owns... Today Amazon signed a $49.8M private placement into PCB maker Gold Circuit Electronics (2368). So now Amazon has ownership/warrants in: - $AAOI - Alchip - $MRVL (Celestial) - $ALAB - $CRDO - $JBL - $FLEX - $STM - $CBRS - $GNRC - $FN - TD SYNNEX - $QCOM - Gold Circuit Electronics And others.. If we look at the private placement amount for GCE in speciifc, it's like .36% of the company... Kinda small financially, meaningful strategically. Esp. since there were claims that GCE supplies ASIC-server PCBs to the four major hyperscaler CSPs... Regardless it's pretty funny to see Amazon to Nvidia start to own all the worlds leading companies. Since Amazon has exposure to the entire supply chain like PCBs now, optical fabric with Celestial, lasers with $AAOI, assembly from $FN to $JBL, ASIC partners like $QCOM / ALchip.

$GLND is absolutely ripping, now at 4.5. I guess it’s a good thing I don’t short small/microcaps. This would’ve been very painful.
Micron Technology beat profit and revenue expectations by double digits for a second straight quarter, but its fiscal fourth-quarter report…
Nvidia, AMD and Micron face the risk that AI data center chip demand falls short of planned semiconductor capacity.
Progress Software shares fell 6% after third-quarter results, as a lower profit forecast offset an otherwise well-received earnings report.
Zentek shipped its first ZenGUARD air-filter order to a Canadian federal facility as its Albany graphite PEA confirmed a US$3.85 billion…
Occidental Petroleum could benefit as declining shale inventories and high rates curb industry capex, tightening oil supply against demand…
 Gen Z Investor

@SilverBacked737 @ishedtruth444 I know you were not talking to me. But I hope you buy more $AMC anyway.
@SilverBacked737 @ishedtruth444 I am not mad about you buying $AMC. I have tried to encourage it. Please buy more.

@P_Remarks $THEON $DLO $TOI.NE
Meta’s Muse illustrates how persistent AI agents shift compute from per-query to per-user, driving heavier GPU, CPU and memory demand.

Happy $MKTW dividend day for those who celebrate ( $PAGS $EVC too)

$PANW and $DDOG both put something real inside the customer's systems that an AI lab cannot recreate by calling SaaS APIs. Palo Alto's install is still harder to replace with AI. 1. Datadog's agents mostly sit outside the traffic and watch production. A bad agent version rarely takes the business down the way a bad firewall rule can. 2. Palo Alto's firewalls and SASE cloud gateways sit inside the traffic and decide what to allow, deny, decrypt or inspect. A wrong allow or deny hits live traffic and live machines. 3. Many Datadog users start the day in a coding agent and open Datadog when something looks wrong. Many Palo Alto users start in its console and stay there through alerts, triage and response. For them, an outside AI agent is an add-on. Cybersecurity work splits two ways on AI risk. Work done before code ships ("shift-left") or from outside the traffic, such as scanning code, checking cloud settings and sorting collected alerts, gives answers that are easy to check. AI agents are already taking over more of it. Work in live traffic and on live machines ("shift-right") means judging whether an attacker is still inside and whether blocking them is safe. That is more ambiguous and mistakes cost more, so enterprises move slower and demand earned trust. Palo Alto is not risk-free. In our view its exposure is the easily checked detection and vulnerability work inside its platform, which AI agents can take over sooner. The threat is not an AI-native firewall startup.

American Assets Trust’s $AAT Chairman Rady continues to buy shares, now already owning 38% of s/o. The 13D also mentions that he may ‘discuss or encourage extraordinary transactions - including mergers, take‑private deals, asset sales, recapitalizations or board/management changes.’
@grok compare the revenue $RGTI has earned ytd with the proceeds of $RGTI insider stock sales ytd

Pretty good thesis on $MNRO here. I think it gets sold soon.
Chevron moved to Distribute at $204 after Q2 free cash flow reached $18.1 billion on $104 Brent, with near-peak margins driving supernormal…
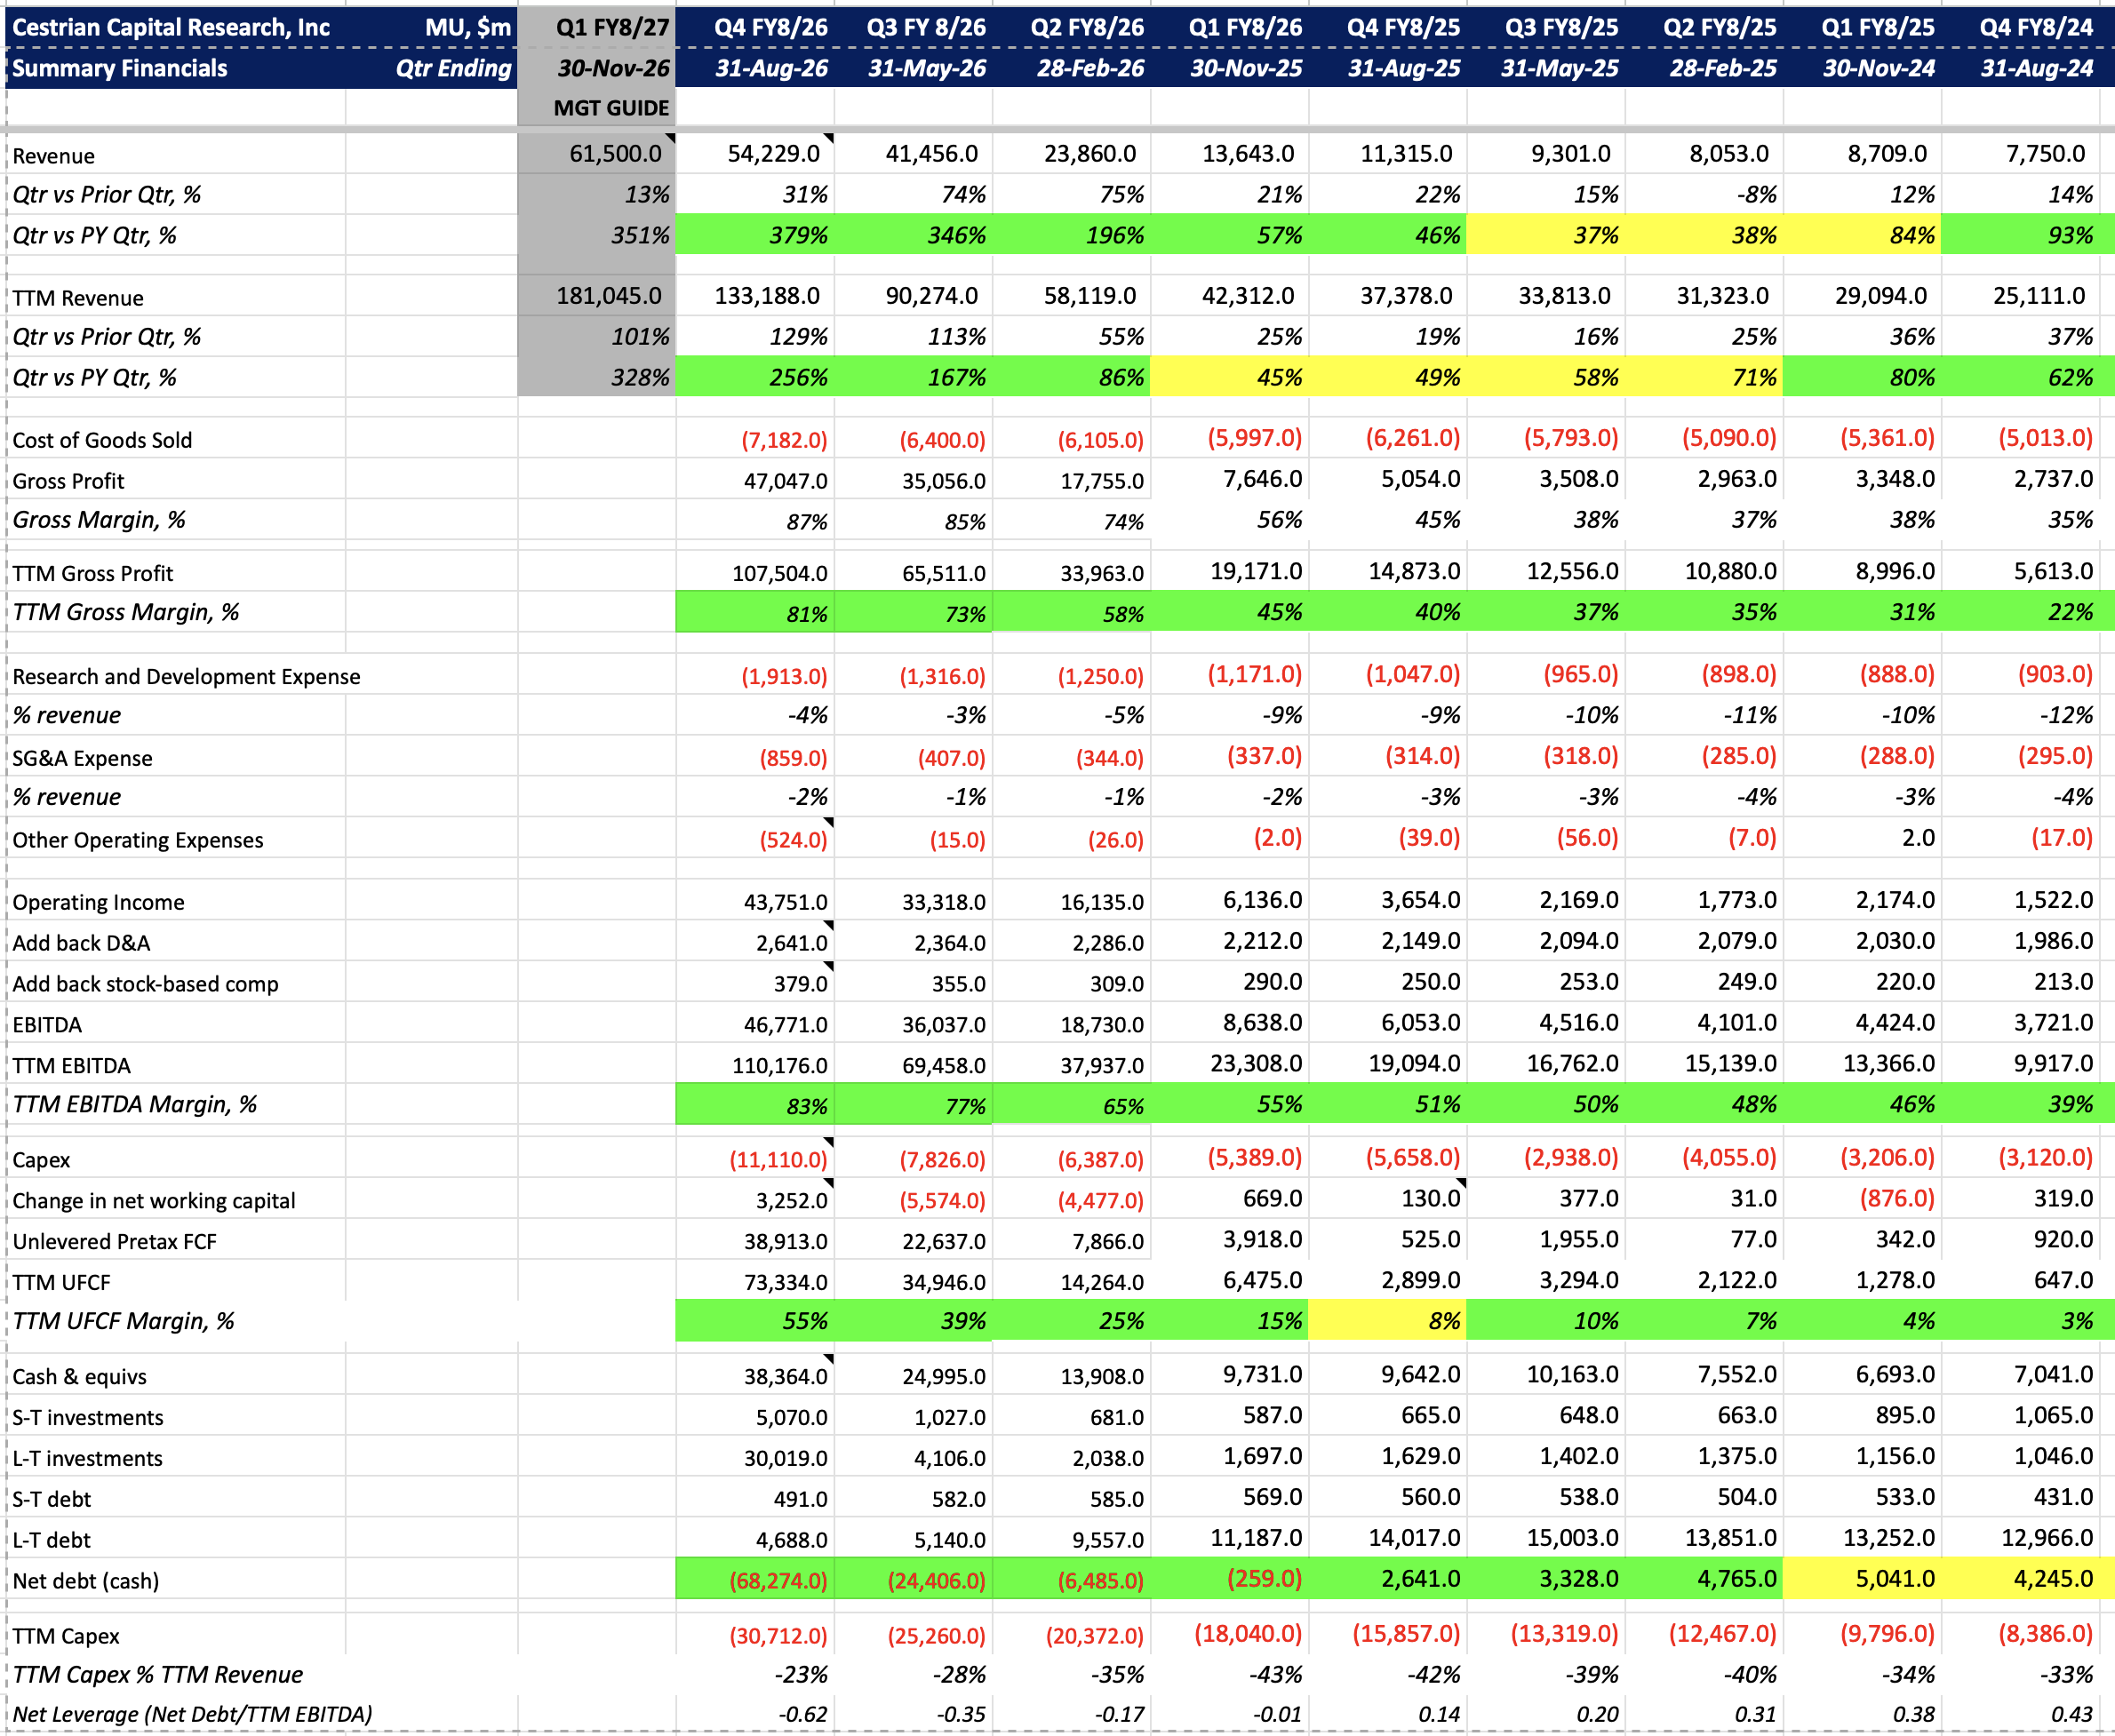
Micron reported Q4 FY26 revenue of $54.2 billion, up 379%, and guided Q1 revenue to $61.5 billion.

@ArgonathCapital Yeah Nice Info services and Misto (paired with a $GOLF short) are large positions for me.

These benchmarks are great, but I'm waiting to see how it does in the bridge benchmark :) also - probably should be long $GOOG

Gemini 4 - "Across most benchmarks, Gemini 4 Argon beats OpenAI’s and Anthropic’s top models by a wide margin, and when it doesn’t, it is generally within striking distance of its competition." - New Stack $GOOG ripping. So back

Following the action in $FICO, it seems this post from @pulte has drawn increased investor attention to $STC $FAF $ORI $FNF and their title insurance pricing policies. We have had a short call on $STC and $FAF for some time. There's no doubt there are several technology options that could lower title insurance costs (AI) if not eliminate the need for it altogether (blockchain). You already have many brokers offering bundled solutions for title, mortgage, and advisory. Lots of pressure on these busineses.
Short Report Review: $EQPT - Blue Orca @blueorcainvest
Yuanbao pairs a 10.2% dividend and cash exceeding its market value with 33.5% first-half profit growth from AI-enabled Chinese insurance…

@NthObject89773 @pradeeepk Given $APP's sketchy history of using data, rather ironic that they would complain about a little turnaround of their tactics.
Corporates (spreads are tight, if this gets rly bad spreads should blow out). Long breadth, consumer exposure and small caps through stuff like $IWM, $RSP, $XSHQ, $RSPD. Short the narrow winners like $QQQ, $SMH, $AAPL, $CRWD, $ILMN, $NBIS. Also shorting long crowded bio longs

@svrnco @ASchulz888 @irbezek Hmm... $TLT implied vol is <15% for the January '29 expiry. Looks like an ATM straddle pays off if rates move by at least 1.5 percentage points in either direction. Probably not a bad trade.
Anthropic's biggest near-term threat isn't the S-1 or AI-safety language. It's competition, especially an OpenAI price war. The S-1 is public, and the timing lines up with OpenAI DevDay. My read is that it isn't a coincidence. That's my read, not something either company has said. What surprised me more came out of DevDay: OpenAI is ending its price war. Here's what that means in practice. OpenAI removed the Pro 20x subscription at $200/month and plans to cut usable tokens on that $200 plan by about half. The allowance was also more generous than it looked. Over the past quarter, OpenAI did roughly 2.5 manual usage resets per week. So heavy users didn't only get a big allowance. It got refilled before they hit the wall, over and over, for about three months. That's a price war fought in tokens instead of list prices, and it is expensive to fund. Why it mattered for Anthropic: for heavy users, cheaper tokens beat a better model. Once a model is good enough, what limits you is how much work you can push through it per dollar. A better model you have to ration loses to a good-enough model you can run all day. Anthropic went the other way and raised margin. That's the right posture for an S-1. It's the wrong posture when a competitor is paying for volume. That left Anthropic in a trap going into the IPO: - Match the pricing, and margin thins just when margin is the story you're selling. - Hold the line, and growth slows as heavy users drift to wherever tokens are cheapest. Either way the numbers get worse at the worst possible time. Ending the price war takes that trap off the table for now. Anthropic gets a cleaner tape into the IPO. Why did OpenAI stop after one quarter? I see two reads, and both are mine, not confirmed: 1. The burn. My read is that OpenAI postponed its own IPO because of how much it was burning, and investors pushed it to stop. 2. OpenAI's own later IPO. If it wants to list, its numbers have to look like a business too. One quarter of subsidized tokens is a campaign. A year of it is a problem in your own filing. The second-order point is that in both reads OpenAI stopped because of its own finances. Anthropic didn't win the war. It ended because the side paying for it chose to stop. The playbook still exists and it ran for a full quarter. It can be turned back on. That's the risk that remains. OpenAI restarts it. Or a rival like $SPCX xAI ships a next-gen model and discounts tokens hard to buy share. It's a bit like Uber's cash burn: a well-funded player can keep subsidizing longer than a margin-focused company wants to wait. I don't think that's fully priced in.

$CODI < $11 with a potential major asset sale coming is too cheap given underlying value. This thing moves on like $2mm of volume. Illiquidity is both a blessing (dislocations) and a curse (violent gaps)… 🤷♂️
Vicor, Rayonier, Accenture and nine other lesser-covered stocks make up Seeking Alpha’s Undercovered Dozen.
 The Undercovered Dozen 5 clicks

Another one bites the dust. $LESL
Fitch just assigned Tesla a 1st-time BBB rating and people are already speculating about a big inaugural IG bond deal Remember when they had JUNK bonds? The coupon on the 2017 deal was 5.3% (not a typo). In retrospect, that's cheaper than what they'd pay for IG money today $TSLA
Both Up Fintech $TIGR and Futu $FUTU benefited from Asians YOLO-ing into 3x levered long MU and SPCX ETFs, with FUTU now up significantly since the regulatory crackdown in May. They only started throttling Mainland accounts in mid-June so the real impact won't be visible until next quarter. ~12x P/E ex-Mainland if you annualize Q2, although Q3 is bound to be a little weaker.

Ben Pouladian argues AMD’s Helios racks cannot match NVIDIA GPUs’ fungibility and financing appeal as agentic AI shifts the bottleneck to…
Precigen’s FDA platform technology designation for AdenoVerse supports PAPZIMEOS uptake in recurrent respiratory papillomatosis and expands…
 Sean Daly 1 click
Monro, Inc. $MNRO looks pretty interesting here. Probably going to get bought out soon as they have been running strategic alternatives since earlier this year. Lots of real estate so you have downside protection. Carl Icahn will go balls to the wall if it is not sold. November has a lot of catalysts set up.
$MAMA is probably at the most attractive valuation since 3 years ago. And right as they are executing super well. This will be a couple billon dollar company in a few years.

Not good for corn / corn basis. Good for $ALTO $GPRE
$SPCX's Starship reached orbit and delivered cargo. The gigawatts still depend on how often it flies. We have been building the orbital-compute case with three key inputs: kilowatts per ton, tons per flight, and flights per year. 1) Ship 41 reached orbit, about 275 km, and released all 26 Starlink V3 satellites. They are in service. Until this flight Starship had only made short hops and come straight back. 2) The flight was shorter than the plan. One of six upper-stage engines shut down early, and the ship came down at the first health check after deployment, about three hours after launch, instead of staying up for about ten hours. Both stages splashed in the ocean. That was the plan. The ship can take a hard splash and be scrapped. It still delivered a commercial payload. Catching it is how later flights get cheaper. 3) A typical 1 GW site on the ground loses about 370 MW to power conversion, cooling and other overhead that is not the chips. Elon has said terrestrial solar produces about an eighth of the power of the same panel in space: no night, and no atmosphere in the way. In orbit most of that 370 MW overhead goes away as well. Sunlight is continuous, and the heat leaves through radiators. 4) On our Special View assumptions, year 4 is 200 tons at 100 kW per ton, which is 20 MW on one flight. Five hundred flights is 10 GW. Year 5 is still 20 MW a flight. Five thousand flights is 100 GW. The tons and the kilowatts stay the same. The flight count is what changes. Flight 14 showed Starship can reach orbit and deliver cargo. The 10 GW and the 100 GW still depend on how fast SpaceX can fly it again, and at what price.
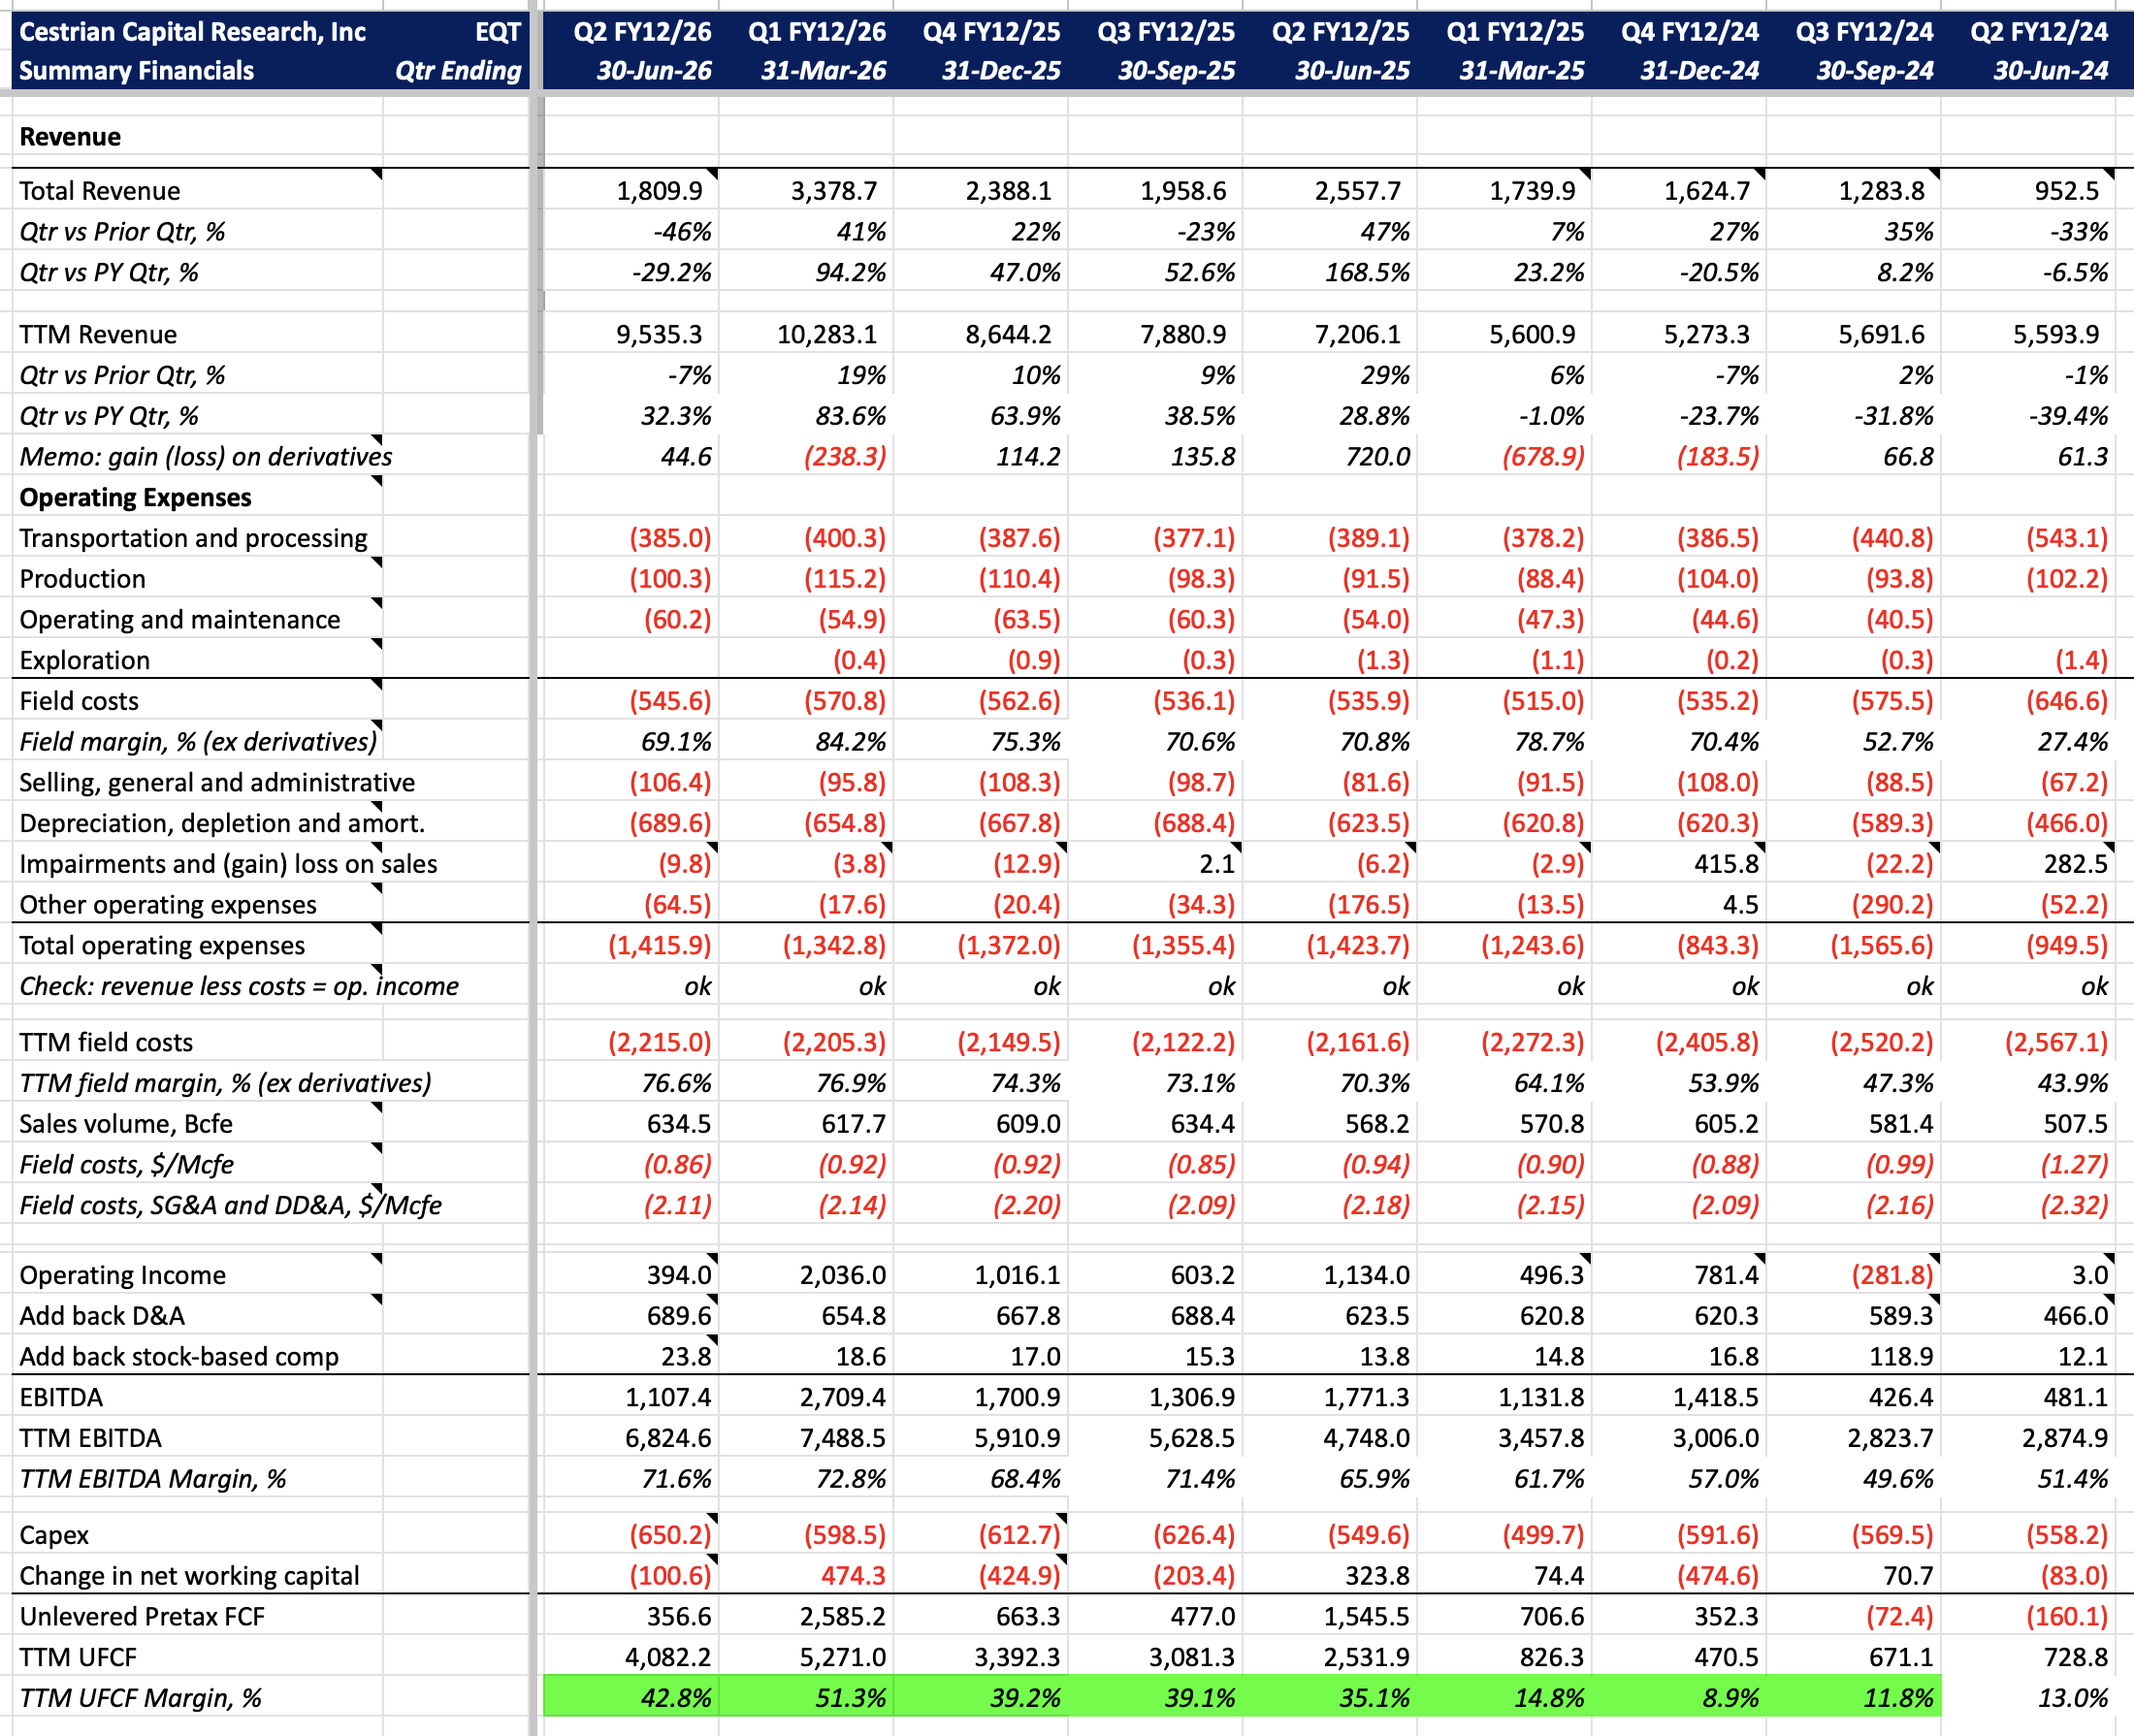
EQT remains tied to roughly $3 Henry Hub gas despite European prices near $23 per MMBtu, with US LNG export capacity limiting overseas…
@SilverBacked737 I have such a small $AMC short I look forward to MOASS. I will get to short more...
@AMCOracle @DrVonGobbler @JIMEDWA79881573 You do not need any valid points to buy more $AMC. Hop to it. The chance to buy at this price is temporary.

$LOGC victory lap...2x in ~15 mo. More room to run as they continue to buy highly-moated assets w/pricing power and pay no tax for decades due to the NOLs. 10+ year compounder. David Abrams agrees. Stock will probably fade some post the rights ($9 rights). ~25x '27 FCF today

Someone really should investigate the price action into some of these ancillary biotech stocks.....very reminiscent of a certain Situational Awareness with chip stocks earlier in the year. No one is filing ownership and yet these stocks push higher regardless of macro, or geopolitical news or the overall index moves. Someone with swaps? or options likely at play then using the momentum pf retail and algos to add to the bid. The trade is melting up perfectly to the end of the quarter (not surprised to see them even more aggressively up today than usual to mark performance). We saw this with the chips trade after an unprecedented April-June. But some of the moves with this trade exceed that euphoria (Look at $TXG, $TWST, $SDGR, $RGEN, $GRAL, and a host of other companies)........DO we see the similar move after a giant quarter with a reversal to kick of the next quarter, that was the fate with chips and caused the fund to blow up. Be interesting to see if they learned any lessons, Im guessing not based on recent performance, and if it is a different player the strategy looks the same. These companies need financing and should hit the market bid which is what set off Viacom and was the undoing of Bill Huang in 2021. Lets see, but a basket of these stocks looks interesting at current levels sometime today for gravity/secondaries to come early in Q4
Institutional money is now coming to the card market. How much cards do you think Coinbase and all of the institutional pigs need to buy to create this demand? There is a reason why Ryan Cohen is buying $GME in the open market in size. Card prices about to go limit up.
@InsiderHawk Why is $SYK selling off?

No one earned this drawdown more than the growth-at-any-price bros paying >100x trailing P/E for $FICO at the 2024 high...with revenue at record levels and net margins having expanded from ~LDD% to ~30% in just six years. If you're even slightly off on any of the ambitious assumptions you must have been making around market position, pricing-driven growth, or the exit multiple, you lose A LOT of money. That said, if there’s a definition of a business worth paying up for, FICO is probably it. Or was... interpreting what the recent changes to the mortgage-scoring landscape mean is no small feat for a tourist like me.

$CBNK merging into $PEBO
Microsoft plans to rebuild Xbox after FY2026 through studio cuts, higher hardware prices, Game Pass growth, exclusive releases and the 2028…
 Khaveen Investments 2 clicks
TIM Brazil $TIMS3.BZ / $TIMB will be buying back ~55m shares over the next 18 months. Not a huge buyback (2.3% of s/o), but this one is notable because s/o have been roughly stable since, what, 2014? Also, the stock is down 40% from ATH over the past few months while TIM keeps growing. We saw something very similar in 2024 (the price action, not the buyback), with the shares moving +100% the following year.
I am fascinated by $FICO. So many people have been blown out by it. Many on X have given up and said it’s going much lower. I haven’t done enough work to even tell you if it’s a buy or not. I just love following these beaten down names. Many once compounders are getting killed now. Building a watch list of compounder names that are getting killed to see what ones are best to own.
$ALTO StoneX initiates with a Buy rating and $7 price target:

$CALM down ~8% pre-market on 1Q27 results Likely another few quarters til cycle turn (?), balance sheet still rock solid, minimal buybacks, dividend is variable so no payout when losing money $55/sh BV (~$50 TBV) vs. $63 pre-market = 1.15x P/B
Aterio flagging that they see a material risk that $ORCL misses their 2H 2027 delivery guidance on their 1.3 GW Wisco datacenter, with meaningful load now unlikely before mid-2028
$PBI
Stratus Properties liquidates Austin real estate below projected distributions, while Atlantic Lithium and Intermex await approvals for…
Beyond Meat’s Q2 2026 revenue fell 8.2% as U.S. retail and foodservice volumes declined, while a flatter, not inverted, Treasury curve…
And here's another CVR from $SSTI buyout... Stock trading at $8.20 with $8 cash + $3 CVR
I’m not saying I think $AAPL is worth 35x earnings but I do think Ternus is going to go on a generational heater. Hardware guy that wants more product releases and wants to cut fat
Amazon expects $220 billion of capex against over $25 billion of AWS AI ARR, with Anthropic and OpenAI projected to supply 73% of AI…
 Deep Value Investing
POSCO Holdings trades at a 78.6% P/B discount as lithium, gas and trading profits reshape the steelmaker, while capex and lithium prices…
 Capital Connoisseur
Sezzle reports subscribers up 76.4%, transactions up 32% and quarterly GMV up 38%, with expanding margins supporting improved profitability…
 The J Thesis
Judging Tower Semiconductor ($TSEM) by how advanced its chip process is misses what its chips are for. Skeptics often set Tower's older 65 nm process against the more advanced processes at TSMC ($TSM). That yardstick suits logic chips, which are judged on transistor density. It does not suit the analog chips Tower makes for optics. 1. In an optical engine, the analog front-end is the circuitry that drives the laser and reads the returning light. It needs speed, linearity and power efficiency, not maximum transistor density. 2. Tower's strength is its silicon-germanium BiCMOS processes. They have long dominated the merchant market for these laser-driver and receiver chips because they deliver high performance without the most advanced CMOS logic. 3. A less noticed strength is hybrid bonding. Co-packaged optics needs an electronic chip bonded reliably onto a photonic one. Tower already runs mature, high-yield hybrid bonding for stacked image sensors in high-end phones, where a signal-processing chip is bonded onto a light-sensing chip. A close technical parallel, already at volume. The limit: if the electronic chip has to take on more complex signal processing, such as clock recovery or adaptive equalization, TSMC's advanced FinFET processes do offer real advantages in power and integration. Different foundries may end up making different parts of the system. So Tower's position in optics rests on silicon-germanium and photonic process expertise, not on advanced logic.
$LFCR finally getting bought out... $6.28 cash + CVR with potential for another $3.39 per share based on post-close revenue performance Stock trading around $6.60 so paying ~30c for the optionality today
Since multiple people have pinged me this. Cancun is not Tulum. They are 100km apart. The prior socialist government built the Tulum airport in part to screw with us $ASR Cancun concession holders. We want Tulum to fail. Cancun hotel occupancy remains in the mid-50s.
Research Roundup covers AAON's data-center cooling ramp, Knife River's margin recovery, ChronoScale's Microsoft-backed neocloud buildout…
Annaly Capital Management’s rate swaps and MBS expansion lifted earnings available for distribution 28% year over year, supporting its…
 Andres Veurink
Sezzle’s Q2 revenue rose 51.7% as subscribers grew 76.4%, while SezzleCash and Sezzle Send add growth potential and greater underwriting…
 Investor Overview
@alexandr_wang This kids meme game is strong. Might have to look at $META from a special situations angle now.
Victory Capital’s First Eagle acquisition is expected to lift 2027 EPS 35%, taking pro forma AUM to $570 billion and annual revenue to $3.2…
 Sorrento Research

Getting hard to justify $CSU.TO > $FIS ... Sure, culture and all that, but FIS sells the stickiest shit & has LT contracts, is (much) cheaper, has more torque (cheap leverage!) & ~organic growth ~the same
Obvious shitcos: $RR $ASPI $TMC $GLND $ALOY $EOSE
