
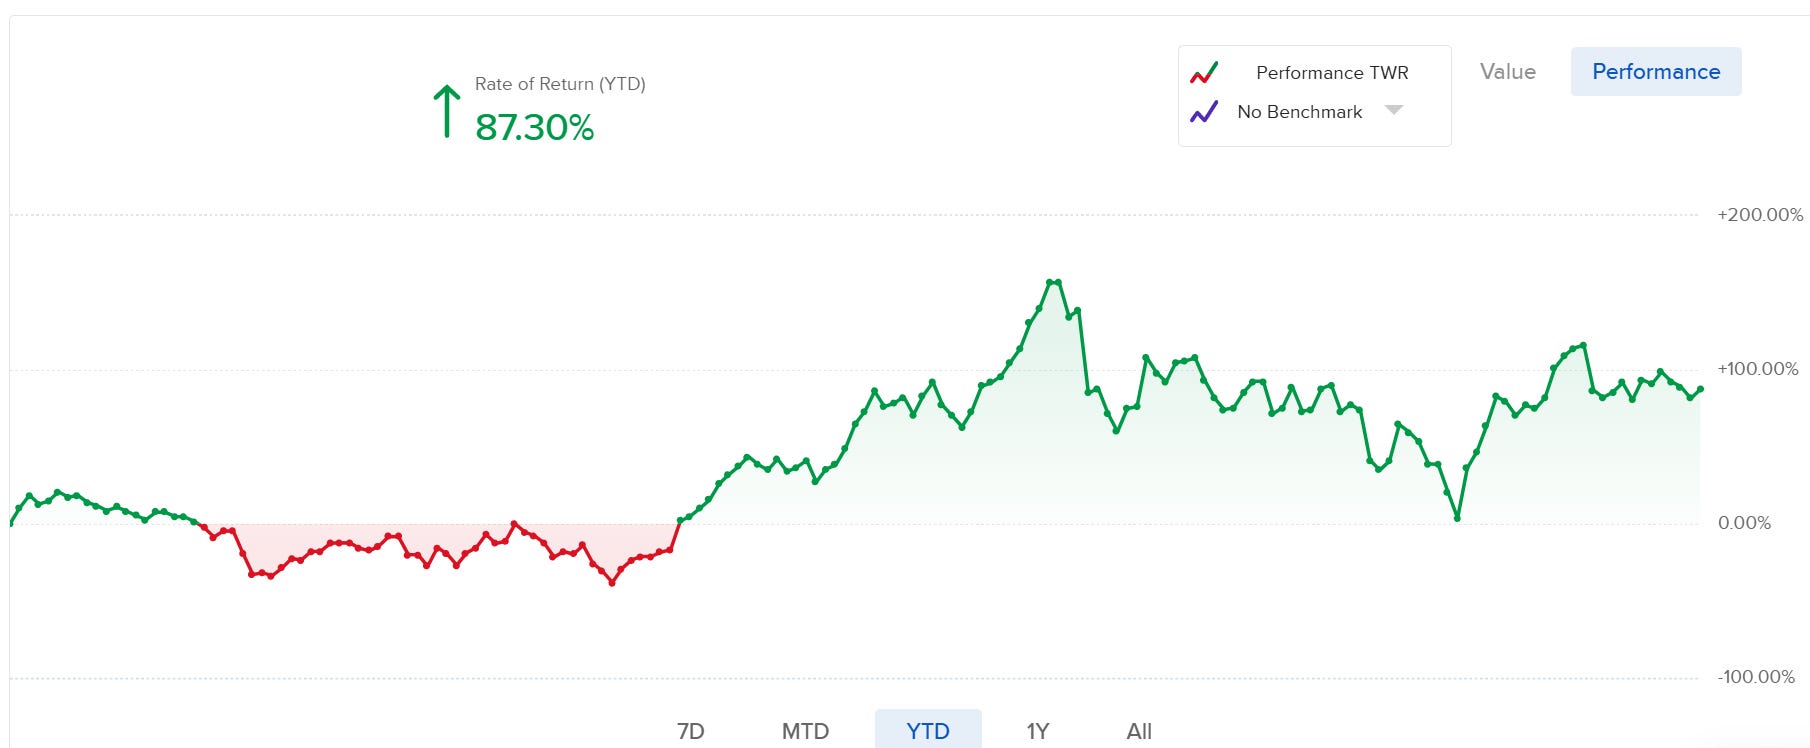
Bi-Weekly Portfolio update - End-August [15th to 31st August]
The portfolio allocates 75% to IBKR trading and 25% to an untouched Trading212 account, which holds SKHY, Micron and TSMC.
Thursday, September 3
Everything we published on this day.
77 stories — the front page that day →
The portfolio allocates 75% to IBKR trading and 25% to an untouched Trading212 account, which holds SKHY, Micron and TSMC.
Valuation firm finally appointed for $CPAC. This starts Holcim’s 60-business-day clock to launch the mandatory tender. Floor price firmly set at around $13/ADR, with some upside optionality from the independent valuation. https://t.co/hPCFKmYQvT
Yet another merger arb win for SSI. $LPSN played out just as predicted. Merger approved, closing tomorrow. Couldn’t have timed it much better. Nice +18% in just 3 days. Full pitch on SSI 👇 https://t.co/BxCJxOKcx7
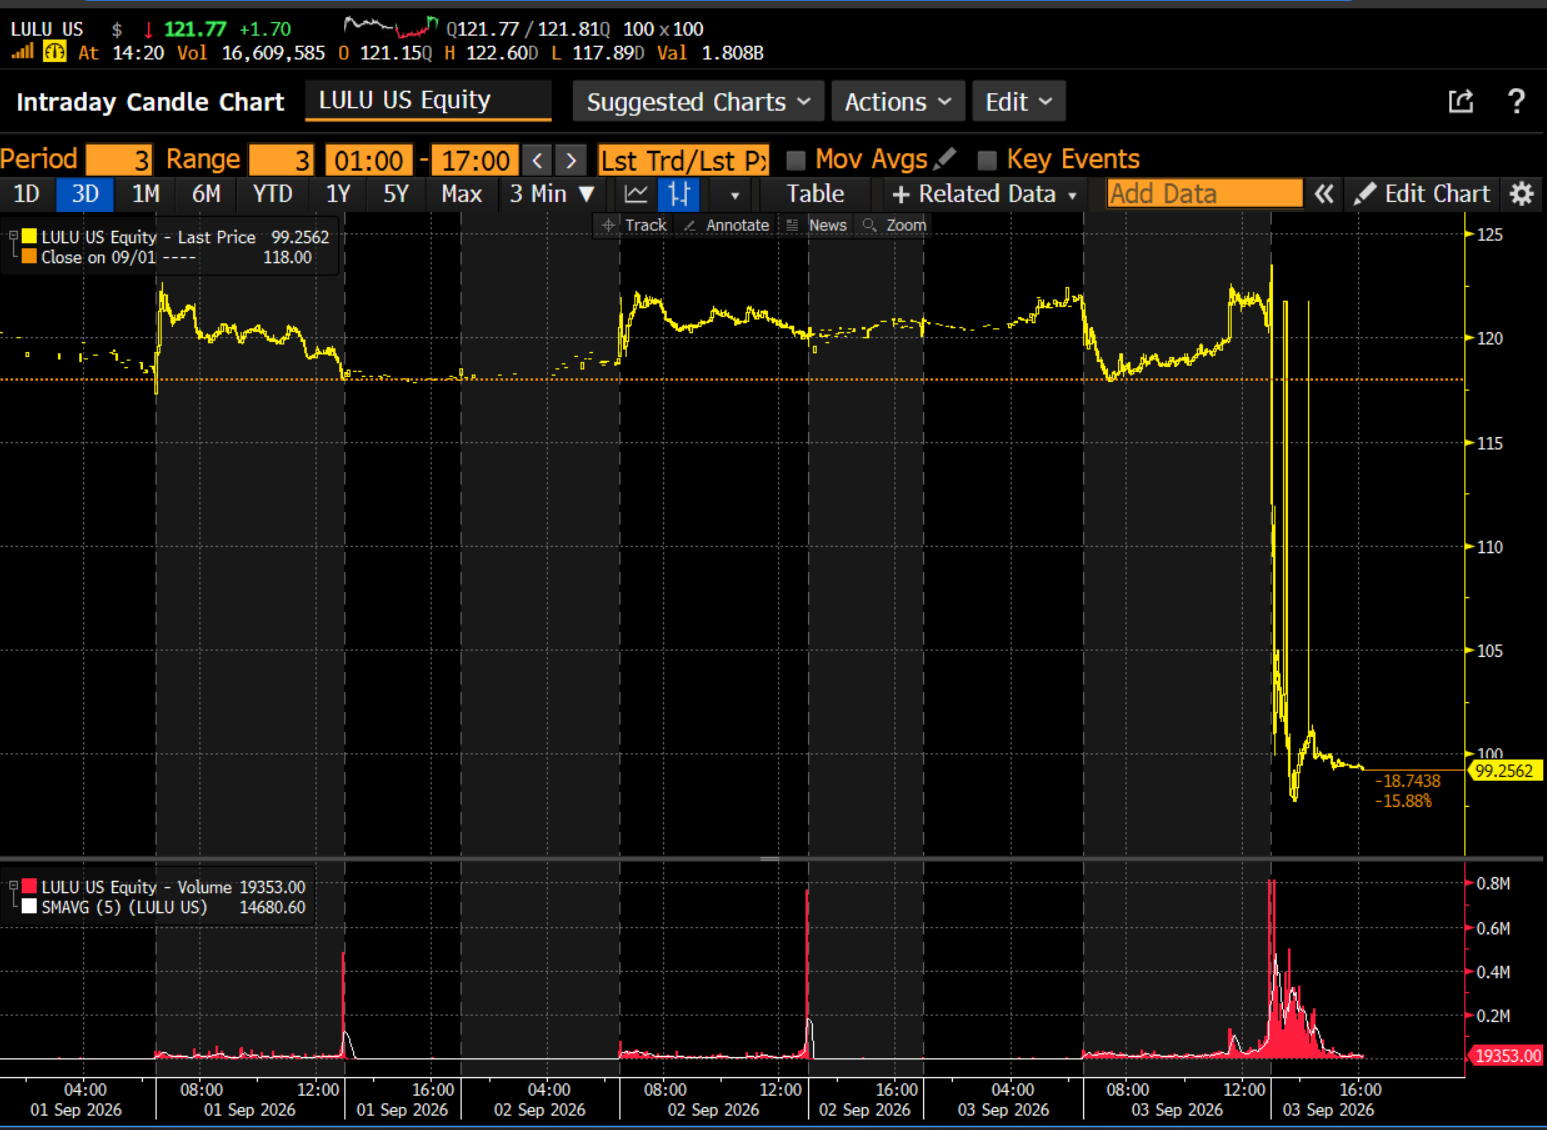
$LULU...what a joke. We've been short since $470. And anyone listening to #TheCall this week heard @KeithMcCullough and I going back and forth about how The Signal and the Fundamentals weakening were aligning in a way that got this stock on our Top 5 Most actionable shorts earlier this week. #boom
Looks like Benchmark / StoneX agrees with our analysis. Not $VVV. Our SOTP on 2027 numbers gets us to nearly 40.00. Too cheap. $DRVN https://t.co/cA9wdjgNE1
$CCXI Jeff Bezos follows only 611 people, starts to follow Agility Robotics employee Probably nothing https://t.co/wQQ7G4Zp7L
Another consumer staples dividend cut... $CPB reducing dividend by 36% (CAG cut theirs in half) https://t.co/VVVvo0Gh8k
@kab604 $CALM is excellent at managing a (very) cyclical business
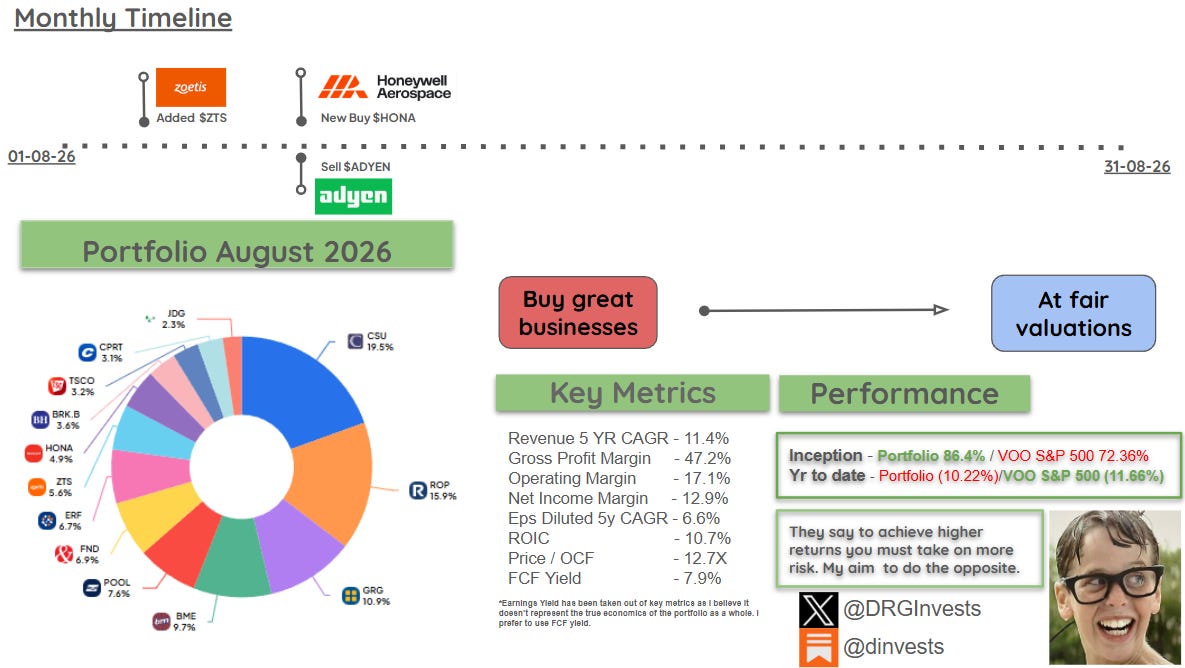
Portfolio update: Honeywell Aerospace was added after a 20% post-earnings drop, while vertical software remains over 35% of holdings amid…
Synopsys reported 8% EDA and 11% Design IP growth in Q3 2026, with Multiphysics Fusion expected to add revenue from fiscal 2027.
Tailored Brands’ bankruptcy erased an asset-backed small-cap thesis, while lululemon has become the portfolio’s largest and most…
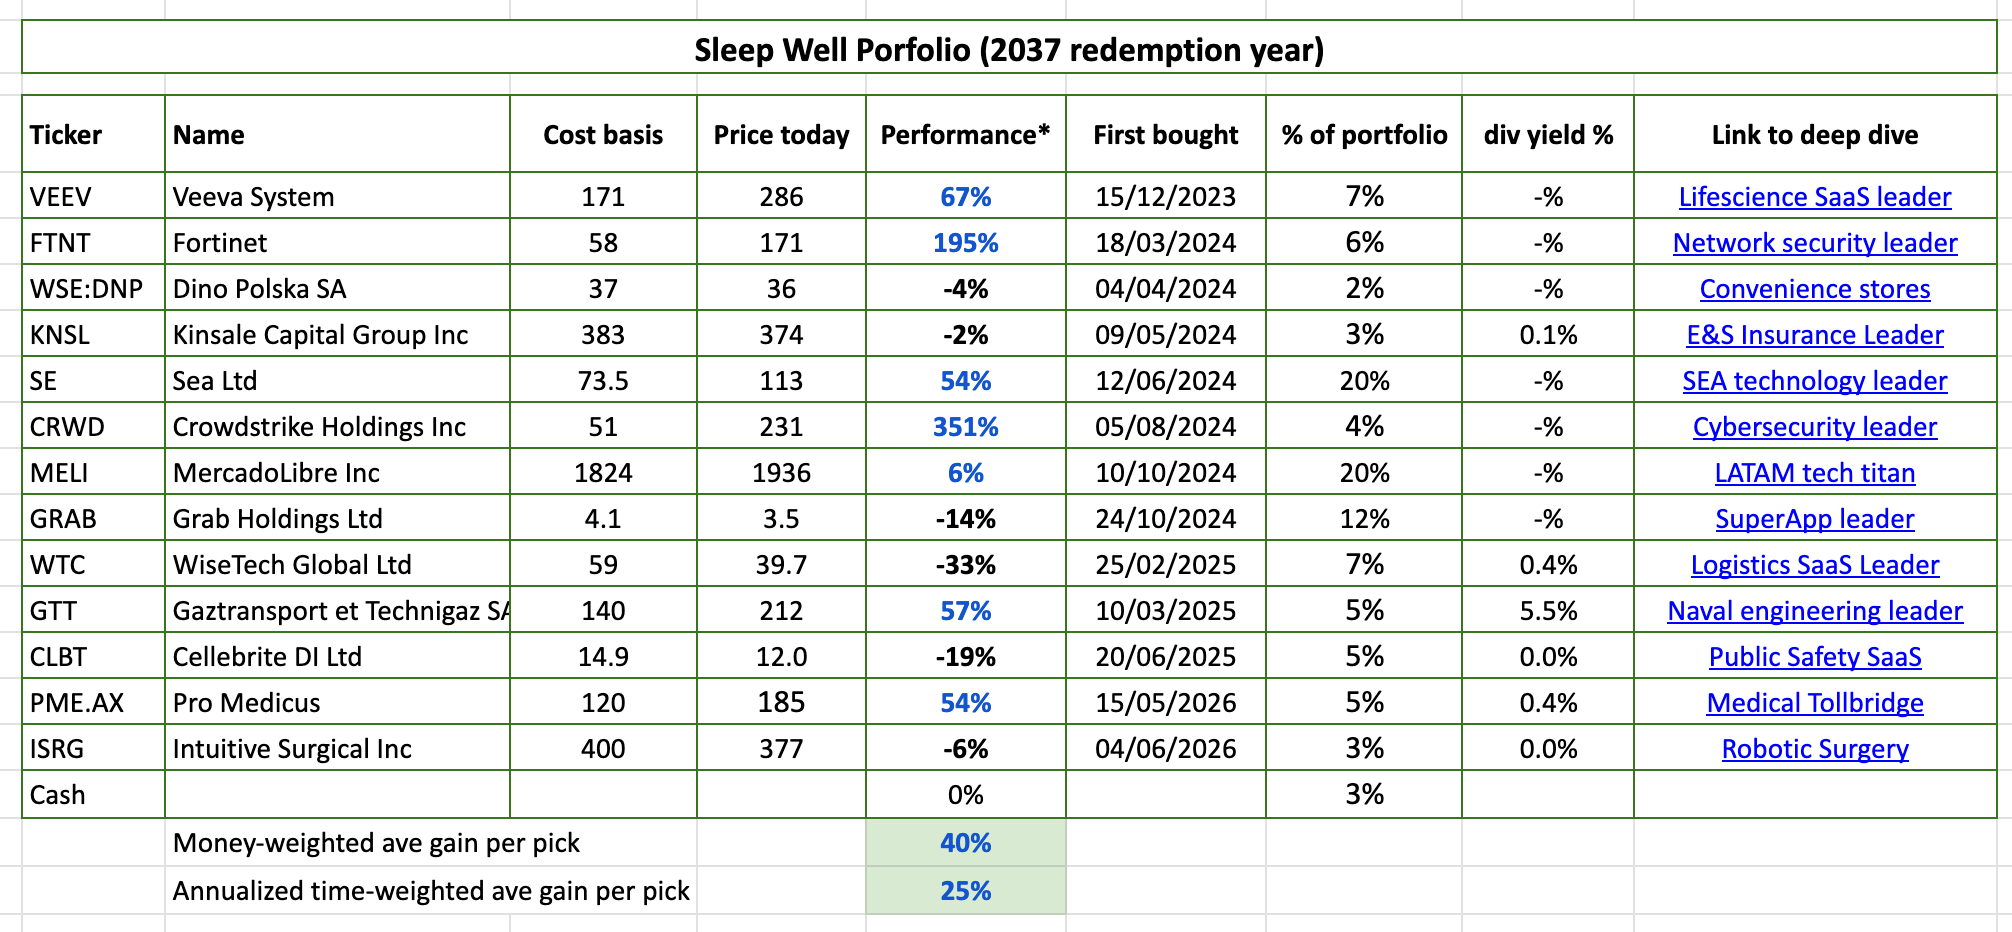
Sleep Well Portfolio’s August gains were led by Veeva, CrowdStrike and cybersecurity, while Cellebrite and WiseTech reported early AI…
Open weight model to Nvidia ls kerosene lamp to Standard Oil. Free access to models = more demand for underlying infra. What's better is $NVDA can make this Lamp tailored and optimized for Nvidia stack such that users have to pick: Free model + $NVDA stack or Expensive model + Non-NVDA stack. The question is more about if $NVDA can deliver frontier open weight models or not. I am still a bit skeptical about it because it takes an elite dedicated team to do that and $META learned that hard lesson. And it also requires visionary mgt directly leading the elite team which $GOOG and $MSFT failed, while $SPCX realized it and back up again.
Pondering how safe $PANW and other cyber incumbents really are if model labs keep expanding. Split security into two buckets. Bucket one: scanning and out-of-band work. Code and package vulns, cloud config checks via APIs, posture reports, “is this alert real?” These jobs are relatively checkable. Coding agents and Mythos-class models can do more of them over time — often with no endpoint agent or firewall in the path. That is where AppSec and vuln tools look exposed. Bucket two: live sensors and inline enforcement. See the process. See the packet. Allow or deny. Contain the machine. AI cannot do that from the outside by calling an API. Something still has to sit in the estate. That is much harder for a lab to recreate. So the interesting question is not “is cyber safe?” It is: how much of the franchise is bucket one, and how much is bucket two? PANW lives mostly in bucket two — plus deep SOC context. That looks safer than a pure scanner. Not untouchable. Just a different risk.
Our model is a tracker but ultimately a forward valuation model using $ B/GW. If, for example, $AMZN is expected to bring a total of 16 GW online by end of 2028, and then there is a delay of some sort and this has been publicly disclosed somewhere, our next weekly update will catch this and adjust the timeline. This would adjust AMZN's forward valuation from 2 to 3 years out.
Build-A-Bear Workshop, the toy retailer.
Special-situations survey profiles 31 activist, buyback, M&A and strategic-review cases, including Abercrombie, PagSeguro and Vodafone.

Leslie’s Q3 sales fell 8%, adjusted EBITDA dropped 32%, and withdrawn guidance left its 2028 term loan trading at 20 cents on the dollar.
$CPB is completely uninvestible for as long as Marc Lautenbach remains on the Board of Directors. Have been telling people this for over a year now... Just look at $PBI performance over his career and then from the moment he "left" the CEO position... https://t.co/Px6gacUNjZ
Chinese stockbrokers FUTU $FUTU and Up Fintech $TIGR are taking a beating after the Chinese securities regulator ordered all unauthorized Mainland accounts to be closed within 2 years, with only sell orders and fund withdrawals allowed. Both companies will be fined, but a rumored 1.85b CNY fine for FUTU is less than 2 months of profit. For FUTU, mainlanders are 13% of accounts but closer to 20% of total assets and revenue. FUTU's rapid growth in HK and SE Asia has diversified the business in recent years, and the loss of Chinese customers is less than 1 year's worth of customer growth outside China. What remains is a faster-growing, HK/SE Asia consumer play with no China risk, which probably trades at 8x P/E with net cash. That is, if this was the last shoe to drop and Mother China isn’t intent on ruining them.
Icon $ICLR finally published their restated financials. The revenue had been overstated by roughly 1% in 2024 and 2025. With shares up 40 percent since we added this name, we're declaring victory and will remove this from the monitor. We doubt AI will fully disrupt the others; this narrative will probably pressure the multiple going forward.
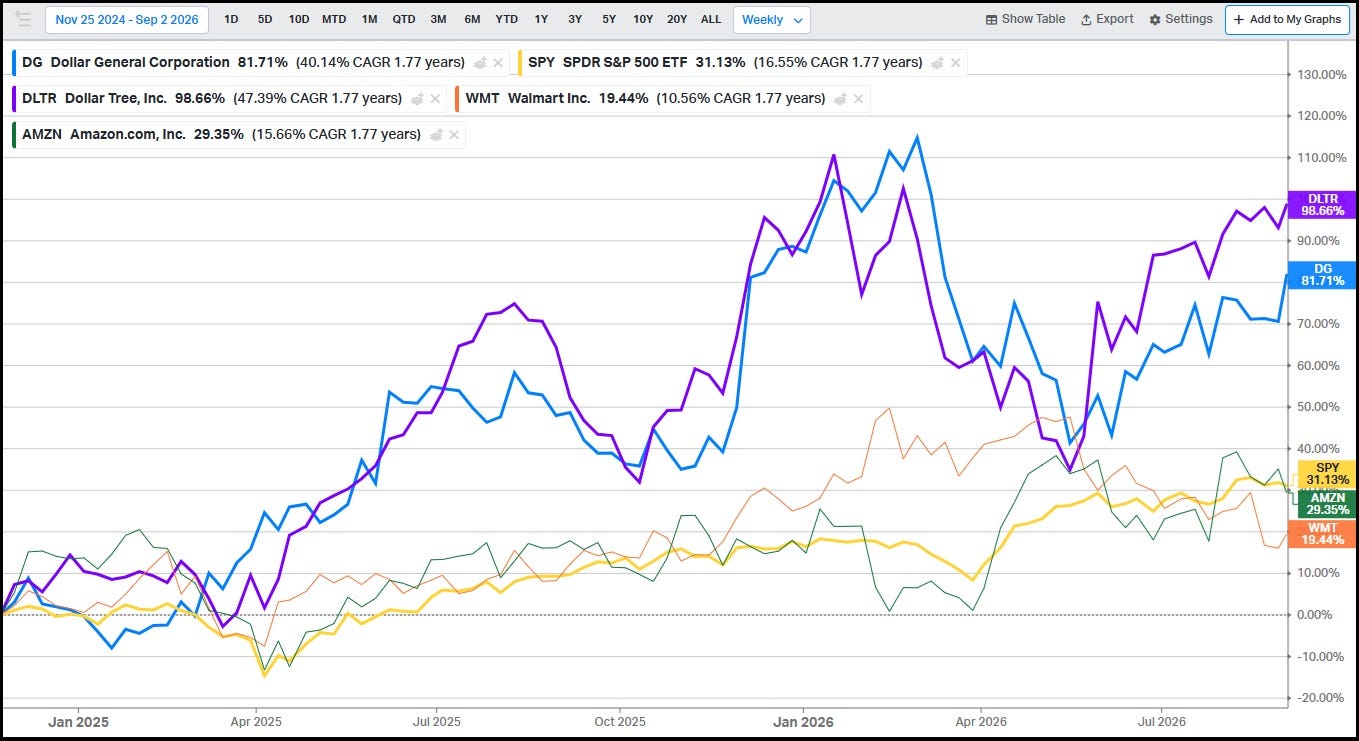
Dollar General’s Q2 FY26 comparable sales rose 3.5%, beating Walmart U.S.
@FloatCheck @CKCapitalxx I’m all for going big on a fashion trade when the brand is clearly benefiting from a shift in consumer behavior. But there was zero data pointing to that for $LULU this quarter. No clue what he thought he saw.
Dang I missed this one -- Nielsen CEO $NIQ almost bottom ticked it at $9 https://t.co/Zh7pIvOHua
Interesting follow up on this today: The SEC settled an enforcement action against $TBBK's now-retired CFO, fining him $30,000 for directing the company's 10-K to be filed when he knew the auditors hadn't yet signed off. https://t.co/9N28UhEMlw https://t.co/8yBRR6MC7Q https://t.co/1lPgtgKyWD
Anti Software trade. Short $OKTA and $TWLO. Both are up 80-120% this year. If software trends down they both will get crushed 30%.
$CRDO It’s pretty rare you find such a high moat business with massive growth that has been managed so well to keep extending their growth pathways. Three years ago they were just copper, now much more. The optics position: Credo isn’t just an AEC (copper) story anymore — they now own the full AI interconnect stack: • Optical DSPs (record Q1 revenue, 50G/100G-per-lane shipping now, 1.6T ramping later this FY) • ZeroFlap Optics • Silicon Photonics PICs (first revenue post-DustPhotonics deal) Management’s guiding >$600m in optical revenue for FY27 alone, with each of DSP/ZeroFlap/SiPho individually clearing $100m As AI clusters scale and speeds push past 800G toward 1.6T, connectivity becomes the bottleneck, everyone knows this. Credo sits at nearly every layer of that bottleneck, it’s been really thoughtful about product expansion so far. Management deserves more credit.
$CRDO Added back here. Trim in the high $200s. https://t.co/lcCN8KshU5
That's a pretty big sale in $VAL. I still own/like. https://t.co/DoHOmmsAtD
$IOT 13% after hours. Monster company firing on all cylinders https://t.co/Zfo3Wy7qxN
@MattJMcClintock Is it time to buy $AS @MattJMcClintock?????!
For basically the first time in my history I have positive beta to $BTC while it's rallying and it feels nice.
$ASAN down 12% on weak guidance. This earnings season has sucked so gotta enjoy my wins. https://t.co/wHULS7a1xW
IF YOU ALLOCATE CAPITAL PROCYCLICALLY, YOU SHOULDN'T RUN A YUUUUGELY CYCLICAL BUSINESS $BLDR - Can anyone name a good (counter-cyclical) mngmt team that isn't named Lundin? https://t.co/yHn2kFBkuP
@pradeeepk I think you wait until it shows up (even more!) in $BLDR's numbers and markets suddenly start worrying about leverage. Investores don't care about balance sheets until it's suddenly the only thing they care about, and that's when stuff really crash.
One of these don't act like the others. $FIS should fix their industry classification. But I guess it's a nice hedge to holding $CSU.🤪 https://t.co/ffxHQNx8jc
I wonder how much Karp is paying him. $AIG must be a massive account, and with Palantir trading at a quadzillion x rev, Zaffino must've created a ton of value for Karp. Zaffino stepping down as CEO of $AIG to be 'head of financial services', but I bet the pay is better?
Zaffino always seemed completely Palantir-pilled. Now we know why. Wonder if $AIG might get their expenses in order if new management (although handpicked by Zaffino...) take it easy with all their Palantir consultants https://t.co/bGgocKEd9v
$LULU comp sales fell 9% compared to last year. Jesus https://t.co/HkUK6ym4oR
$PYPL may have received a new takeover approach per Betaville https://t.co/6Xvh1uA9hG
Where were the signs $LULU https://t.co/B1RLkiGdlH
$LULU Hilariously bad guide -15% AH "For Q3 of 2026, the Company expects net revenue to be in the range of $2.290 billion to $2.320 billion, representing a decline of 10% to 11%."
*CPB: SNACK CONSUMPTION TRENDS NOT WHERE THEY NEED TO BE *CPB: 1Q FY27 GOING TO BE A VERY CHALLENGING QUARTER FOR SNACKS Ozempic is wild. $CPB down 10% on the day, and down over 60% since the 2023 high https://t.co/JR6WmAFjCt
I did an article on SharkNina $SN September 5, 2023, shortly after the very unusual (split from a non-US company) spinoff. https://t.co/7JoGbrRP70 No paywall https://t.co/9XSWVQpqv4
Summit Therapeutics needs HARMONi-3 and Western-subgroup data to validate China-based ivonescimab results, while $690.7 million in Q2 cash…
 Stephen Ayers 8 clicks
Wall Street hates $LULU. Twitter hates it. Should I buy it or for shits and giggles or just throw myself into traffic? https://t.co/PzqJvBv2UK
spent a couple hrs this wk on $LULU research, as i do with numerous retailers during back to school and holiday season. lots of conflicting data and a tough setup to handicap going into the report. often the best trade is the one you don’t make. https://t.co/z3xvfjOsRE
CME perpetual-futures activity is tested against more than 240,000 CFTC data points on open interest and dealer positioning.
$OXM getting "LULUed" after hours following a huge guide lower. Apparently people are tired of the floral prints at Lily Pulitzer. Less bright colors they said. Tepid demand for $150 quarter zips at #southerntide isn't helping matters either. The market seems to think that $0.70 quarterly dividend is at HUGE risk. No position.
@LatamData Medellín will keep taking relative share from Bogota. Underappreciated driver for $asr
@AltaFoxCapital @DeepSailCapital $SNAP
@burningbushcap $CIB is a quarter of the Colombia ETF, $AVAL is 4%. Need folks to go stock-picking in individual names, right now, people are mostly buying the index.
@dirtcheapstocks I look for companies like this for my inflation basket. $INFL seems pretty good to me for a lazy version. https://t.co/OkhW0QroSL
@SkillJoy_00 how many GTA VI launch month, quarter, yr 1 units and what eventual online ARPU do you think the market is currently pricing in to $TTWO ? And how does your analysis differ from those expectations?
Broadcom's custom ASICs, co-packaged optics and Ethernet switches position AVGO as an AI hardware alternative alongside Nvidia, with…
 Carla Magliocco 7 clicks
Intuit targets 9.1% FY2027 revenue growth and 23% EPS growth after Q4 revenue rose 13.7%, supported by Global Business Solutions, Credit…
 Treading Softly 5 clicks
Broadcom targets $115 billion of AI revenue by 2027 and more than $30 in fiscal 2028 EPS after Q3 AI semiconductor revenue rose 221% year…
 Steven Fiorillo 8 clicks
@GrumpierBTDay @FrontRangeHQ @maxwellhouse99 Have you tried "$CRCL min_faves:1 -filter:mentions -filter:hashtags" ?
@treygurr also said the move was to go all in on $HOOD the second crypto showed life
@StockJabber @hntrbrkmedia I saw your email on for-profit education names that could be exposed to AI. We have written extensively on the bear case for $LOPE $CVSA $STRA $PRDO and others. AI is only ONE OF MANY ISSUES the industry now faces, in my view.
Me buying $HOG at $18 because Wall Street said it was going to zero. https://t.co/nGdqlBiwY2
$DLTH is a perfect case study on where AI & stock screeners might get tripped up and on why doing the manual work still matters. Even though the headline acknowledges a large tariff refund, adjusted EPS does not “adjust.” Adjusted EPS is 6c, not 50c! Source: @InfoArbMonitor https://t.co/RBcbuTAHmX
"But my quarterly deceleration" the Wall Street idiot cries out as his wife leaves him for a cashier at the local grocery store. $EVC https://t.co/9Z5qvFrCCh
NIO beat Q2 expectations as delivery growth and higher ES8 and ES9 vehicle margins narrowed losses. Its shares trade at 0.35 times revenue.
 The Asian Investor 3 clicks
@dbcthomas2 I'm long $CLSE which is similar. https://t.co/cyhmEYEZeW
Mosaic’s potash business remains profitable, but negative phosphate margins, elevated sulfur and ammonia costs, and negative free cash flow…
 DCF Value Investor 3 clicks
$DLTH Duluth report better than I expected, but mostly tariff refunds. - Net income of $18.4 million compared to net income of $1.3 million last year. This year includes $16.3 million in tariff refunds. - Inventory down $22.9 million or 15.5% vs. last year - Net sales decreased by 7.8% to $121.4 million
$ADMQ new orders for this nanocap (mkt cap 6.55m) https://t.co/67gBW9Me5k
Expand Energy’s hedge book and Twin Eagle acquisition support free cash flow through weak gas prices, while LNG export growth could lift…
 Elliott Gue 4 clicks
MiniMed Group's pumps, sensors and dosing algorithm expand recurring CGM and consumables revenue as separation costs roll off and cash flow…
 Myriam Alvarez 1 click
Chewy's Q2 hinges on stabilizing sales, active-customer growth and NSPAC after its forward EBITDA multiple fell from roughly 24x to 10.8x.
 Bernard Zambonin 1 click
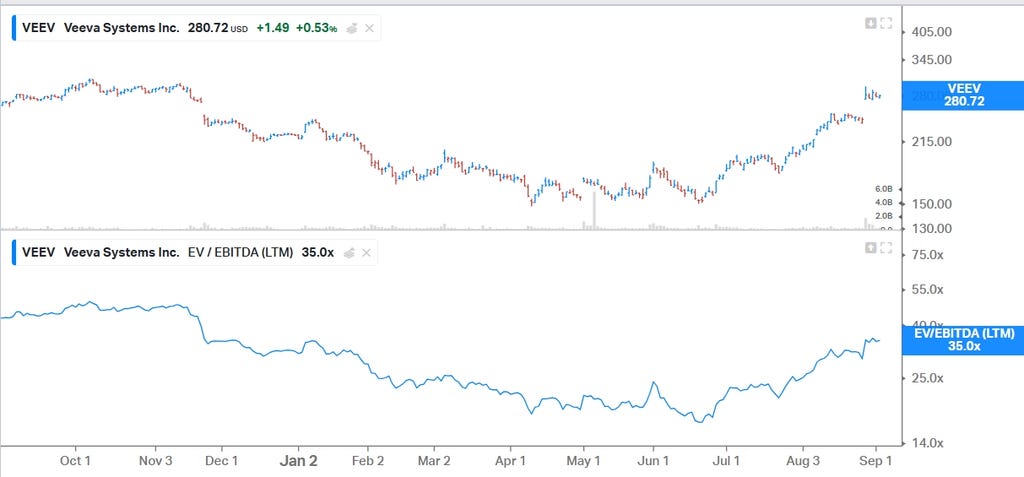
Veeva targets CRM share gains from Salesforce migration delays while Falcon agentic labor expands its reach into life-sciences safety,…
Edison International faces Eaton Fire litigation, but a $1 billion customer-funded pool and the California Wildfire Fund support its…
 Power Hedge
If we go above $2-3 in $GPRO today I will be very tempted to sell '28 calls
Happy $JCAP dividend day for those who celebrate https://t.co/8yZPuQp8R4
$GPRK GeoPark breaking out after news it is expanding into Venezuela. Sin of omission for me: I sold my position in 2025 and never re-entered. https://t.co/aR4XtkYvHX
Netflix targets $51–51.4 billion of 2026 revenue, $3 billion of advertising revenue and $12.5 billion of free cash flow as its second…
 The Curious Analyst 2 clicks
