

Nvidia (NASDAQ: NVDA) Q2 Earnings Review - Rating, Hold; PT $260, Stretch $300, Stp<$189
Nvidia posted $96.2 billion in Q2 revenue, up 106%, and guided Q3 revenue to $108 billion. The review rates NVDA Hold with a $260 target.
NASDAQ
NVDA
251 stories
$4.6T Market cap · 2026-11-06
Get NVDA news in Claude, ChatGPT or your own code. See plans
Nvidia posted $96.2 billion in Q2 revenue, up 106%, and guided Q3 revenue to $108 billion. The review rates NVDA Hold with a $260 target.
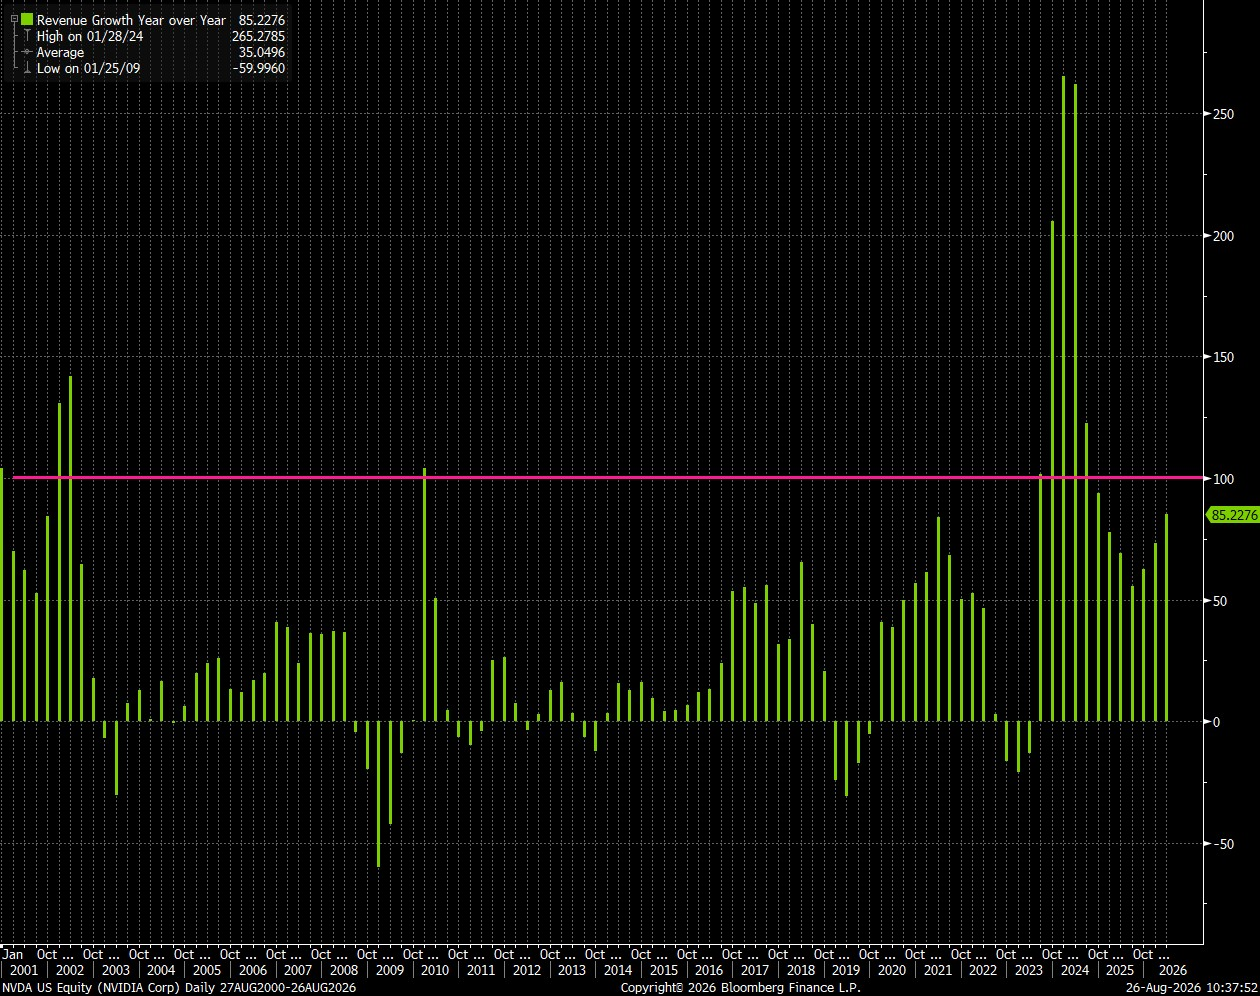
Nvidia features in the August 26, 2026 Trading Post.
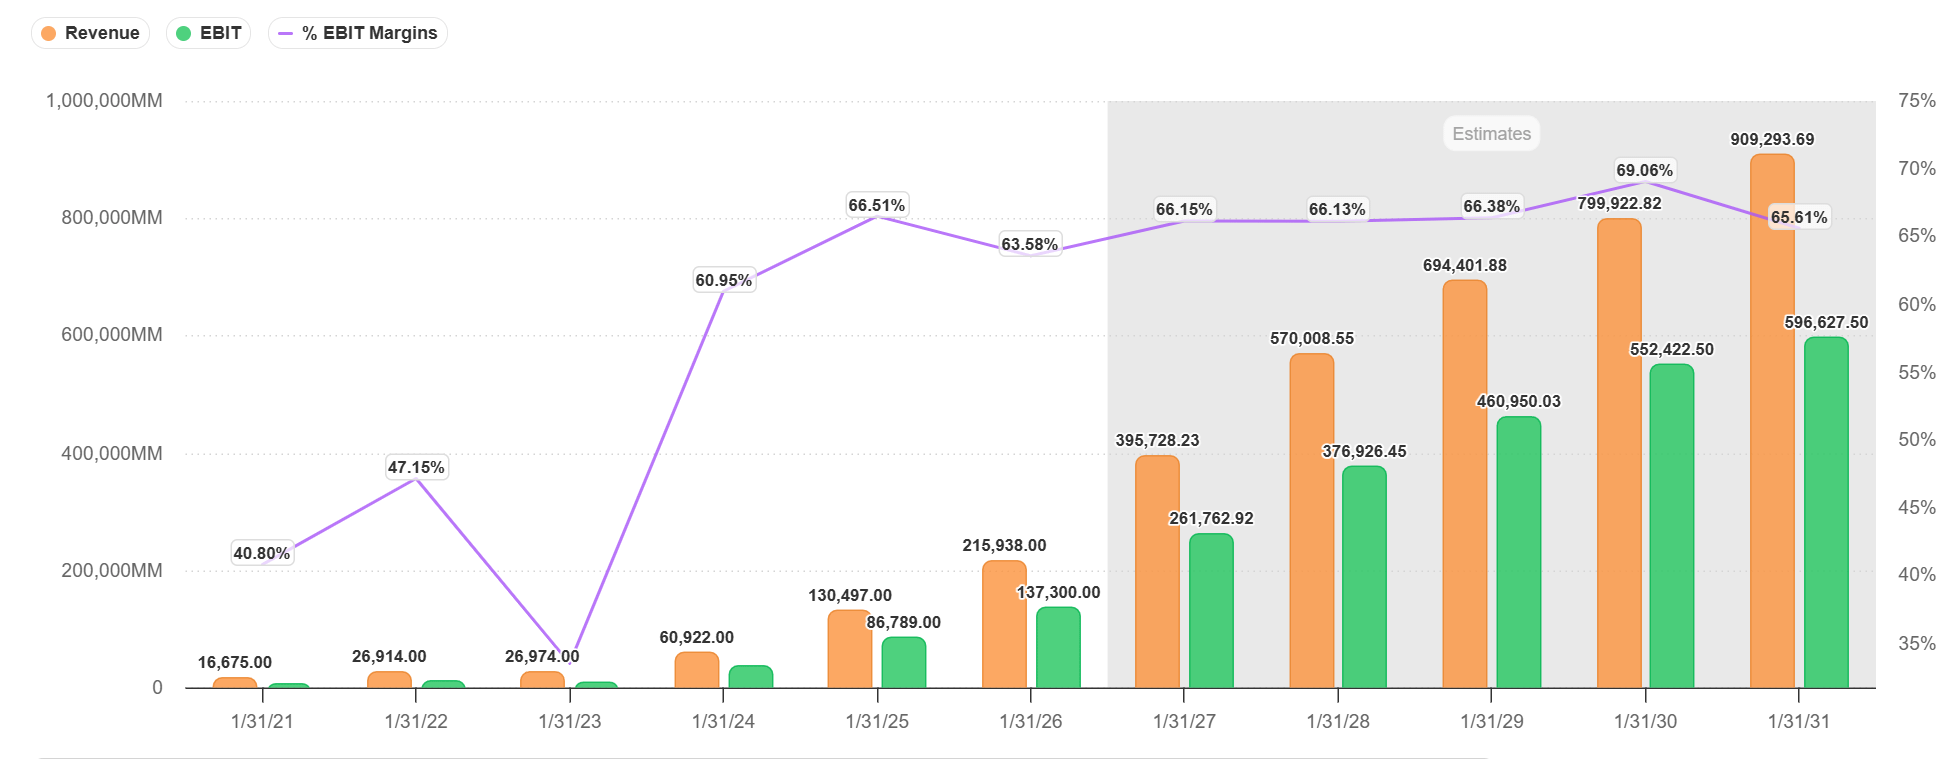
Nvidia faces questions over the durability of its long-term profit margins ahead of earnings.
@sp3cul8r No. Been a bit since I’ve thought deeply about the short-term risk/reward on $NVDA.
Too many of you are revving up to make an outsized bet on $NVDA earnings based mostly on vibes. Conviction without an information edge is just confidence dressed up as research.
Cerebras is a taxi. NVIDIA runs the buses. Almost every confusion about $CBRS begins with reviewing the wrong vehicle. We just published Part 1 of our Cerebras deep dive: → Why wafer-scale SRAM excels at low-batch decode → Why $NVDA becomes the cheaper token factory at high concurrency → Why Cerebras was built for training—but found its future in inference → Why the two architectures are increasingly complementary, not substitutes Our conclusion: Cerebras is mostly a buy over the next 2–3 years—but demand for premium-speed inference will decide the case. The full high-level report is live. 👇
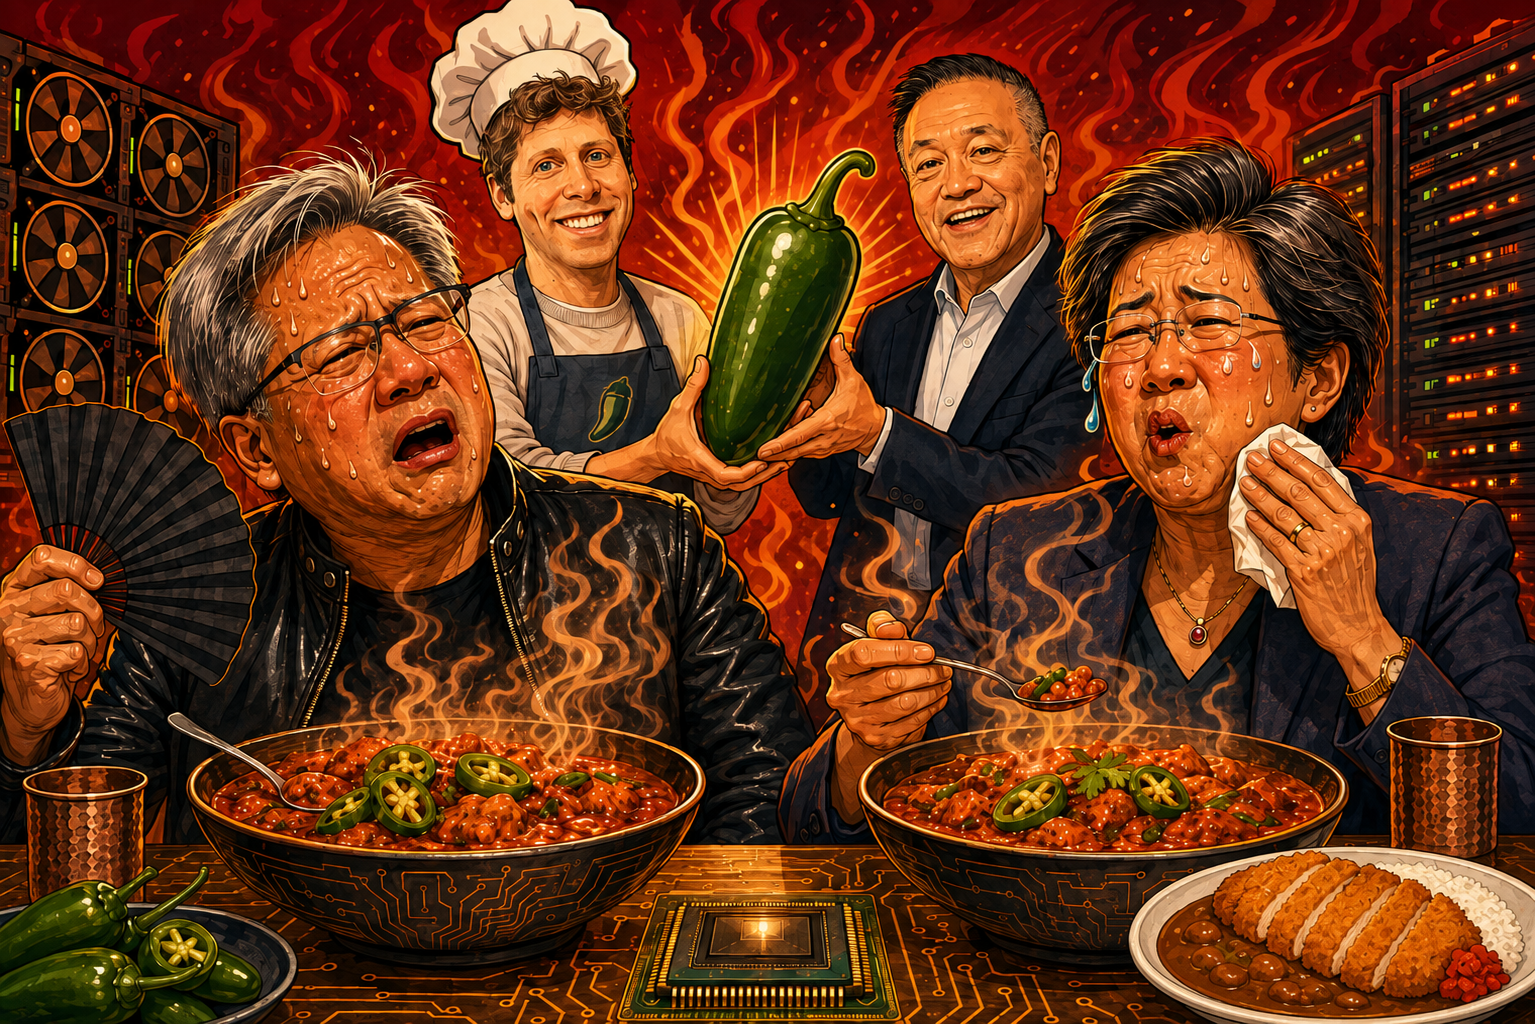
OpenAI’s Jalapeño inference ASIC beat Nvidia Blackwell on claimed performance per watt in InferenceX tests, using HBM4 and a…
Nvidia reports Q2 2027 earnings August 26, with data-center backlogs, enterprise AI inference demand and Vera Rubin volume sales expected…
still feel the rotation from July-current is more about a short squeeze (the opposite end of the Situational Awareness portfolio) and the dispersion of having to unwind the long semi trade portion. But that rubber band is similarly stretched as it was the opposite direction at the end of June. Still feel its in the process of reversing (even the morning action today looks like a top could set in?) $RNG, $IT, $APPN, $TGT, $EXPE, $FDS, $PAYC, $ELF, $MET, $MFC, $GDDY, $V, and many more that were AI losers that have had incredible runs in the past 4-6 weeks seem like good ways to be short against a snap back to AI or a more seasonal unwind from policy risk trying to control rates, midterm/fall seasonal factors, etc. Especially with SaaS earnings taking the stage later this week and next (overshadowed by $NVDA on Wednesday)
AgentX 1.0 open-sources a 1 million-context agentic coding benchmark, testing Nvidia and AMD inference hardware on multi-turn production…
@Cashflowfarming * $NVDA’s competitors are doing the same with their balance sheets, not customers.
Jensen is clearly very smart, and I think he was wise to seed the neocloud industry ($NVDA customers) to help offset the dominance of the hyperscalers (ASIC customers). But that doesn’t change the competitive reality that he has to use $NVDA’s balance sheet to buy business… (and his customers are doing the same with their balance sheets)
 NVDA 2026-08-22
Nvidia’s exclusive SpaceX partnership targets a 10 GW data-center buildout and could add $120 billion to $230 billion of revenue beyond…
 Uttam Dey 2 clicks
It is simple: $NVDA is using vendor financing to avert margin pressure and market-share loss.
Intel's silicon photonics CPO work shows precise 16-wavelength lasers but suffers SOA four-wave-mixing noise and weaker link performance…
I think what this guy @dylan522p does not understand is that receiving semianalysis institutional is just an information edge right now. Funds know they can short on publication and know they can cover lower- easy His negative pieces have been proven wrong more often than not, and when they’re right, the stories are often less material than stock moves on day of publication But he probably feels untouchable when he can take tens of billions off company values now, so he’s gonna typically act like a dick- but this type of edge rarely lasts long (and it won’t here) $AVGO $AMD $MU $NVDA
“Just buy $NVDA and let Jensen allocate”
Nvidia GPU rental prices are rising across generations, supporting a $500 billion push to finance AI compute as a durable, rentable asset…

GPUs retain an edge in AI training, while custom ASICs target predictable inference workloads with better power efficiency and cost per…

Nvidia, Broadcom and OCP APAC speakers debate copper interconnects, optics and emerging alternatives for scaling AI data-center networks.
Just as Lucent and Alcatel did, $NVDA is providing enormous vendor financing, thus in part the argument as to why it is a “synthetic” neocloud hyperscaler. $NVDA is on the hook if the neoclouds stop paying. I think there are great similarities between the neocloud boom and the CLEC buildout. And I think there is great risk of DWDM-like innovation (which is what killed the fiber industry) in LLMs, memory, et al. Finally, some investors whine about $NVDA’s “low multiple.” That’s what happens when you lend money to your customers to prop up pricing power and stem market share loses to ASICs. You can’t have your cake and eat it too.
Nvidia is building a synthetic hyperscaler around neocloud partners, GPU fleet software and financing as AI workloads strain traditional…
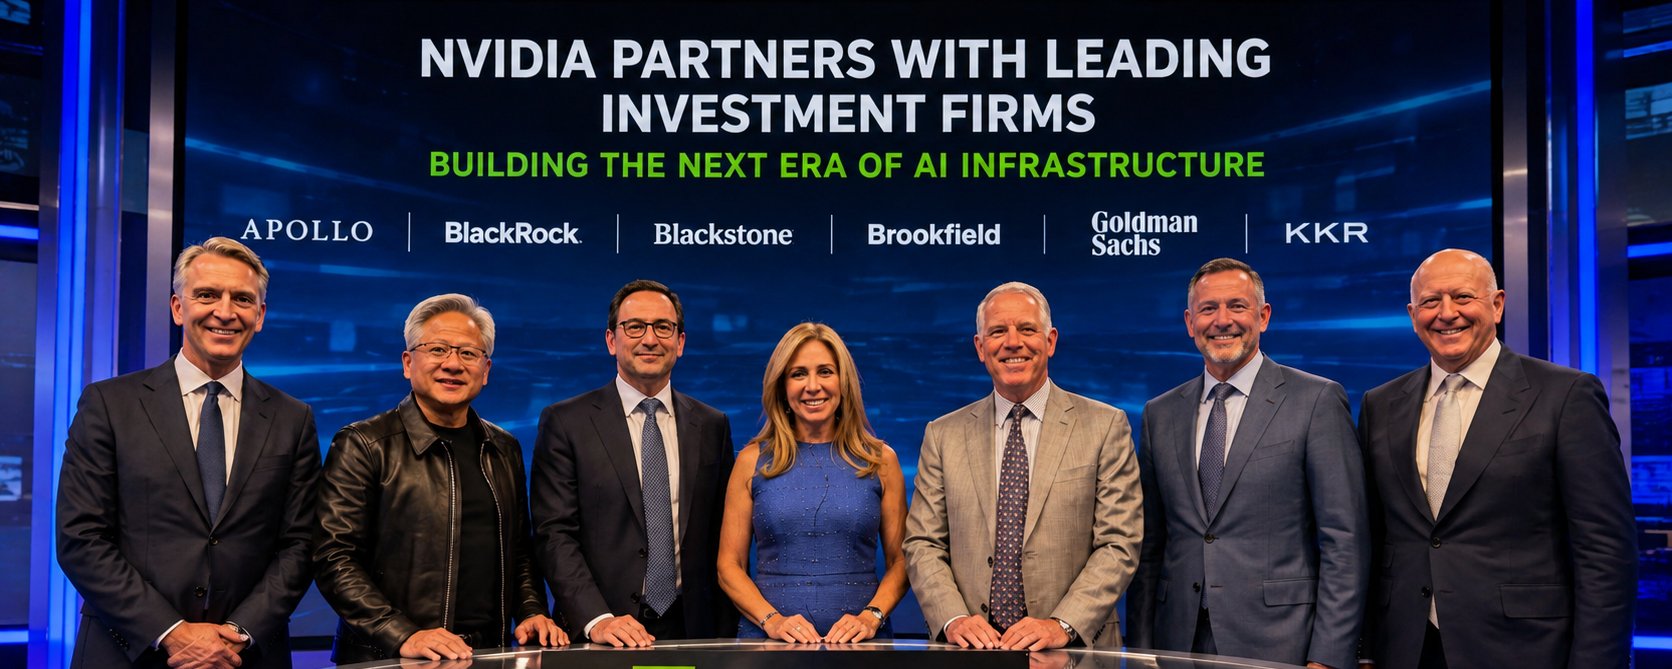
Nvidia has partnered with Apollo, BlackRock and four other firms to raise over $500 billion for AI compute infrastructure, while limiting…
@JonathanSeller Didn’t miss it, very much long $NVDA
Letters that discuss NVDA.
Companies the stories above are also about, besides NVDA.


