
Dalius - Special Sits on X
I really want to be wrong on $LSTA this time around. It’ll be pretty bad for retail shareholders if, by the end of the day, the offer still hasn’t been lobbed. https://t.co/k99Zo100XP
Monday, August 31
Everything we published on this day.
65 stories — the front page that day →
I really want to be wrong on $LSTA this time around. It’ll be pretty bad for retail shareholders if, by the end of the day, the offer still hasn’t been lobbed. https://t.co/k99Zo100XP
$CPAC is +16% since the SSI write-up, and the key tender-price ambiguity is finally resolved. ~$13/ADR now looks like a solid floor. With much of that already priced in, the remaining upside is mostly valuation/overbid optionality. Full pitch on SSI👇 https://t.co/J8Amvtfqou
A formal phase-two strategic review is now underway. Transaction comps imply 10–14x EBITDA versus $PBI’s much lower multiple. Greystone’s conservative value is in the mid-$20s versus ~$16.50, with a deal offering further upside.
AI could pressure $DOX revenue, but also lower delivery costs. If the embedded managed-services franchise holds up, modest growth and buybacks could drive attractive returns without a heroic recovery. The key risk is AI savings flowing to customers rather than shareholders.
9/ $PBI pitch by @GreystoneCap Pitney Bowes owns a sticky postage-meter installed base and the only national-scale US presort network. The market still treats it as a terminally declining mailing-equipment business.
8/ $DOX pitch by Rewey Asset Management ~7x FCF for mission-critical telecom software priced like an AI casualty. Roughly two-thirds of Amdocs’ revenue comes from long-term managed services built around proprietary billing and customer-care systems that are risky to replace.
7/ $RMTI pitch by @MinotLightCap Potential $18–30/share vs ~$8. Rockwell supplies dialysis concentrates in an effective US duopoly and has finally turned FCF positive. At entry, ~$15m of net cash backed a ~$30m market cap, leaving the operating business valued at ~$15m.
$RMTI management targets ~$100m of revenue by 2030, potentially supporting $5-10m of FCF. Years of losses and a reverse split have left investors skeptical. Still illiquid and operationally fragile, but sustained cash generation could drive a substantial re-rating.
5/ $FOUR pitch by Emeth Value Capital Shift4 is an end-to-end payments platform dominating attractive verticals. It is the #2 US restaurant POS provider, serves ~40% of US hotels and processes payments for 75%+ of professional sports venues.
4/ $NAVI pitch by @gatorcapital Navient trades near 40% of TBV as the market treats its legacy student-loan portfolio as a melting ice cube. But private lending has returned to growth, with Q1 marking its first portfolio expansion since 2021.
CDTi’s $7.7 million nanocap valuation rests on clean-energy coating orders arriving before roughly 12 months of cash runs out, despite…
S&P Global has fallen about 20% in 2026 as AI disruption fears test the durability of its ratings, indices and financial-data franchises.
Vistra's contracted nuclear fleet benefits from data centers' high, steady load factors, while Amazon and Meta contracts contribute roughly…
Harte Hanks’ $5-per-share sale to Starr Equity offers a 15.7% gross spread, with closing dependent on $15 million of debt financing and…
The AI build is moves more aggressively off the balance sheet Convequity’s debt scan across $MSFT $AMZN $GOOGL and $META: what these companies borrow in public is rising slowly. What they have promised to spend later — leases not yet started, equipment orders, contracted compute — is rising much faster. In 2Q26 that gap is the widest in four quarters. Off-book commitments are running toward +316% year-on-year. On-book debt is barely moving. If you only watch headline borrowings, you miss the cycle. MSFT is the clearest case. On-book debt +15% YoY. Off-book commitments +138%. That is why its all-in financing load is about 17x reported borrowings. Microsoft is under pressure from two sides: shareholders who want more AI spend, and shareholders who want less capex and faster returns. The compromise is to slow the capex it puts on its own books and lock in capacity from $IREN, $NBIS and other neo-clouds instead. How that works: IREN or NBIS borrows, builds the site and owns the chips. Microsoft signs a multi-year contract to pay for the capacity. Microsoft does not put the building on its balance sheet. It takes a future bill — rent and service payments that show up later as operating cost. Asset risk moves to the neo-cloud. Payment risk stays with Microsoft. GOOGL looks similar on a multiple and is doing something different. All-in commitments are 10.2x borrowings: $100bn of headline debt, $121bn including leases, $902bn off-book. $811bn of that off-book pile is purchase orders for its own stack — TPUs and the kit around them — not rented neo-cloud sites. On-book +190% YoY. Off-book +836%. That multiple is Google buying the factory, not renting it. META is closer to Google than to Microsoft: on-book +127%, off-book +680%. Some of Meta’s orders are reserved compute from CoreWeave and Nebius, which Meta will expense as it uses the capacity. Most of the pile is still Meta committing to build and buy for itself. AMZN is the most balanced of the four (+59% on-book / +80% off-book). Both lines are rising together. If the cycle breaks, Microsoft is less stuck with buildings and chips it owns. It is more stuck with bills it already signed. Google is more exposed because more of the capital is already spoken for on its own account. If compute gets scarcer, the extra megawatts IREN and NBIS have not yet sold can go to whoever pays more. Microsoft then has to wait or pay up. Because it owns less of the physical stack, it has less spare capacity it can simply switch on — which means higher compute costs and tighter margins. Powerful cycle. Not a broad bubble. The heat is in the promises, not the 10-Q debt line. Full AI Bubble Barometer available at Convequity.
FT: Big tech giants booked a $160B+ windfall last qtr from investments in other AI companies. $GOOG, $AMZN, $NVDA, & $MSFT all had lg boosts to their pre-tax profits from ‘other income’ in theory P&L, due largely to valuation gains on equity stakes in other leading AI companies
Voss Value Fund @CapitalVoss initiated a position in Versigent PLC $VGNT, a recent spin-off of Aptiv $APTV. The Fund said the company is an entrenched global oligopolist in high-complexity automotive wire harnesses, with content in one of every six vehicles built worldwide and nine of the ten largest OEMs as customers. Yet it trades at roughly 5x EV/EBITDA, meaning there’s substantial upside.
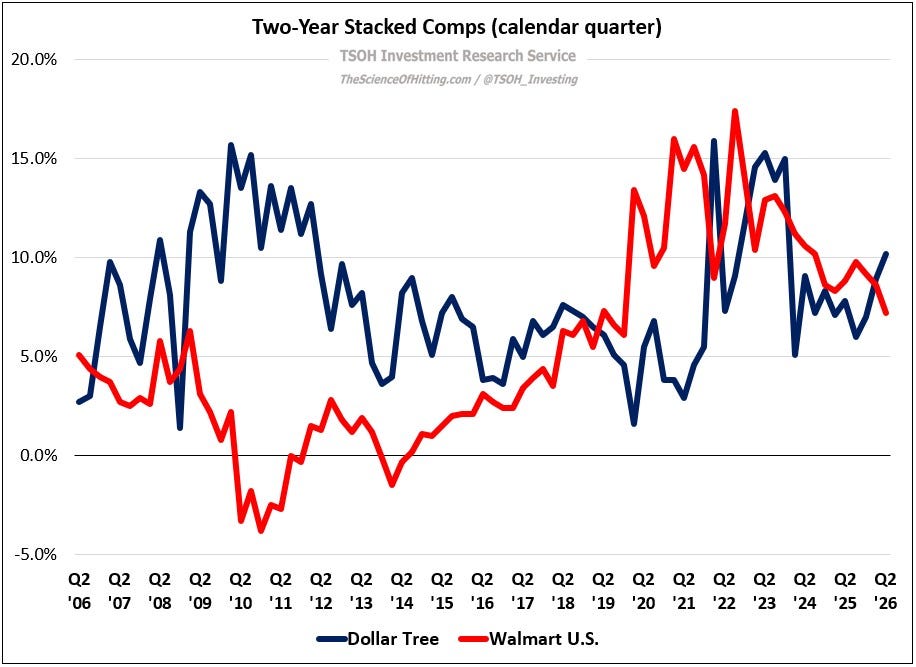
Dollar Tree’s $1.25 opening price and multi-price assortment supported 10% two-year comparable-sales growth, outpacing Walmart U.S.
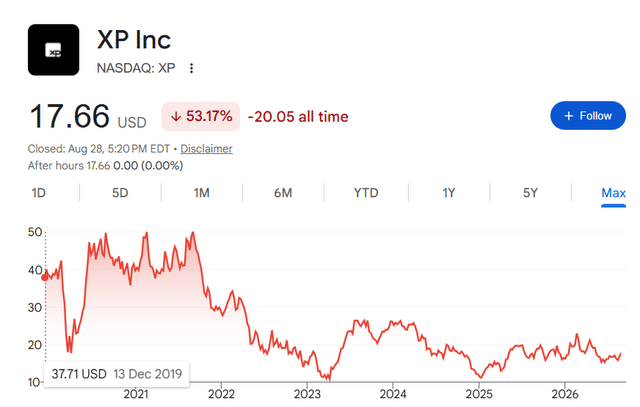
LLM adoption is rising but may not generate returns sufficient to justify current AI investment; the aggressive portfolio exits Estee…

Palantir shares at $183 exceed Cestrian’s $177 target after Q2 revenue grew 93%, prompting a 48-hour Distribute rating as Q3 growth…

Salesforce trades at 14x trailing unlevered pretax free cash flow after Q2, with 10.8% revenue growth and unproven agentic AI adoption.
@keshwani_s7063 @grok why has $FTAI sold off?
If you liked $FTAI at $209, you’re going to love it $186… https://t.co/J40mboCyG8
Quantum / SMRs seems pretty bombed out. I love to see a better entry point on $OKLO or $QBTS
$RUM Great entry the last week. Target back to $6-7 range. $DJT ok entry here, long way to go to zero over the next few years. https://t.co/9cQrIyVmp7
A fun trade I've had in is arbing convertible preferreds. Long $PCGPRX short $PCG, long $QXOPRB short $QXO. Trading below the convertible price while pocketing a nice dividend with cheap financing.
@erik_ywr Absolutely, that's why I been long $sbux and long @erik_ywr 😄
@HoocheeEnjoyer $HRTG hits 30s and you hit the bars immediately??? At 4pm?
*ANTHROPIC SIGNS $35B CLOUD DEAL WITH LAMBDA IN TEXAS: WSJ $NVDA holding the lease, developed by $HUT https://t.co/fqoFb2vl2J
$NVDA now trades under 10x GS’s updated 2028 EPS estimates, per GS’s Peter Callahan: https://t.co/OUP3K9CLj5
$TSLA ripping after GS raised their Humanoid Robot TAM yesterday to 6.5 million units, or a $138B market opportunity by 2035 The robots are coming https://t.co/hObI1dtvQq

Aurora Innovation targets 200 driverless trucks by Q4 2026 and FCF breakeven in 2028; 0.6% of US combination trucks by 2030 supports 20%…
 Andras Tory
Take-Two Interactive, $TTWO, trades weeklies around GTA 6 news and debates the benchmark for the game’s success.
Krista continues to do things that benefit all $WCCB constituents. https://t.co/SfnvY46NVh
XBP’s failed post-merger integration leaves its turnaround dependent on contract wins, asset sales and cost cuts overcoming a heavy debt burden.
Sol Bier and Factorial Funds backed SPCX, Anthropic, Perplexity and ElevenLabs early. A conference interview covers Sol Bier’s venture investing.
@reddy67874 @Jerry19880 @piques15 only stock i added to today was $AMZN. like the risk/reward probabilities here on $TTWO, but there’s more downside if player sentiment and engagement data start moving the wrong way.
@steven_finch Pretty much everything I own has revenues declining. People pissed and moaned when I bought $HOG because it was "dying"
@sigmazerocap I own a small position in $CRM (thankfully lower cost base), and no $META, so $CRM it is. Clicks results. Wow, guess CRM is going up another 25% next quarter. Love when everyone is positioned wrongly.
Aduro funded R&D and pilot-scale development through equity raises, warrant conversions and $5.5 million of share-based compensation while its pre-revenue operating losses widened.
@ryanTesling @piques15 added to $AMZN today, no surprise there
@ryanTesling don’t care as i’m not focused on $AMZN short term trading rn
@Spykex02 no. currently just holding $TTWO equity. i did have a large one-day weekly call position i entered on thursday’s dip and exited friday. down a bit more today than i made last wk but im fine!
@piques15 $TTWO could drop 30% this week and my ’26 ROI would barely notice. I’ve had worse Mondays this past month. https://t.co/meivfWSxx6
apparently $TTWO wanted to make sure this quote still holds up. https://t.co/09z8jddmcH
Seems like im the only one blown away by these numbers. $ttwo had an incredibly storied history with many successful games and over a decade of high margin gta5 online numbers, but even pre Zynga writedown barely had any profit. Will gta6 be different? https://t.co/CivKO6DyFX
August 2026 portfolio lists Evolution, Toyokumo, Parigroup, Leatt, BioRem, Secunet, Shelly, Enogia, Lindbergh, ErreDue and Circle Group.
$FIRY update from Israeli court https://t.co/yI5CThILVQ
Shitco Yarrow Bioscience $YARW has finally cracked. https://t.co/qk6gptxPhj
$SAIL also with news out today on expanding their partnership w/ $CRWD things need to move fast .... https://t.co/YICsfVXAPX https://t.co/sT950PQ0mu
$NTSK + $CRWD News out today. $NTSK is currently one of my top holdings in cyber along with sail and silc https://t.co/KlY5gNBw5V
Having Sony Music Entertainment makes it a lot less likely Gungho will attempt a take-under of $GRVY, IMO https://t.co/xvjalTHgN7
Vistance Networks' $5 distribution leaves year-end 2026 cash and receivables near 60% of market value, while the core trades at 2.75x EV/EBITDA.
Rayonier’s $1.86B debt costs 2.29% after swaps and Farm Credit patronage refunds, giving its four million timber acres a cheap fixed-rate funding edge through 2028-29.
$ACMR https://t.co/gzKlQTn1pF
@SovietInvestor ok well $RYN sells for $1,800 per acre...
Waystar sells revenue-cycle software for a US claims process where roughly 18% of submitted claims are initially denied and healthcare…
Genius Sports guided for $1.005–$1.025 billion of revenue and $285–$295 million of adjusted EBITDA despite higher leverage from the Legend…
 Mayank Marwah 5 clicks
I just published my Portfolio Update for August 2026. It includes: ▫️My current Portfolio & position sizes ▫️Earnings Update about $YSN.DE, $SLYG, $LEAT, $4058 ▫️Recent news & information about $CIRC.MI, $EVVTY, $4058, $SLYG https://t.co/bEmwcymkyy
Hewlett Packard Enterprise’s Q3 hinges on converting AI-networking orders while preserving its 21.6% segment margin, after booking $1.8…
 Deep Value Investing 2 clicks
Verastem's AVMAPKI FAKZYNJA generated $43.7 million of H1 2026 revenue, funding its KRAS G12D oncology pipeline ahead of an October VS-7375…
 Equity Eagle 2 clicks
$BMRN up premarket on settlement agreement. I continue to like/own. https://t.co/a6WZ9ksaeH
This hypothesis was wrong. We now have earnings from $LX $QFIN $FINV, and they all were terrible noting a late June credit event in the industry. Downtrend has continued, and will end when it ends. https://t.co/X86cYvTk0h
PayPal's failed Stripe and Advent bid leaves a Venmo spin-off or aggressive buybacks as value-unlocking options amid slowing growth and a…
 The Asian Investor 5 clicks
Tower Semiconductor generated nearly half its revenue from AI optical content as Q2 2026 revenue reached a record $460 million and…
 Miletus Research 3 clicks
