
💥PETITION💥 on X
Saddened to learn that Lovesac Company ($LOVE) doesn’t have any funded debt. Would have been fun to watch a dumbf*ck reaction to a social media post (by the riotous, Deric Cahil) take down, say, Ares, lol. https://t.co/a466vIoOtP
Monday, August 24
Everything we published on this day.
41 stories — the front page that day →
Saddened to learn that Lovesac Company ($LOVE) doesn’t have any funded debt. Would have been fun to watch a dumbf*ck reaction to a social media post (by the riotous, Deric Cahil) take down, say, Ares, lol. https://t.co/a466vIoOtP
After being quiet on X for some time, I'm pleased to return to public posting to highlight our thesis on $PRKS 👇 https://t.co/vjzhqA7Mx1
Jana Partners is pushing Alkami Technology $ALKT to pursue a sale, arguing the fintech platform is materially undervalued after a sharp share price drop. At first sight, Alkami looks like your typical not-yet-profitable / disgusting share-based comp / a ton of open market sales company. That said, this thing actually has an interesting offering, which makes continued ~20% organic growth and high customer retention very probable over the next years. Also, we’ve seen funds getting more active in the market and taking significant stakes (ao, General Atlantic).
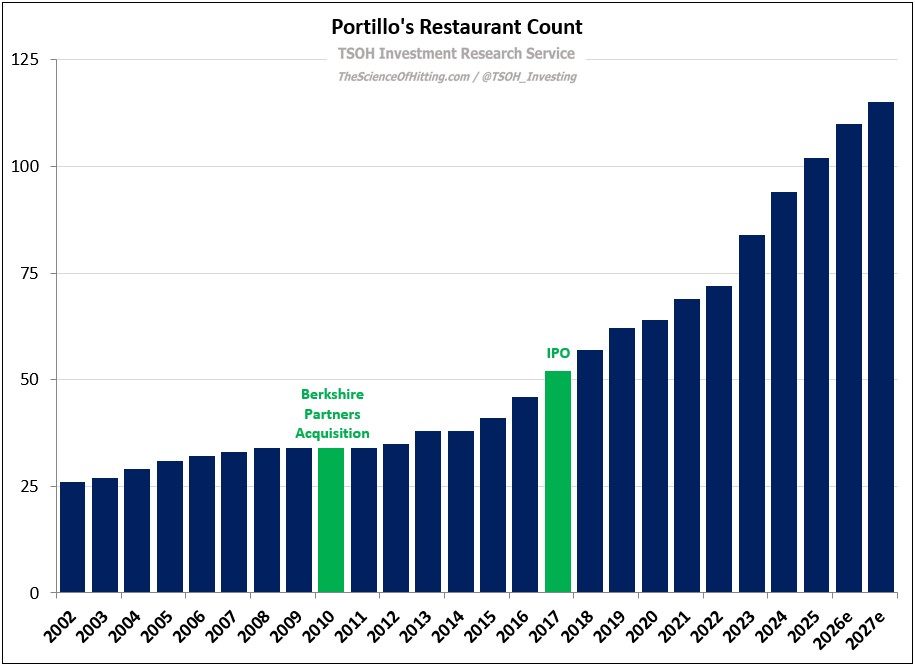
Portillo’s reset follows weak Texas unit economics, cutting next year’s openings to five from roughly 10 annually and shrinking store…
CDTi has doubled revenue since 2020 to $10 million and is moving catalyst programs for data centers, methane abatement and carbon capture…
US-Canada tariffs impose 50% duties on $20 billion of Canadian goods, lifting US steel makers while pressuring Canadian exporters and…
$BABA management continues to do everything in its power to keep the stock a generational value trap https://t.co/kgj6l73QpY
Ziff Davis $ZD on their Q2 earnings call: "We've seen huge increases in the amount of code generated by AI. We shipped 24% more code in the second quarter and we expect nearly 100% of new code to be generated by AI by the end of the year"
Yeah it’s pretty hard to predict, I think with good data tracking and social sentiment you might be able to gain an edge. If you can predict only a handful a year your returns could be outstanding. I successfully predicted $BYND last year for a sizeable return. You could also subscribe to https://t.co/7R7A2Nonkw
With all the analysts updating their models post the Q2 earnings beat, $CLS is now trading at 13x EBITDA NTM consensus while growing topline 65%.
If the $BHF deal goes through the SEC needs to investigate whoever bought 500 of the September 55's for $1.30 today
$GOOS continues to fly south new 52 week low -88% drawdown over 7 years. https://t.co/V8kTwqDJVy
$celh https://t.co/apPT4ADdcm https://t.co/kGhsFi95q7
$NN. This podcast is must listening. Doesn’t mention NN by name, but amazing insights into FCC strategy under Chairman Carr. This Week: The FCC's Spectrum Pipeline with Arpan Sura - The Week with Roger | Podcast on Spotify https://t.co/tSebqMRetN
Was also wondering if $WMT could use some of that electricity. e.g. would the grid destabilize if their usage increased 20-50%. The bolt-a-GPU-on-your-house thing seems a little silly, but maybe it makes more sense on commercial buildings? The scale of those Nebius/Coreweave numbers seems hard to believe...
$OMER My friend Matt just sent this to me. Great review of how Yartemlia works. Narsoplimab Mechanism of Action: Fighting Transplant–Associated Thrombot... https://t.co/cxTshzo3Qq via @YouTube
@herbgreenberg @ParagonIntelNYC As it turns out we've had a short call out on $LOPE since the start of the year...
Someone just sent me a brief slide deck on $MCD and it made me realize that I never, I mean never hear anyone talk about it on this platform. Not even @jeffmacke mentions $MCD at his 3:45AM Denny's sessions and he likes to keep everyone on their toes about monster consumer franchises that receive little investor attention in this tech driven era. It did remind me that Ron Dottin called the bottom in this stock in late 2002 after $MCD went through 3-CEOs in a few years (one of which who died) and the company was seemingly in shambles. The stock went up 5x in 5-years. That was back when that meant something. On paper, $MCD looks like the least interesting setup (long or short) I've seen in a really long time.
Yes, you're touching on some of the issues that $Z/$ZG faces in the residential real estate landscape. There are reasons that the stock trades at 8-9x FY27 consensus EBITDA even though the company continues to grow revenues at a mid-teens clip YOY organically while generating huge FCF. We've written HUNDREDS of pages on these issues so this is not the right forum to litigate the relative merits of any of these concerns. Zillow has a lot of organic initiatives that should sustain growth for the next few years. From all my work, the commission structure of the industry is not changing much right now, but of course that seems inevitable at some point. If you really drill down to what $Z/$ZG is doing strategically it's all about becoming more deeply integrated into the transaction. Follow-up Boss was the most important acquisition the company ever made IMO. You don't need to see around corners here, but you have to look through the noise to see what the company's doing.
$Z/$ZG announces it reached a resolution with the FTC on the commission's anti-trust allegations related to the #zillow/#redfin rentals syndication deal. The partnership will continue going forward but $RKT/Redfin will be required to buildout its own rentals listings syndication platform and Zillow will waive any non-competes. My sense is that $RKT/#Redfin are not hugely interested in the rentals space at this time and Zillow's market share gains will continue at a robust clip. This is a positive for $Z/$ZG and eliminates another litigation overhang. We estimate the size of the rental property advertising landscape at $9-$10B annually. One has to wonder where this lawsuit came from given that it involved a $100MM deal in a massive marketplace. $CSGP?
👀 have been out of $WU for a short time. A sale would not surprise me, but probably makes more sense after it digests $IMXI. https://t.co/bno9ZATJ4I
$PSFE bizarre pivot. I'm long rn, and at first glance don't like the move. https://t.co/K2ZMLhQcro
@sidecarcap @GeoInvesting I should’ve also added $RWWI to this list
$TGT continues to run post earnings now at 17x next year before considering net debt load with earnings expected to shrink next year on less than 3% growth Tough weekend too. ATF with 1.8m members (teachers union) announced a boycott for back to school of Target last week and today are having to make public comments about a racially insensitive clown costume….. might seem on the margin but prior issues with pride and other campaigns were a key contributor to TGTs foot traffic problems
After Montgomery-Caribe and the impact on liability for brokers, and the general trend of dramatically higher insurance across the trucking space in recent years. How do people close to the freight market think about the truck rental companies like a U-Haul? If we are pushing liability on professional drivers, what is the case to give everyday drivers access to various side truck fleets and send them off to drive them on American highways? Clearly this practice seems unlikely to go away and U-Haul likely can pass escalating insurance costs on consumers better than the professional transport market but something to think about relative to margins and future demand in this space I think..... $UHAL
still feel the rotation from July-current is more about a short squeeze (the opposite end of the Situational Awareness portfolio) and the dispersion of having to unwind the long semi trade portion. But that rubber band is similarly stretched as it was the opposite direction at the end of June. Still feel its in the process of reversing (even the morning action today looks like a top could set in?) $RNG, $IT, $APPN, $TGT, $EXPE, $FDS, $PAYC, $ELF, $MET, $MFC, $GDDY, $V, and many more that were AI losers that have had incredible runs in the past 4-6 weeks seem like good ways to be short against a snap back to AI or a more seasonal unwind from policy risk trying to control rates, midterm/fall seasonal factors, etc. Especially with SaaS earnings taking the stage later this week and next (overshadowed by $NVDA on Wednesday)
The bigger issue I think is if changes in commission structures ongoing in real estate changes Zillows position in the industry and if they need to overhaul their model on the housing side? ZG running straight into https://t.co/xkzar3nuEl with success to increase supply and they'll both likely end up sharing that market (more a negative against csgp as they have the larger share in the rental space currently) but I think they end up shrinking that pie with their competitive attacks against each other. The compass and regional MLS provider lawsuit on exclusives, supply I think is the bigger case hanging over $ZG currently because thats one of the few threats to their dominance in mindhare in shopping/looking at homes online and their ad revenues there
$suja dug in on a recent ipo that has collapsed, weirdly saw a bunch of people commenting on it and got curious. On the service it seems cheap, but EBITDA is not FCF. And I struggle to understand how the business scales the way the bulls and the sell side want you to believe it will. Cumulative fcf has been negative for years, and of course they cleaned the books for an ipo year, so numbers elevated td, but still nothing to get excited about and forward numbers already look disappointing right of the gate versus S1 guidance (a very bad look, and terrible way to establish trust with investors and sell side coverage) New mgmt background is uninspiring Debt load is quite high even post ipo, the recently lowered interest rate is nice for delta in income statement benefits next few quarters but still have a cash flow problem but this was a nice development. No idea what the slice business is or how it fits - it would be massively cash consuming if they actually try to compete in that space saturated with deep pocketed players like poppi and many other players with national advertising campaigns and distribution/shelf agreements with players like $KO and $PEP (slice is never going to get any meaningful mind awareness or share without massive marketing investment, and Suja does not have the capital or FCF to pull that off. The 90s nosteliga approach already worn off from the early 2025 launch as its not a relaunch of that heritage brand, it's just the ip wrapped as a prebiotic soda. ---it seems more like a story to dangle to get the ipo out that they can sell a huge TAM in their s1, which is a further strike against the board, the PE sponsor and mgmt (likely it just sits at the range its at and gets slowly unwound in a year or two to stop further cash bleed) PE sponsored and +60% owner -- can be your friend on locking float, but also your enemy when they need liquidity, the lock up period ends, or decide to move on. --- one of their other exits through IPO went a similar way, massively collapsed in value after the ipo, wallowed for a number of years and ultimately the PE firm bought out the remaining shares at pennies on the dollar to the IPO price (agrofresh) --Structure of ownership and tax agreements is highly unfriendly to passive long common equity shareholders (good for sponsor) Ultimately its an uninspired story, that is more expensive than it appears with fully diluted shares, a very difficult consumer space that relies on trends, shelf space staying in front of KO and PEP and BUD in addition to many many others on distribution and shelf space - a concentrated number of distribution points that gives power to their buyers (highly concentrated customer base on their sales (grocery channel) Stock probably bounces along the way especially in fronton or right after the coming lockup and the market loves to squeeze things one last time before their final resting space, and the tighter float here (assuming pe stays in) likely makes that more likely an outcome than not. So a swing trader after a brutal IPO? sure I would likely bet up before it's back in time out likely for good. But as an actual investment? let alone long term investment? I find that argument deeply flawed on both financial and fundamental basis
$META prepares to launch consumer AI offerings https://t.co/cB3kWOricw
@SowingAlphaSeed So $AMZN probably has lots of sites to divert to compute if needed, no real permits even really required I bet...
 NRIX 2026-08-24
Nurix Therapeutics gained $700 million upfront from Roche, a 50% U.S. profit share and Roche-funded global bexobrutideg development,…
 Equity Eagle 3 clicks
@JakeNapppoa4 i don’t look at price but currently long $BE
Whether it’s AI demand or player sentiment heading into the GTA VI release, you’ll never get to ground truth by lazily relying on what algorithms surface: copy/paste headlines and viral investor takes often driven by confirmation bias. Go to the source. Small accounts. Real people who actually consume the product, not those clouded by the trade. $TTWO
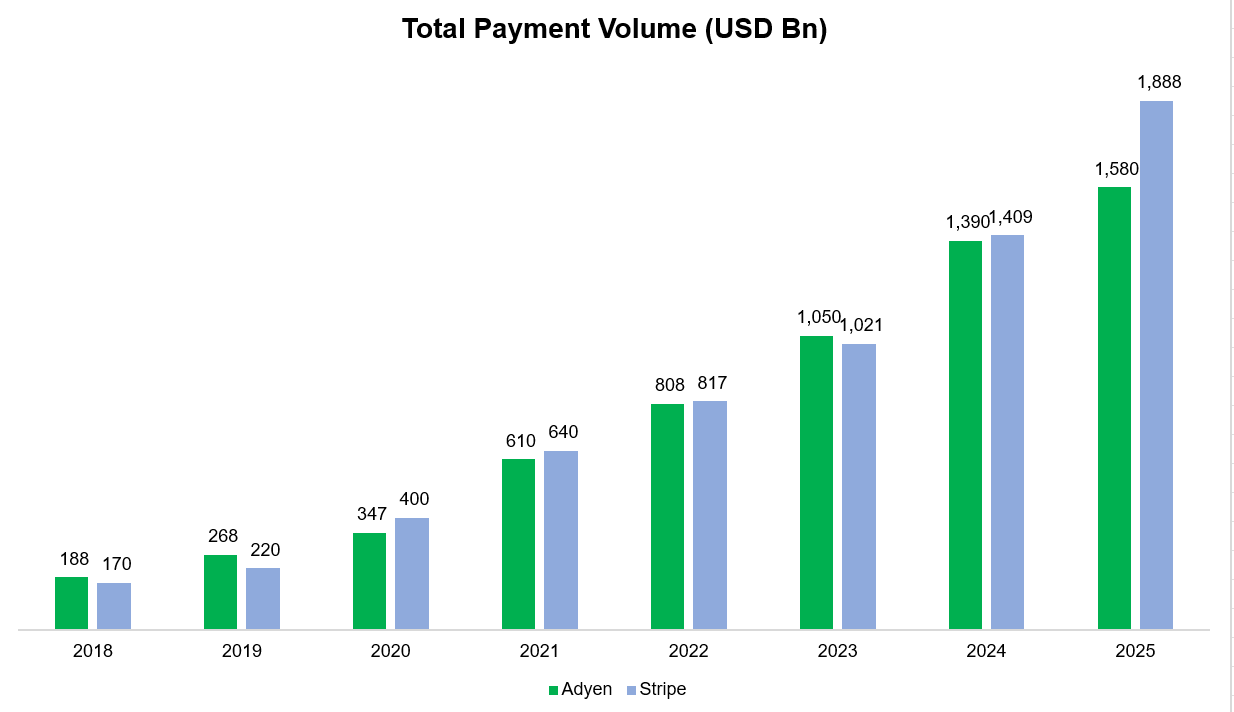
Stripe’s net revenue rose 41% in 1H 2026 versus Adyen’s 21% FX-adjusted growth, fueled by AI-native startups and acquisitions including…
$SOXX could go down 20% from here and still be up over 30% YTD
@TheValueist No, the best capital allocation for both $MU and $SNDK would be to either dividend back cash or sit on the cash until the cycle turns down. Buying back stock at around the peak of the cycle and at (give or take) 20x the value of their invested capital base is not smart.
Star Equity’s $5 per-share Harte-Hanks acquisition offers $2.50 cash plus 0.25 STRRP per share after proration, against a $2 break price.
RCEL 2026-08-24 AVITA Medical’s more predictable reimbursement, RECELL GO rollout and PermeaDerm economics support adoption, with cash flow breakeven…
 Myriam Alvarez 4 clicks HMY 2026-08-24
Harmony Gold targets copper at roughly 40% of future production, diversifying gold exposure while increasing sensitivity to commodity…
 Prakhar Agarwal, CFA 4 clicks UEC 2026-08-24
Uranium Energy Corp. is withholding production at low uranium prices while funding mine development through future share issuance.
 Marc Gerstein 3 clicks CVS 2026-08-24
CVS Health’s insurance, PBM, pharmacy and clinical-care integration supports margin recovery as its valuation falls to 11.78 times earnings.
 Juxtaposed Ideas 4 clicks
