
Prepared Remarks on X
$orcl https://t.co/iYGgRL7OOG
NYSE
ORCL
66 stories
$438B Market cap · 2026-10-28
$orcl https://t.co/iYGgRL7OOG
$orcl https://t.co/ijvvXUOS3J
$ORCL investors and employees https://t.co/o4BXT3Vwqp https://t.co/VUFdajk32I

Oracle’s $88.3 billion net debt and $90-95 billion capex plan pushed five-year CDS to 215 bps, despite 121% OCI growth and a $664 billion…
*ORACLE STARTS A NEW ROUND OF LAYOFFS: INSIDER $ORCL started a new round of layoffs today per Insider. Cuts on some teams could reach "double-digit %'s" on some teams
Adobe’s RPO and ARR growth continue to decelerate, while Oracle’s AI cloud capex economics face a supply-normalization test.

Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's…
Convequity’s AI Bubble Barometer (ABBX) — Week 17 | 11 September 2026 Our weekly framework tracks valuations, returns, capex, financing risk and forward infrastructure economics across hyperscalers, neo-clouds and model labs. This week’s print is also an Oracle week. $ORCL reported FQ1 FY27 on 10 September: revenue and cloud growth accelerated, disclosed backlog (RPO) jumped to $664B, cash capex ran hot, FCF stayed negative but better than feared, and a $20B ATM equity sale was completed. Capacity delivery was the operational headline — 850 MW and >300k GPUs in the quarter. The ABBX read is below. As of 10 Sep session close (US ET), 13 selected companies (hyperscalers + neo-clouds): -EV / IC = 5.80x (↓ 0.06x from 5.86x on 4 Sep Friday close; ↓ 1.87x from 7.67x on 15 May series start) - All-in EV / IC (incl. private OpenAI & Anthropic) = 6.52x - ROIC / WACC = 3.07x in Q2'26 vs. 3.73x in Q1’26 - ROIC – WACC spread = +23.1% EV/IC tells you what the market is paying for every dollar of invested capital. ROIC/WACC tells you whether those dollars are still earning more than they cost. A classic bubble is when EV/IC keeps expanding while ROIC/WACC is rolling over. That is still not the setup. Returns remain more than 3× the cost of capital while EV/IC for the public builder set sits near 5.8x — well below the midsummer 7× prints and the 15 May series start. The multiple compression looks more financing-driven than fundamental: the return spread is still wide. Oracle is the live test of that financing channel — and on ABBX it sits halfway between the diversified hyperscalers and the neo-clouds. Start with backlog. ORCL’s $664B RPO is now in the same league as $MSFT (~$678B) and ahead of $GOOGL (~$520B) and $AMZN (~$496B). Neo-clouds are a different scale entirely: $CRWV ~$104B, $NBIS ~$40B, $IREN ~$17B. On disclosed backlog, Oracle is already peer to Microsoft — hyperscaler-scale contracted AI demand. The constraint is not finding counterparties; it is delivering power, GPUs and campuses against a backlog that already exceeds its AI enterprise value (EV/RPO ~0.7x on the company row). Valuation paints the halfway case. On Forward Valuation, Oracle’s AI EV is roughly mid-hundreds of billions against ~$163B/year of plan-implied revenue (~12.8 GW internal × ABBX blend (colo vs. GPU rental vs. mode/app derived revenue) — about 2.8x EV / plan-implied revenue and ~4.3x EV / implied gross profit. That sits well below Microsoft, Amazon and Google (roughly high-single-digit to low-double-digit EV/plan on the same framework) and Meta (~4.5x), but well above CoreWeave and IREN (sub-1x to low-1x on plan revenue). EV/IC tells a similar story: Oracle is cheaper than the big four diversified names and closer to the neo-cloud pack on capital multiples, while its backlog and quarterly capex now look hyperscaler-sized. The market is pricing Oracle more like a leveraged AI builder than like Azure/AWS/GCP — even though its contracted demand book looks like theirs. Capacity mix explains part of the gap. In AI Infrastructure Capacity Plans, Microsoft, Amazon, Meta and Google all show some external planned GW — capacity rented from specialists such as CoreWeave, Nebius and IREN. Oracle shows none. Its disclosed plan is treated as internal OCI build. Oracle is the landlord in this graph, not a tenant: it sells AI cloud to frontier labs and enterprises, and does not need a large rented-GPU line to hit the plan. That is control and a cleaner path to own-stack margin. It is also concentration. Build cost, leases and delivery sit on Oracle, not on a diversified supplier set. The Implied Revenue & Valuation Multiples table shows the same shape in the numbers. Oracle’s implied ABBX USD per planned GW is about USD 13 billion, below Microsoft at about USD 17 billion and well below Meta and Google in the mid-20s. That is not a claim that OCI is worse infrastructure. It is a revenue-density assumption. Oracle’s plan is weighted to large-contract AI infrastructure sold to hyperscale counterparties, closer to wholesale cloud economics. Meta and Google’s higher implied USD per GW embeds denser take on their own AI and platform stacks. CoreWeave can look high on a thin equity base. Oracle is the opposite: a huge RPO and more conservative revenue per gigawatt of disclosed plan. Financing is where Oracle looks more neo-cloud than Microsoft. Our Expanded Debt & Capex, split by disclosure vintage: From FQ1 FY27 (31 Aug, condensed balance sheet in the earnings release): borrowings $125.3B, cash $36.4B, IC $156.2B, plus operating-lease ROU/liability lines on the face of the BS. Still on the May / Q4 FY2026 full note lock (not in the FQ1 PR): on-books stack ~$167B (~1.3× borrowings), uncommenced DC leases ~$260B, purchase obligations ~$13B, all-in burden ~$441B (~3.4× borrowings). That roughly 3.4× all-in multiple sits near Amazon (about 4×) and above CoreWeave (about 2.5×) and IREN (about 2.9×), but far below Microsoft (about 17×), Google (about 10×) and Meta (about 9×). Those names carry large off-balance-sheet lease books relative to thinner headline debt. Oracle’s uncommenced lease line is still huge; the multiple looks moderate only because borrowings themselves are already large. The setup is notes debt, a completed ATM equity raise, heavy cash capex, negative FCF, and a large May commitment book that the next 10-Q still needs to update. Management says new contracts need no further equity raise. ABBX treats that as a claim to monitor, not a free pass. Oracle’s Q1'27 cash capex was about USD 28.5 billion — in the same league as Meta, below Microsoft, still below Amazon and Google. Against that sits about USD 664 billion of contracted future work, more than twenty times one quarter’s build spend, with management guiding that roughly half should become revenue inside three years. That is the highest backlog-to-build ratio in the group, and it is why demand on paper looks full. It does not mean this year’s cash bill is already paid. RPO is multi-year revenue, not cash this quarter. Capex is a repeating outflow — FY27 guidance is about USD 90–95 billion, or about USD 70 billion net after customer prepays — and Oracle has also signed about USD 260 billion of data-center leases (as of May 2026) that are not yet on the balance sheet and start as campuses come online. Rent is due once those leases begin, even if customer cash is later. That is why the stock can de-rate on funding even with a full book. The high ratio argues for utilisation if delivery lands. Free cash flow and the lease stack are the separate question of who funds the build before the backlog turns into cash. Other hyperscalers can look weaker on the same ratio because more of their spend serves their own ads and cloud stacks, which never appear as Oracle-style external backlog. Delivery is catching up with that book. Oracle has put about 850 MW and more than 300,000 GPUs into service, with GPU utilisation at 97.9% and renewals at a premium — capacity is being used when it lands. At the Abilene, Texas campus, six of eight buildings are live, and customer acceptance of new clusters has shortened to about 24 hours: delivered capacity is signed and usable in a day, not weeks. The earlier caution still holds: lab tests of how many tokens a cluster actually produces, and real traffic samples through gateways that serve open-weight models, are still thin. Campus delivery looking full is not the same as those checks. Direction still matters. Across the complex, Friday’s snapshot still looks like a build-out, not a hangover. For the 13 names, aggregate AI enterprise value is about USD 10.7 trillion. AI EV over disclosed backlog is in the mid-single digits. AI EV over plan-implied revenue is in the high-single digits on the broader cuts. Planned capacity is still well above 100 GW. Those multiples look attractive if the book converts: a few years of contracted work, and under 10 times the revenue the build plan implies — not a 20-times software multiple on a hope. Financing risk is the other side of the same picture. One debate is a high EV versus invested capital. Another is a high EV versus off-balance-sheet commitments. Oracle now forces both into one name: hyperscaler-scale backlog, a neo-cloud-like equity valuation, and a commitment stack you can inspect in ABBX. Verdict: no broad AI bubble signal. Week 17 of our ongoing weekly series. Updates every Friday. Full interactive dashboard (Fundamentals, Forward Valuation, Expanded Debt & Capex, Capacity) available at Convequity. #AIBubbleBarometer #AIBubble
Large cap software comps rerating higher OAI / codex accelerating Jensen saying he’s funding the labs next yr $orcl 🚀
@Ross__Hendricks @DratchCap @WarrenPies Equity is abundant even while absolute debt issuance skyrockets. I would think prudent capital allocators would tap the former… (see $GOOG, $ORCL as of late)
OpenAI “ARR” apparently run rating at $60 b, and (for the most part) they haven’t yet monetized their 1 billion weekly consumer actives. Bullish $ORCL. https://t.co/pBDIrTTAqV
If Newsom has aspirations to run for president, he can’t be perceived as being bad for big business. The Warner Bros. $WBD situation is not the same as Sable Offshore $SOC and I am sure there is tremendous political pressure through the Ellisons. Larry didn’t get to where he is by backing down from a fight and we saw this in action during the acquisition of Peoplesoft by Oracle $ORCL more than two decades ago.
OpenAI’s CFO Sarah Friar also on a media tour spreading the good cheer… bullish $ORCL https://t.co/oymK8c7nVc
Sam Altman sounded a lot more at ease about his revenue ramp and was even bullish about his compute commitments (even saying they may have been too conservative) in this podcast. Given that he has been relatively quiet on the podcast circuit over the past year, I view this as a positive tell on OpenAI/$ORCL. https://t.co/yezInyb9XB
I pitched $ORCL at $285 as a short last October at my conference. Now at $120 think it is intriguing as a long… https://t.co/8QB7O3VSoH
AI capex rests on coding-centric benchmarks, cheap-model commoditization and circular financing: OpenAI’s $60 billion annual Oracle…
To me it's a situation where you just need one bad actor to go crazy with compute scale and it practically forces the hand of everyone else to do the same because they are scared if they don't they will lose the race. Or even better, they actually agree that you should go crazy with compute so they are doing it for rational reasons. Here this bad actor may not even be acting in bad faith and they might even be right. Look at OpenAI buying insane amounts of compute early on and many thinking they are insane and shorting stocks like $ORCL but suddenly over the last 2 months now hearing they are servicing their customers better than antrhopic and many people moving to openai.
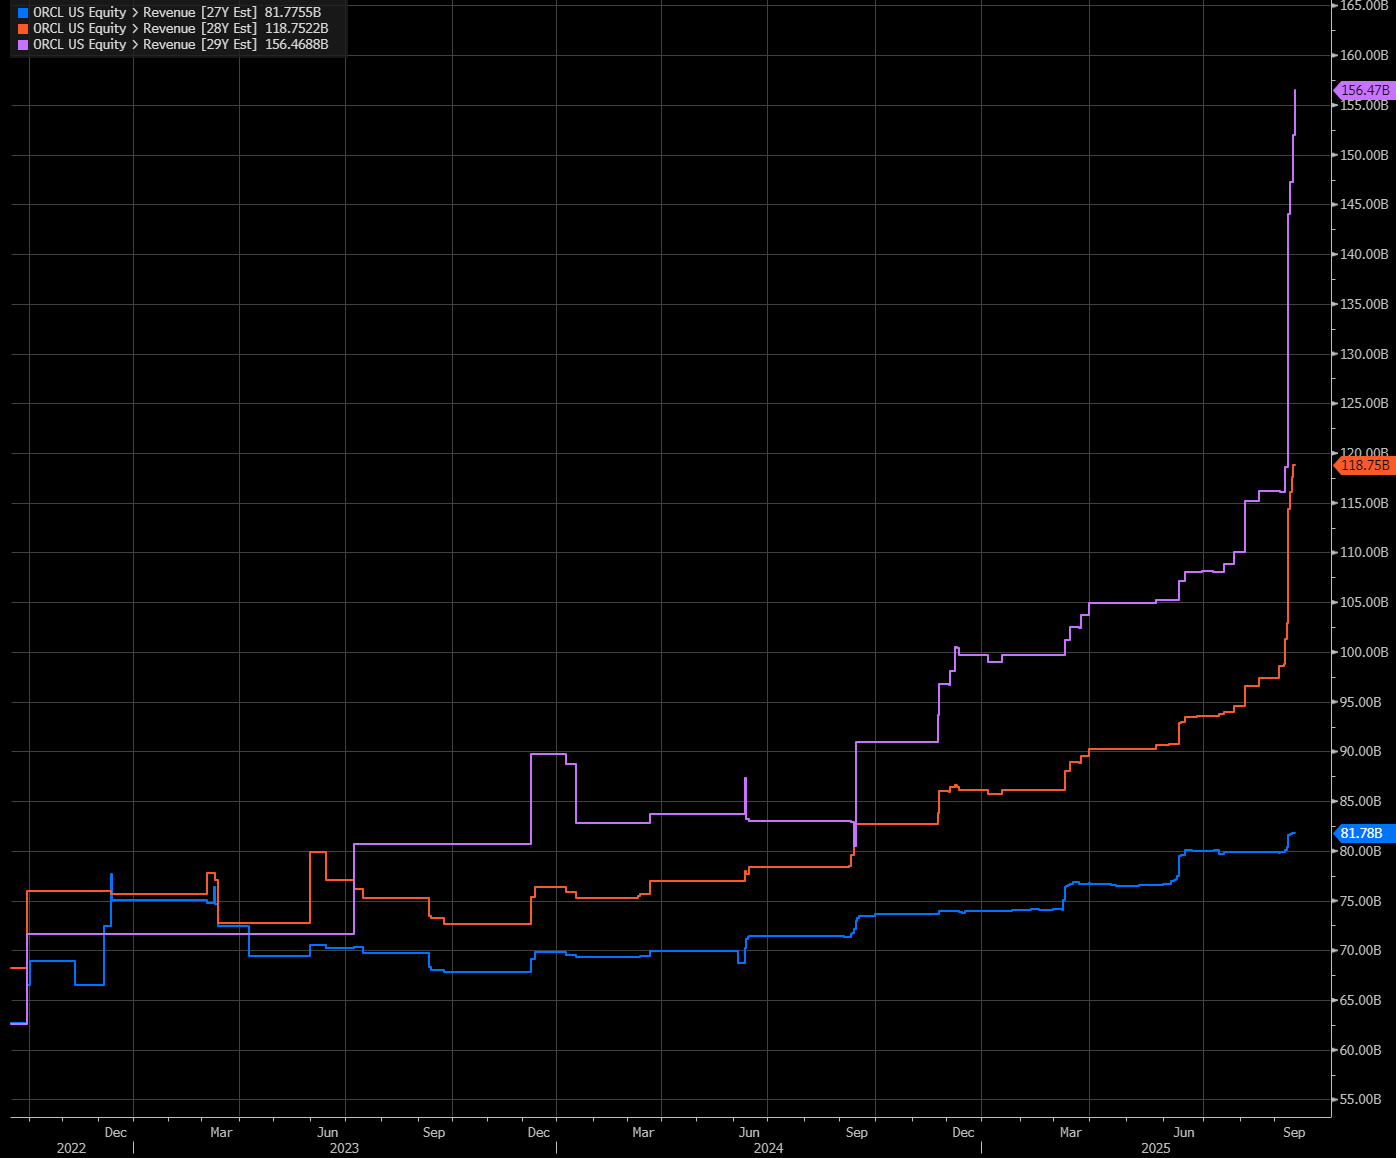
Oracle’s $455 billion RPO and four-year cloud guidance position it as OpenAI’s primary infrastructure partner, while requiring major…
Letters that discuss ORCL.
Companies the stories above are also about, besides ORCL.

