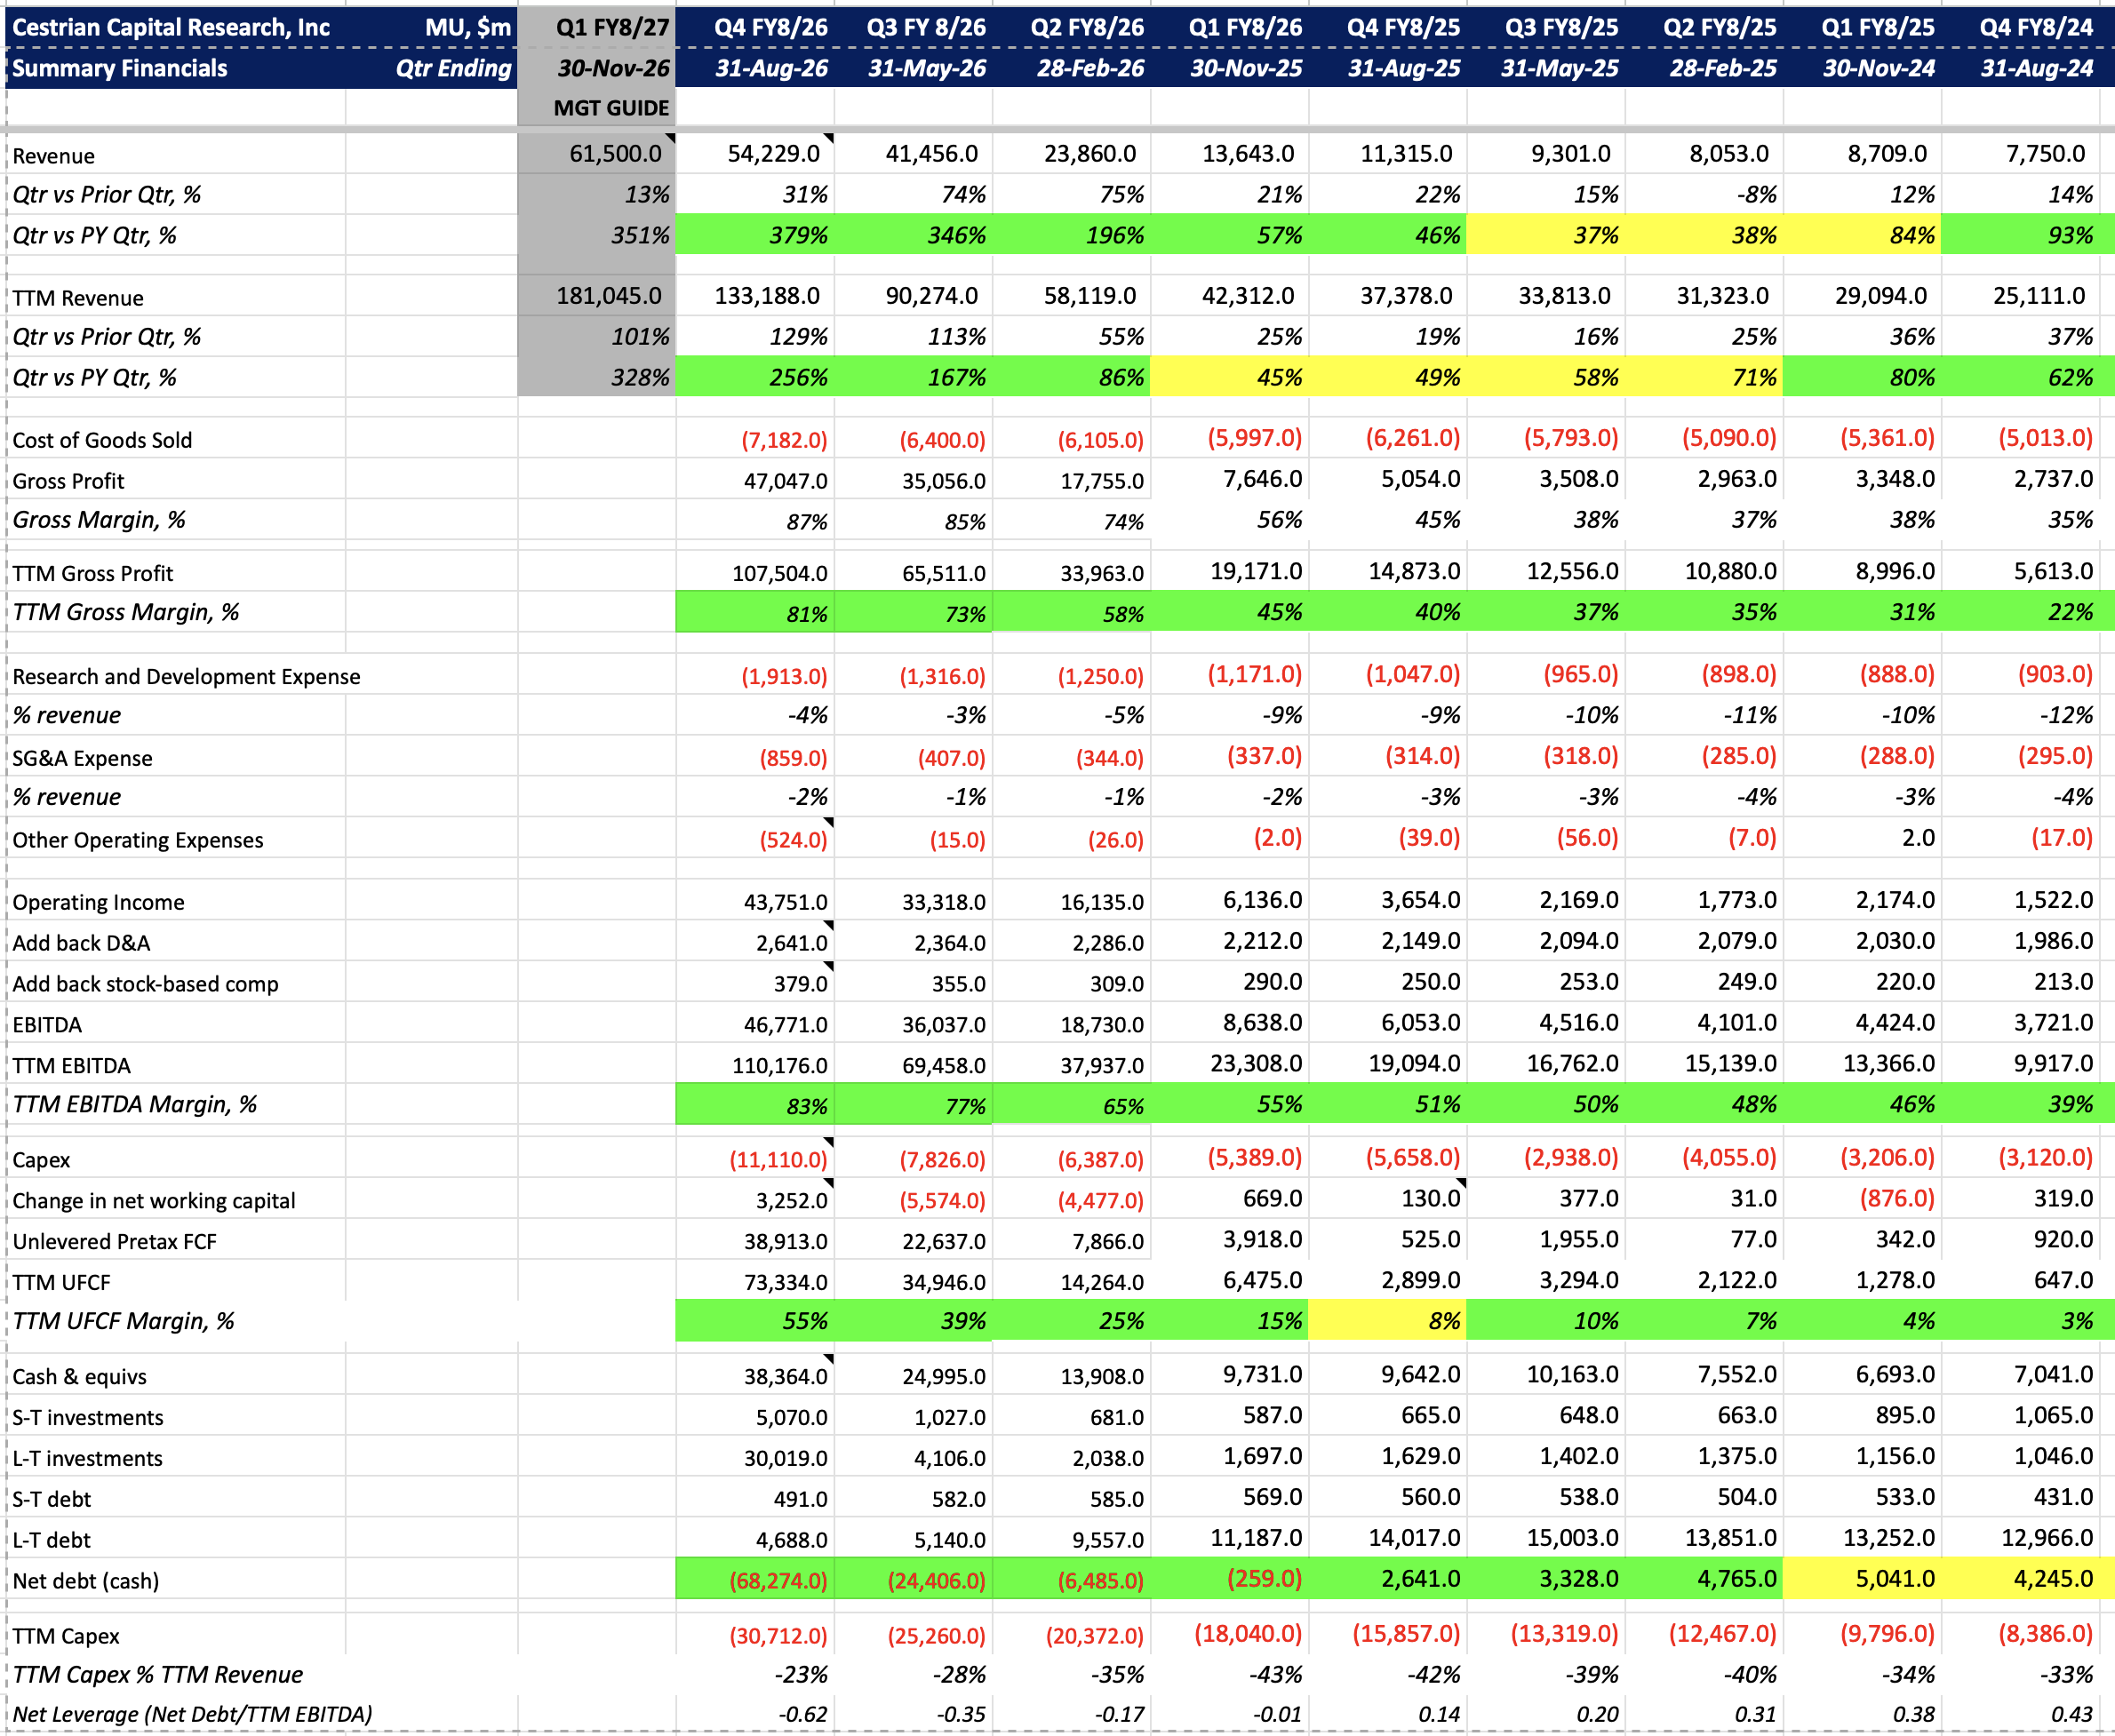
Micron (NASDAQ: MU) Stock Rating: Hold After Q4 FY8/26 Earnings - No Change To Rating
Micron reported Q4 FY26 revenue of $54.2 billion, up 379%, and guided Q1 revenue to $61.5 billion.
NASDAQ
MU
66 stories
$969B Market cap · 2026-10-22
Micron reported Q4 FY26 revenue of $54.2 billion, up 379%, and guided Q1 revenue to $61.5 billion.
$GOOGL Gemini 4 Argon benchmarks got released. Against GPT-6 Astra + Anthropic Fable 5.1 / Opus 5.5. Still coughing nonstop, so will comment on $MU / $JBL earnings later. I've always thought Google's internal models were stellar, but anecdotally, they seem to get hard nerfed shortly after public release... Maybe because of compute constraints? But yeah, looks like Google is back.
Micron and Nike earnings headline a weekly briefing featuring Exor’s NAV discount, Meta’s Muse agent and Bellway’s UK housing valuation.
Micron’s November revenue guide will test whether an 86% gross margin reflects a structural memory shortage or a cyclical peak, while…
Micron’s DRAM margin commentary, Core PCE and payrolls headline a week also shaped by Iran ceasefire talks over the Strait of Hormuz.
Nope for $AKAM. But if you look at what’s needed probably CPUs/Memory #1. So your $ARM / $INTC / $AMD thematically (AMD probably higher beta to this company in specific). Then your Samsung / $MU / SK Hynix are your obvious memory beneficiaries. Component procurement is done through $JBL, which potentially benefits their own supply chain if they’re doing networking too.
$AKAM signs $11.6B compute deal with Anthropic for accelerated CPU workloads demands over 7 years. $AMD to $MU should be happy to hear this… Akamai ests. ~$5.5B of capex to service the $11.6B commitment. Including +$1.7B of 2026 capex specifically to pre-purchase supply chain components like memory. So much for Anthropic/OpenAI calling for an AI slowdown?
It’s mainly thesis tracking mode now since I layed out most of my ideas H1 from $INTC, $ARM to $MU. Or $SIVE to $AAOI or $AXTI or $NBIS Only two recent ones were $ESMT for legacy memory trade and $CCXI for humanoids but aside from that it’s just seeing if they get validated over time Stuff like large body substrates or CXL or MLCC with newer discovery, I’ve already published earlier on
I’ve actually entered positions in many tiny Korean companies recently… That actively supply memory, test, machines, etc. to $MU, $SKHY, Samsung, and others like $SMTC + US companies. It’s pretty interesting what you find in the $30-$250m range for optical components, CPUs, memory, and others that are inflecting due to AI. I don’t share these names publicly since risks/volatility is enormous. But one or two going from $40M -> $400m makes the risk/reward worth it for me personally.
Micron’s customer agreements, Analog Devices’ acquisitions, Ondas’ GATE deal and Baker Hughes’ power systems position them for AI…
I'm not having a fun day since I got sick today. But the bottlenecks are having a good time: $AMD +9.13% | $INTC +14.16% | $ARM +14.33% CPUs go brrr $SIVE +10.32% | $AAOI +3.39% | AMS OSRAM +24.61% Lasers go brrr $EWY +4.08% | $DRAM +2.83% | $MU +2.23% Memory go brrr $NBIS +4.7% | $CRWV +5.03% | $IREN +1.73% Compute go brrr Probably most material developments were CPU:GPU ratio expectations + CPU demand (from new AI releases). As well as optical developments from ECOC 2026 (as seen with $MRVL PR + others) Still a lot to catch up on.
The main duo $SKHY and Samsung are having a fun day. I'm still long memory (eg. $EWY / $DRAM ) since if capacity agreements extend 3-5 years... and your analysts model 2.8-3.3x 2027E. Risk/reward is attractive over time. But I think legacy memory a very interesting trade currently due to ASP hike potential.. It also just so happens these same companies procure memory from even smaller memory companies (that might have higher sensitivity)... So if you want to, you can track $PSMC wafer allocations, and find some interesting companies that likely replace $MU discontinued legacy memory through Alliance or supply directly to Samsung. Won't mention them on X, but just throwing out some research ideas.
@TheRayMyers why not $MU at 6.5x?
Will the shape of memory look not like the deep cyclical's of the past but more so something like this? Maybe $MU should be 13x NTM EPS, not 6x which it is currently. https://t.co/26sSfYz3yb
Wonder what the market might be thinking by giving $MU a forward P/E of 5x during the Situational Awareness liquidation? One possible shape that justifies a 5x p/e: https://t.co/24OatE4VXj
Micron’s AI-driven memory demand lifted Q3 revenue to $41.46 billion and gross margin to 85%, with $22 billion in customer agreements…
 Sharon McArd
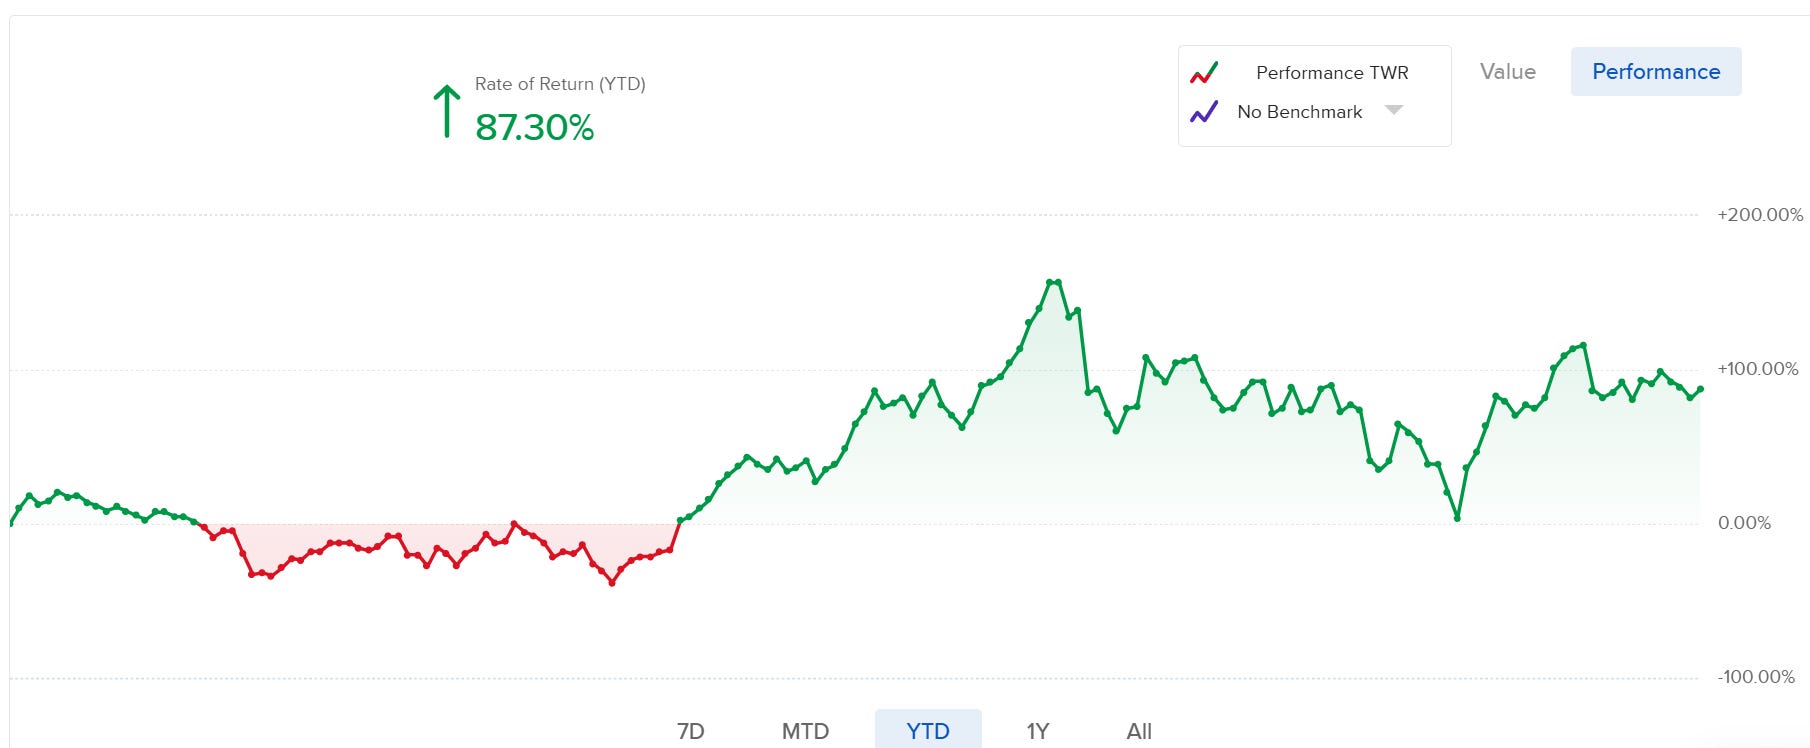
The portfolio allocates 75% to IBKR trading and 25% to an untouched Trading212 account, which holds SKHY, Micron and TSMC.
Custom logic-node base dies are shifting HBM competition from stack height to per-pin bandwidth, favoring high-speed PHY designers over…
 MU 2026-08-28
SK Hynix posted record quarterly revenue of 79.32 trillion won and a 76% operating margin, while trading below Micron on forward sales and…
 Prakhar Agarwal, CFA 4 clicks
I agree there are differences in HBM vs. NAND. I said we are “around” the peak of the cycle, with $SNDK much more at risk. Memory is an intensely cyclical business with a long history of booms and busts. Cyclical peaks are typically associated with double and triple+ ordering, as we are seeing today. Paybacks on new capacity are 1 year or less; capacity will come. $ASML is the primary limiter of capacity growth for DRAM/HBM, which is bullish for limiting supply growth in those markets. NAND is far less defensible. Memory is the biggest pain point in the ecosystem today and many entrepreneurs and engineers are intensively focused on solving this problem with innovation and other adjustments. De-speccing is already commonplace and memory pooling is coming. Finally, I am not saying it is time to short these stocks (although I am short some $SNDK). What I am saying is it is very poor capital allocation for $MU, $SNDK, etc. to be buying back stock at these multiples of invested capital.
@TheValueist No, the best capital allocation for both $MU and $SNDK would be to either dividend back cash or sit on the cash until the cycle turns down. Buying back stock at around the peak of the cycle and at (give or take) 20x the value of their invested capital base is not smart.
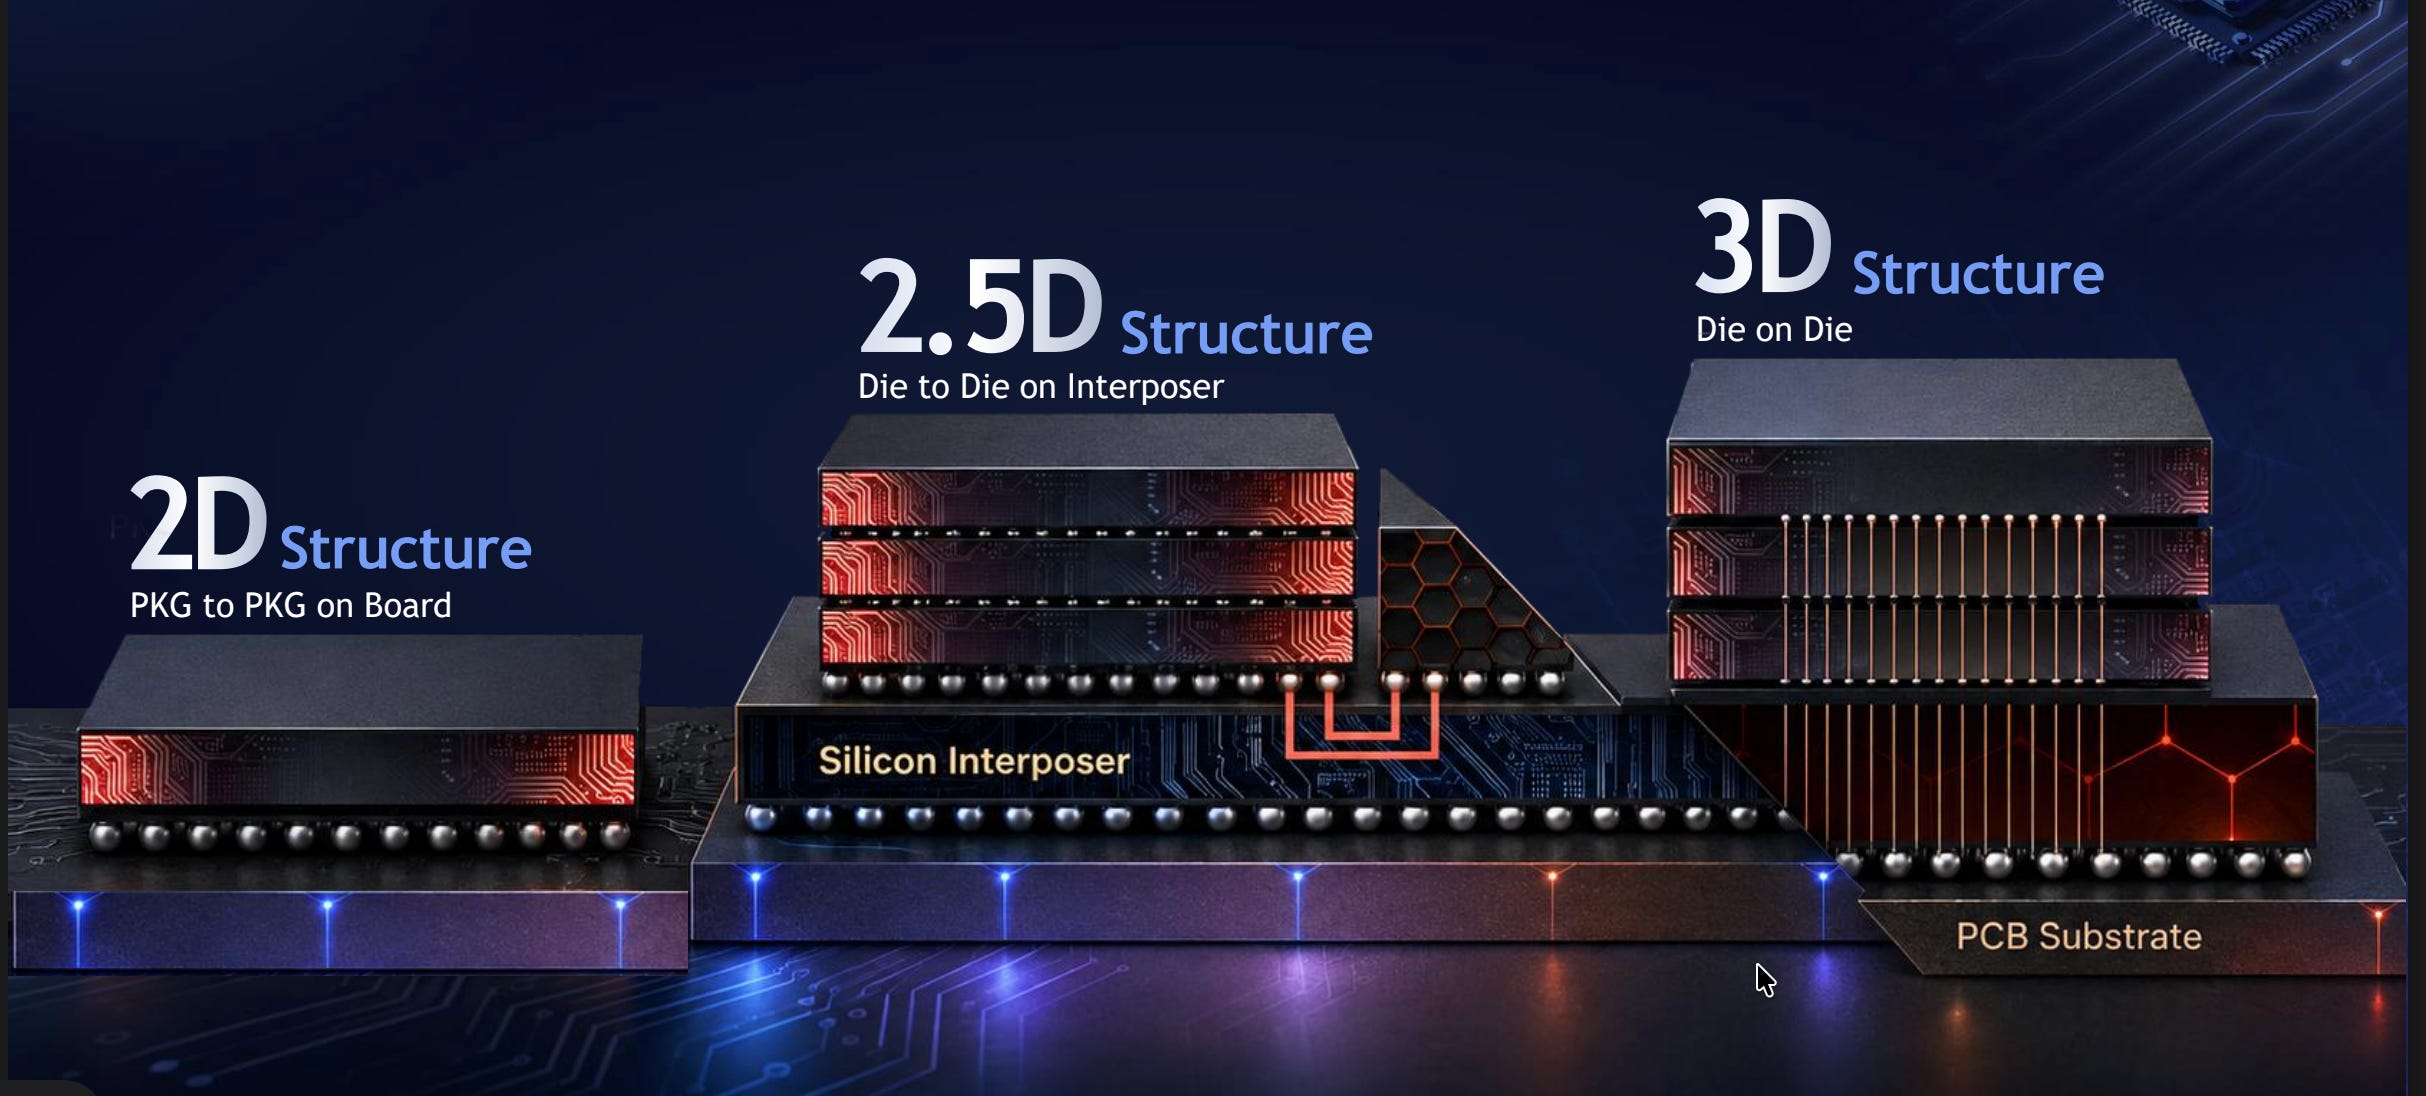
Micron, Samsung and SK Hynix set out HBM roadmaps at Hot Chips, with Samsung targeting custom logic base dies and HBM5 at 60GB and 6TB/s.
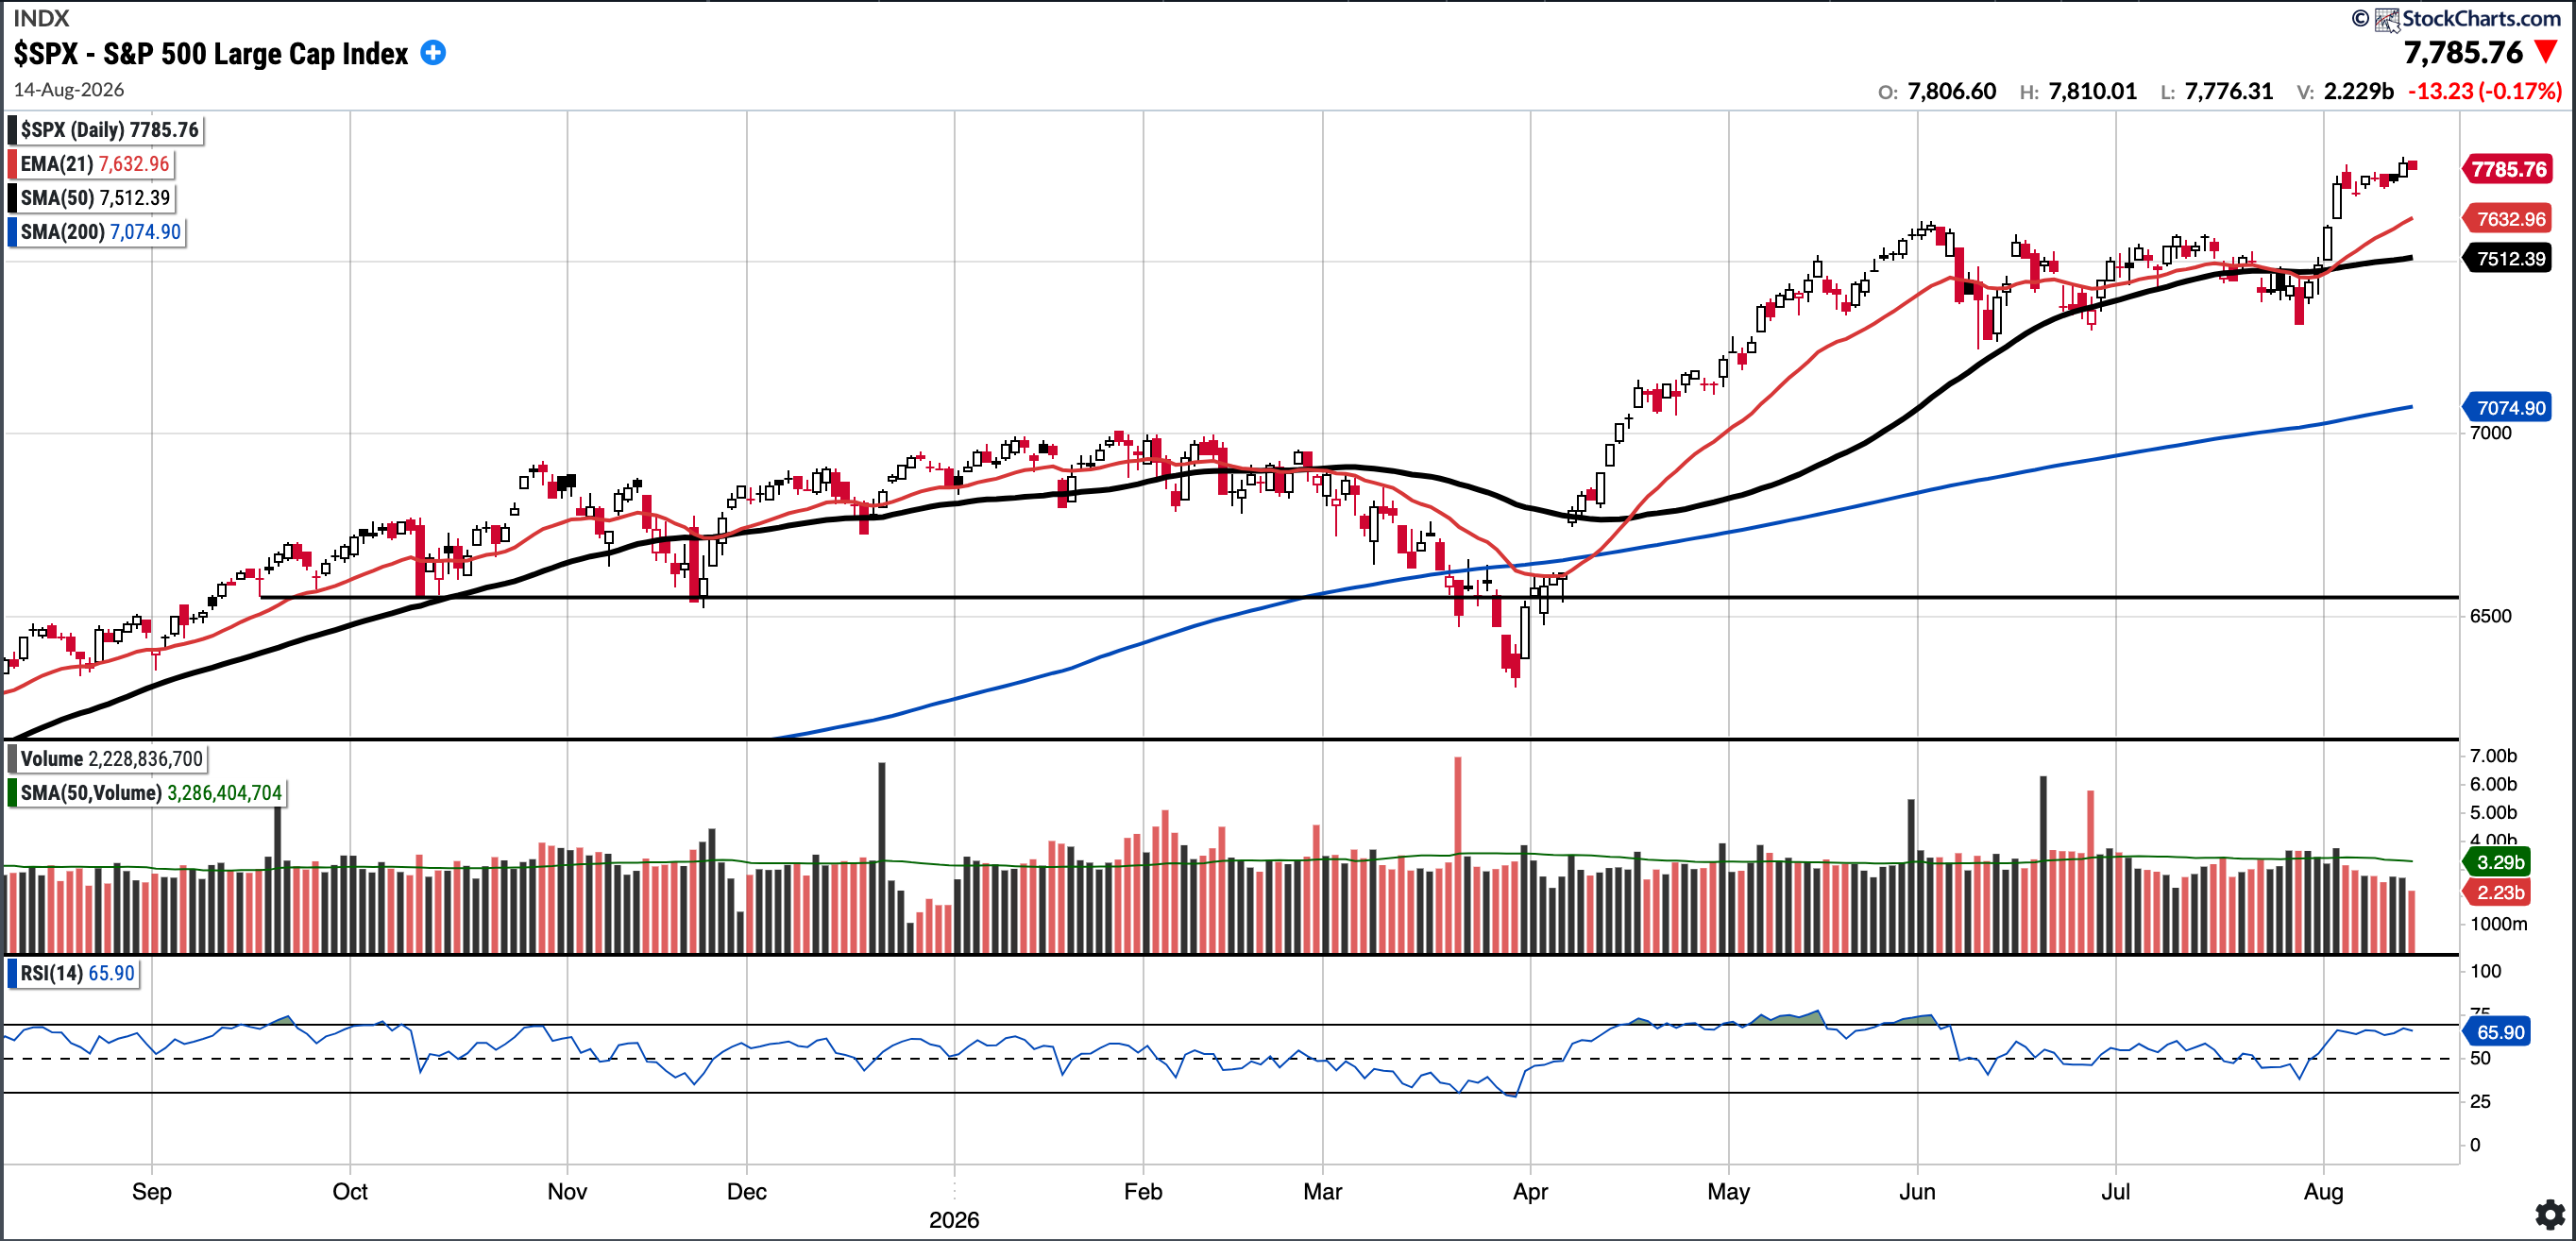
Week of August 17 tracks FOMC minutes, housing data and PMIs alongside technical levels for the S&P 500, Bitcoin, semiconductors, gold and…
I think what this guy @dylan522p does not understand is that receiving semianalysis institutional is just an information edge right now. Funds know they can short on publication and know they can cover lower- easy His negative pieces have been proven wrong more often than not, and when they’re right, the stories are often less material than stock moves on day of publication But he probably feels untouchable when he can take tens of billions off company values now, so he’s gonna typically act like a dick- but this type of edge rarely lasts long (and it won’t here) $AVGO $AMD $MU $NVDA
Letters that discuss MU.
Companies the stories above are also about, besides MU.