
BDC on X
I know I was poking some fun at $META last night but I think its a buy here in all seriousness. Not advice. But lots of ways to win in the end. Not advice, do own DD etc. I could be wrong.
NASDAQ
META
218 stories
$1.6T Market cap · 2026-10-28
I know I was poking some fun at $META last night but I think its a buy here in all seriousness. Not advice. But lots of ways to win in the end. Not advice, do own DD etc. I could be wrong.
Lam Research lifted its September revenue guide above consensus, while Microsoft’s capex cut reflects lease accounting and Meta’s AI…
$META’s platform engagement is incredibly robust and healthy with a deep product pipeline. The business is fine. I understand the capex debate, and clearly the biz is today more capital intensive, but I’m sure Zuck will make the right decisions in the end. Weakness is likely a buying opportunity.
...."but we might not take the offer bc we have all these reasons to use the compute internally even though we missed ad revs" (basically) $meta https://t.co/ozJ63qcFIL
The capex spend is mind boggling, but I held my nose and bought $META today around $590-600 I don’t how the AI bet will shake out, but I do know that… - $META Reels is sucking up engagement share from everyone, even $NFLX - $GOOG search refers are in free fall, which should benefit $META’s ad network - Zuck is the best owner-operator in the business who is willing to pivot if necessary - There are tremendous AI cost efficiency opps in core $META operations (Note: I have a long and fruitful history with $META and my family members still own their shares going back to 2013, knock on wood)
I think the worry is that the committed capex toward current RPO could be in excess of the demand that the market will ultimately finance. Demand is there now. But capital financing is getting more expensive and Frontier lab revenues better keep ripping. In $meta case they really need to pivot on their excess capacity
Remember the good ole days when covering internet meant you just needed to have a view on: - If $GOOGL Search was going to accelerate or decelerate and what the opex was likely to be - $META fxn ad revs...how big a beat? Opex? - $NFLX are they going to beat on subs? - $AMZN AWS to accelerate? How much? Margins? EBIT guide? - $BKNG room nights ! I started my career covering these companies and a bunch of other internets....at that time capex was not something we cared about bc it didn't matter. It was a simpler time.
@kermankohli GCP is baked into $GOOGL's price already. $META's cloud optionality is obviously not. You may prefer the known thing but its the unknown things that over much more asymmetry.
This is obviously unsustainable. The larger the gap, the worse the crash. Semis are printing cash now - but for a buyer and seller relationship to be healthy over a long time, everyone, both sides, needs to make $. I think $AMZN can make $ because their flagship business sells compute capacity and their capex ramp has funded more capacity to sell. $META can work because their flagship biz benefits from internal AI and they may in fact have excess compute capacity to sell - which is a positive pivot. $GOOGL is less clear to me. Their flagship biz is soaking up internal compute because new entrants in search, gPT for one, have $750B in capex earmarked - not to sell compute but to improve their own frontier capabilities. At the same time, $GOOGL's external compute biz is going to do great - but in this theater they are also competing with AMZN/MSFT etc. So for $GOOGL there's no pivot opportunity akin to $META and there's 2x the capex need as the arms race accelerates for both internal and external needs.
Meta’s planned cloud business and Moonshot AI’s Kimi K3 revived doubts over AI compute scarcity, driving chip stocks lower and exposing S&P…
WhatsApp named CRED founder Kunal Shah to replace Will Cathcart after Meta bought a 20% CRED stake for $900 million, signaling a push to…
Meta and Microsoft are framed as mega-cap opportunities based on business quality and valuation.
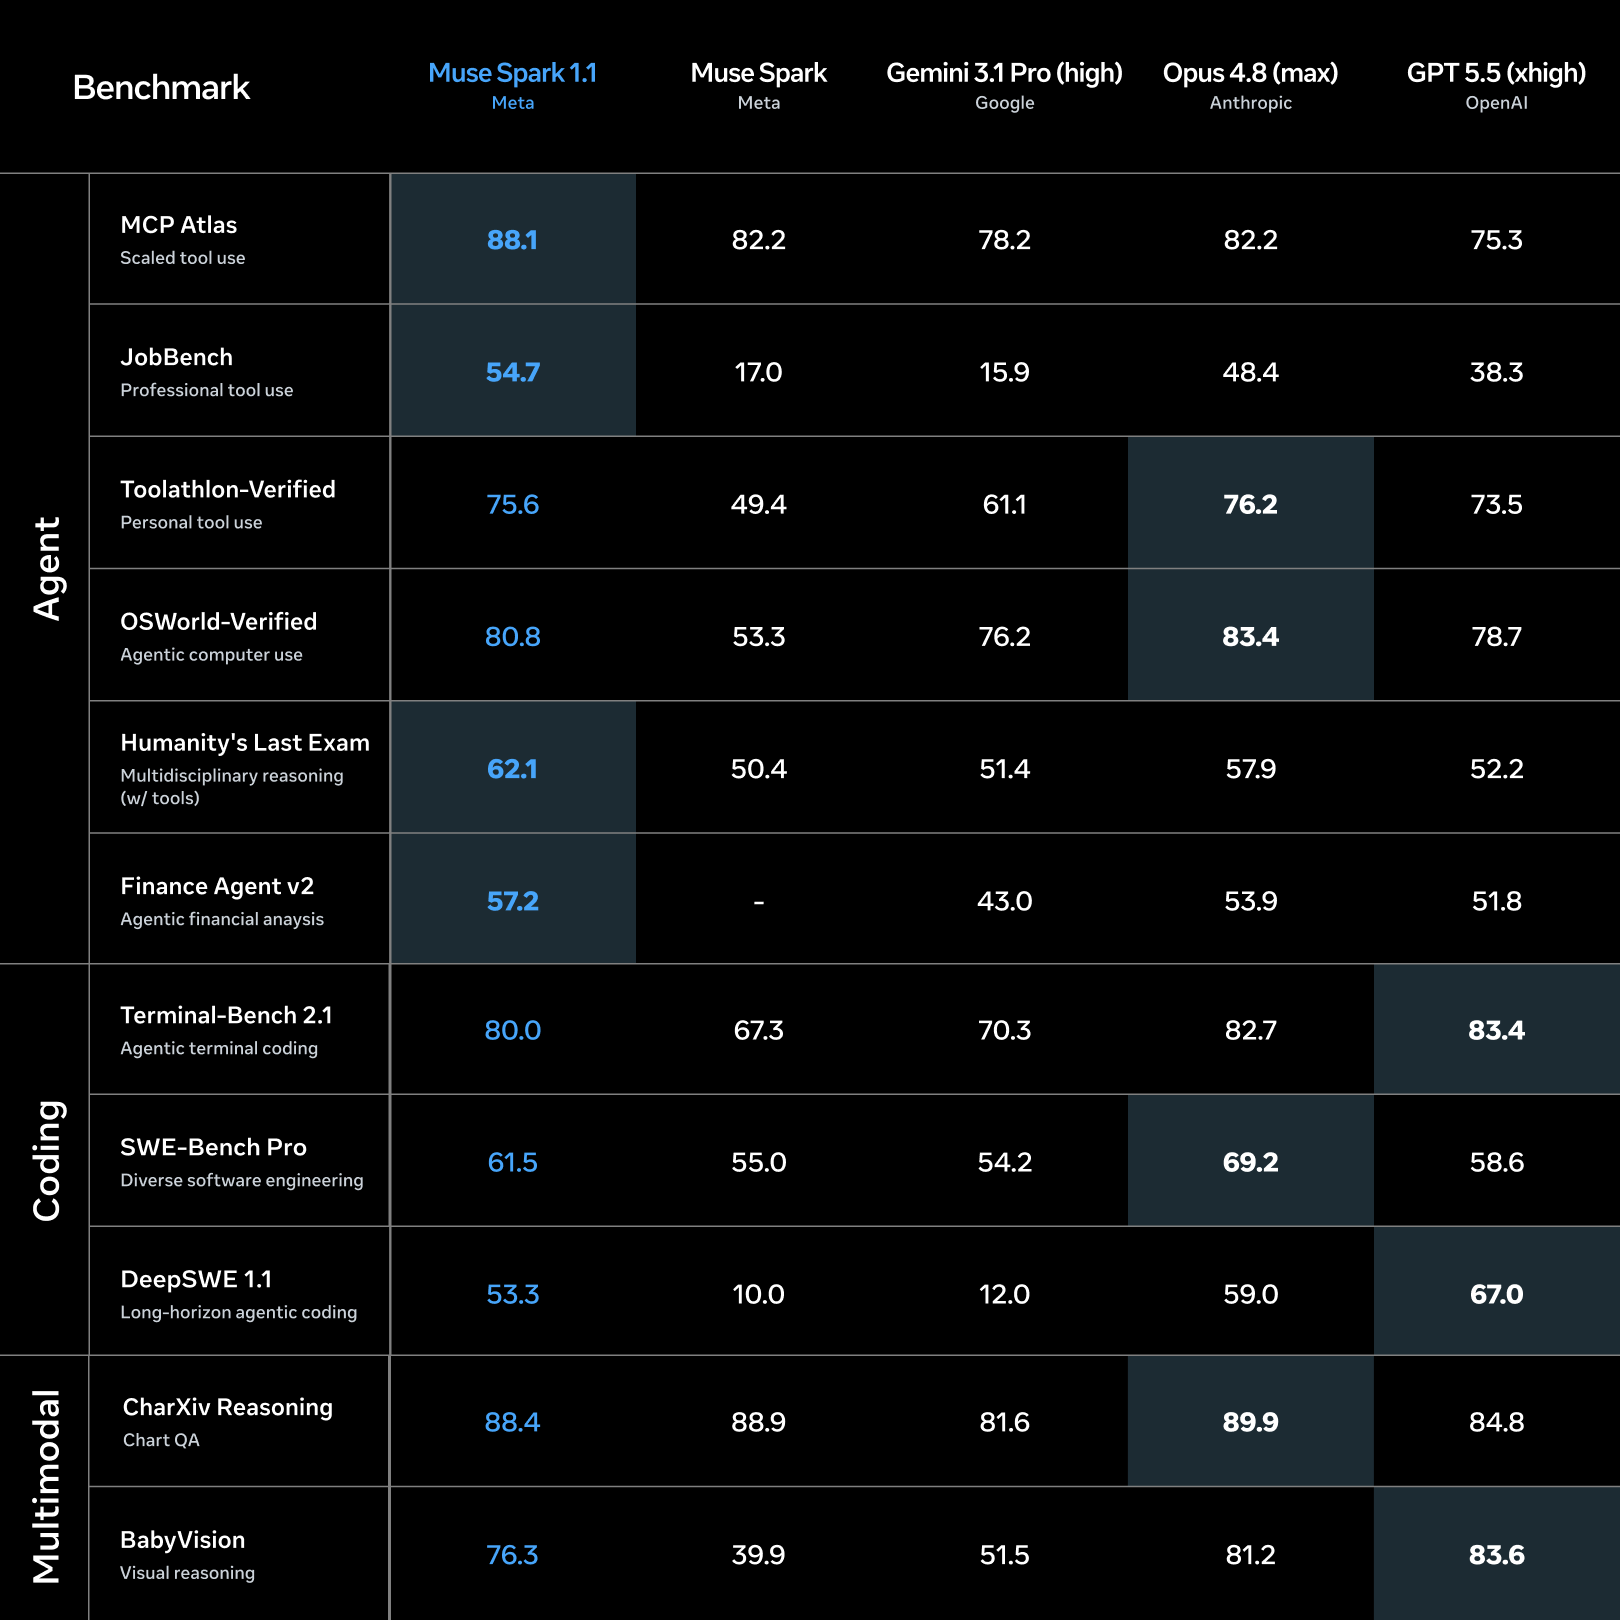
Meta’s Muse Spark 1.1 targets agentic enterprise work, backed by employee workflow data and 3,000 engineers building reinforcement-learning…
AI semiconductor stocks sold off as Meta’s planned compute business revived overcapacity fears, sending SOXX down 13% in two sessions and…
Meta investor bought a $350 December 2028 call for $26,901, preserving $28,123 versus 100 shares while betting AI and data-center spending…
$META probably can serve more tactical ads if you know exactly what each user is willing to put money on (aka is paying attention to) in the moment! https://t.co/9DnpLAIS4i
In the case of $GOOG, Adwords, which in my view is the greatest business model ever created is now being replaced by something quite different and considerably worse. In the case of $META, there's a long list. I don't share your view of the caliber of that business even while I recognize the considerable ad share gains they continue to get. The toxicity of the platform matters greatly if you're thinking of this business in any kind of longer term context.
I've been short $META for a while as I mentioned in previous posts. I'm fully aware that $META has been benefitting in continued shift of ad dollars away from $GOOG (I'm also short $GOOG) as we transition away from the SEO/SEM world to AEO/GEO. However, nothing can mess up a good fundamental story like poor capital allocation and Zuck and co. have demonstrated time and time again that they're willing to pull defeat from the jaws of victory. This latest effort to go and compete with Kalshi, polymarket, and even the traditional broker/dealers to get into betting markets is just another example. Betting markets doesn't represent the existential risk to the biz like AI does, why even consider getting into this now? Based on chatter about their upcoming AI model updates, it seems CAPEX at $META is poised to go way up, yet again. Will the street like that? I guess if their latest model is Mythos quality or better, maybe it will be tolerated. Maybe, but probably not. What is it about Zuck that he feels the need to be all things to all people? Does he not understand the strengths of his own business or is he worried about the duration of those strengths? Maybe it's just ultimate hubris. Either way, at some point soon he probably pulls the reigns back as the market continues to penalize $META for the absurdities of their capital incineration.
Bubble Spidey sense is starting to tingle pretty hard here! $GOOG and $META secondaries, silly SpaceX IPO valuation, Anthropic and OpenAI IPOs coming. Who is going to soak up all of this incremental equity supply? If investors start to balk, the music stops pretty quickly!
Is there a company that has employed a more "prisoner of the moment" approach to capital allocation than $META?
Meta’s Q1 2026 revenue rose 33% as ad impressions gained 19%, while AI-driven ranking and targeting lifted engagement and conversion;…

Meta grew first-quarter revenue 33% as AI lifted engagement and ad conversion, while data-center depreciation cut margins and personalized…
Meta’s 4Q25 revenue rose 24% as AI lifted ad performance, but 2026 costs are guided up about 41% and capex to $115–135 billion.
Meta’s 22% Q2 revenue growth and AI-driven ad engagement support its core business, while planned 2026 capex of roughly $100 billion…
Letters that discuss META.
Companies the stories above are also about, besides META.


