NASDAQ

Meta Platforms, Inc.

META

218 stories

$1.6T Market cap · 2026-10-28

@BlueDuckCap

BDC on X

Just surfacing this one to demonstrate we are not and never were $snap absolutists. We will go long and short and when facts and circumstances change our opinion changes too. And NO - Specs will not be a mass market hit this holiday season. Too expensive and awk form. But here's the bull case from here: 1. FCF/Share is the metric mgmt now focused on. By definition that requires fresh cost and SBC discipline. 16% hc reduction and flat share count already in place. $500mn in opex savings about to flow through. 2. Ads biz stable enough. 9% growth in Q2. Guide implies so decel. But ad checks stable vs Q2. Decent enough. Some progress on ad tech. Only needs 5% growth next year to hit our numbs. 3. Sub biz $1.2B rr, growing 85%. Needs 50% growth next year to hit numbs. 25mn paid subs, still well below penetration threshold of 7-12%. 4. Specs tech is real. 7k+ patents. Real use cases. What's that worth? $META or $MSFT or $AMZN could buy Specs for the patents alone and pay $2B and it would be nothing to them but all the call optionality which could incubate until form factor is mass market. 5. Lets just say Specs is worth $2B to a strategic buyer or partner. That implies $snap 7.5B or $4.5/ share. In this scenario then FCF/share at SNAP goes to over $1/share, easily. So 4.5x FCF on a business still growing revenue mid teens. @evanspiegel Specs are cool. But can't keep spending $500mn a year on them. Bring in a minority investor please and lets make SNAP stock great again. @IrenicCap
@MaiusPartners

Maius on X

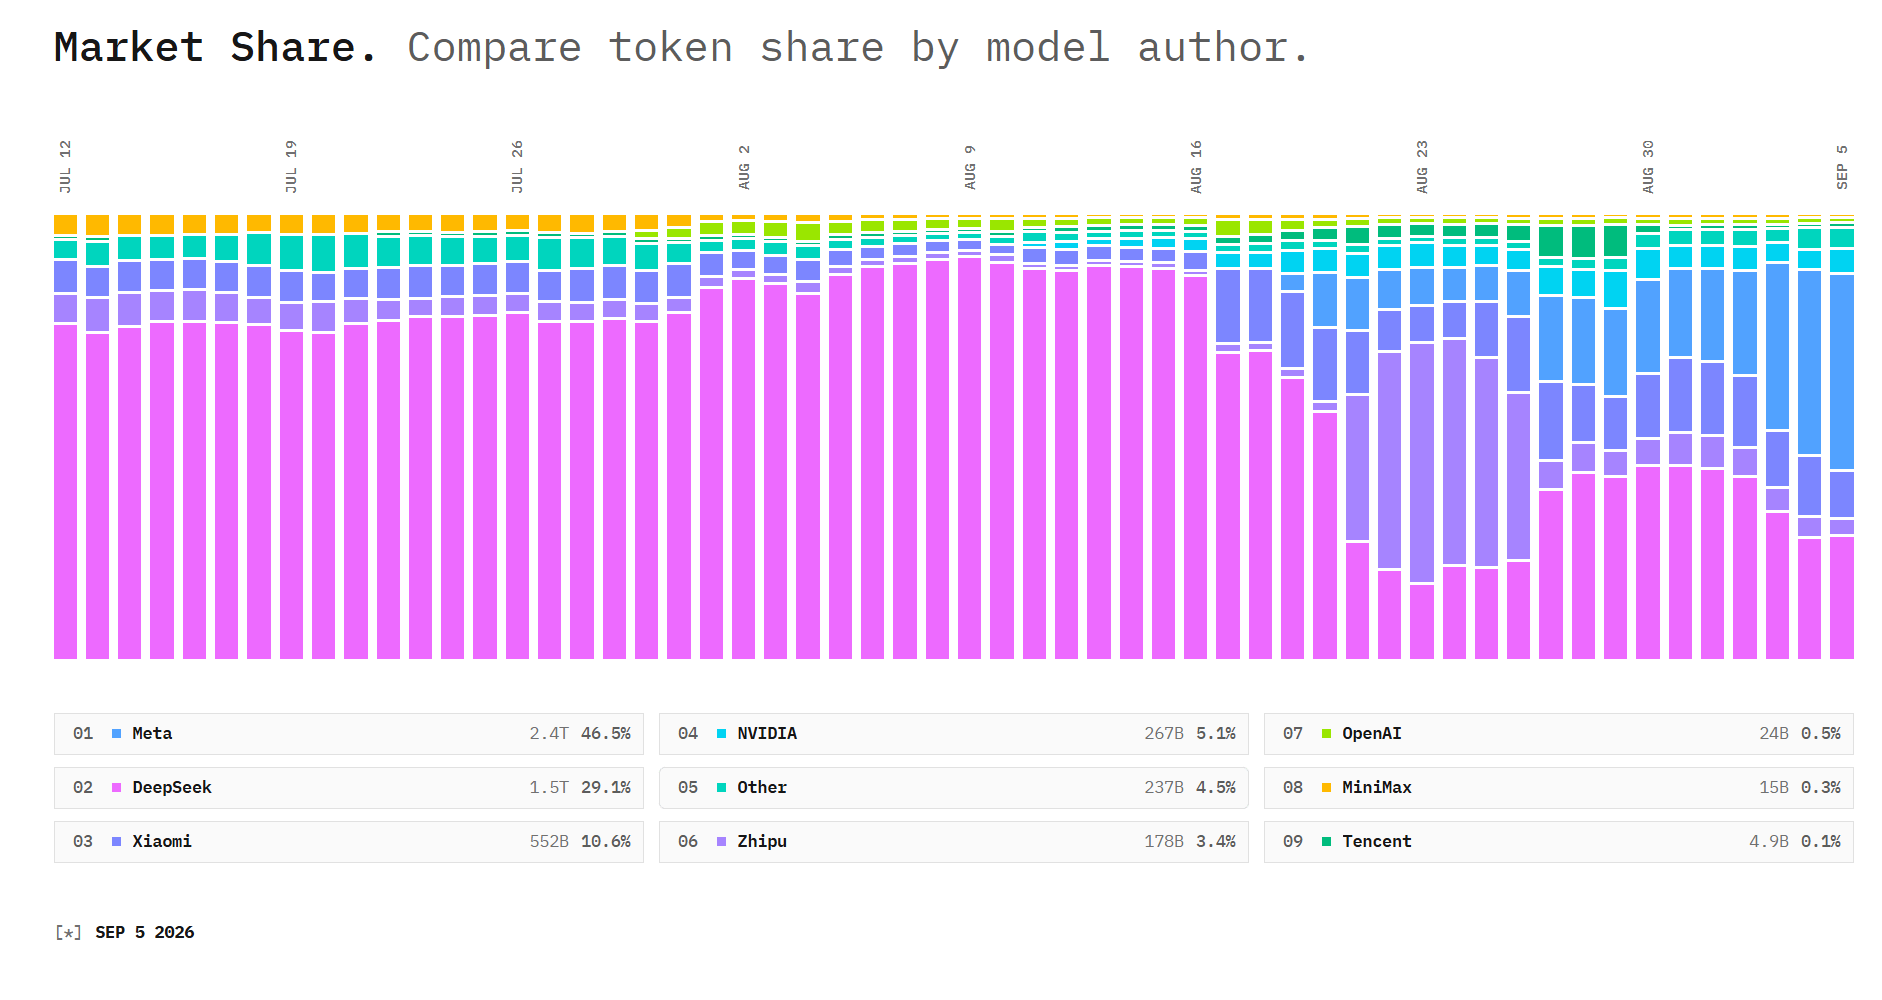
Full disclosure: Have closed out the Kimi idea to concentrate LLM exposure in what we think is the most mispriced remaining proxy on the list: $META. The fact that someone could have identified the potential in any of these LLMs, yet still lost money investing in nearly all of them over the last few months shows how difficult the game is for secondary market investors. And as capital flows into the sector increase, the game will not be getting any easier from here.
@negligible_cap

Negligible Capital on X

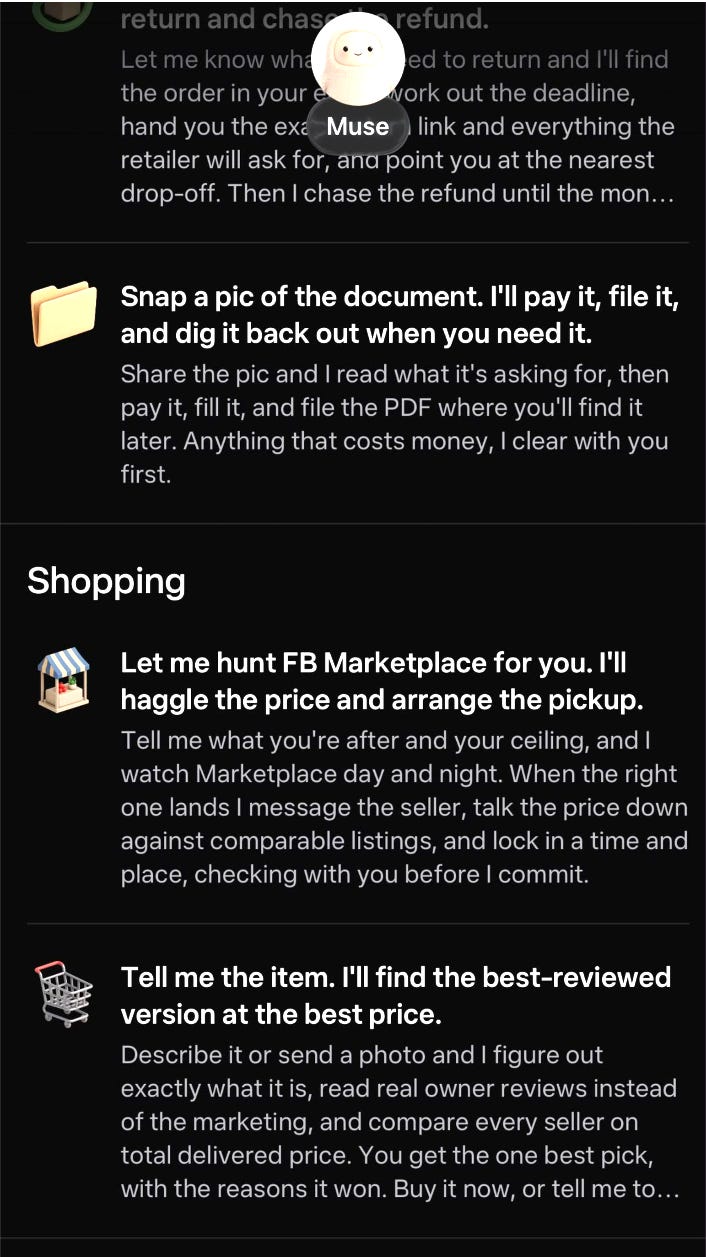
Sure $META Muse is good. Really good even. I had it go through my entire email last night and unsubscribe me from dozens of promotions and it only used around 10% of the free token budget But Instinct is also really good and didn’t need to pay Alex Wang a billion dollars to get there. And what happens when $GOOG releases their version? Being the first mover isn’t much of an advantage anymore. Nonetheless Meta Connect will be exciting to see in 2 weeks and expectations are very high for Watermelon

First Impression of Muse

Meta’s Muse personal agent connects multiple Gmail accounts, automates recurring tasks and offers free usage capped at 100 million weekly…

@convequity

Convequity on X

Open weight model to Nvidia ls kerosene lamp to Standard Oil. Free access to models = more demand for underlying infra. What's better is $NVDA can make this Lamp tailored and optimized for Nvidia stack such that users have to pick: Free model + $NVDA stack or Expensive model + Non-NVDA stack. The question is more about if $NVDA can deliver frontier open weight models or not. I am still a bit skeptical about it because it takes an elite dedicated team to do that and $META learned that hard lesson. And it also requires visionary mgt directly leading the elite team which $GOOG and $MSFT failed, while $SPCX realized it and back up again.

Investor Letters

Letters that discuss META.

Every letter that discusses META

Tickers on this page

Companies the stories above are also about, besides META.