
ECOC 2026: Important Product Announcements Around Optical Scale-Up
Teradyne, ams OSRAM, Lumentum and Coherent introduced microLED, VCSEL and DWDM products targeting optical interconnects for AI data-center…
Monday, September 21
Everything we published on this day.
104 stories — the front page that day →
Teradyne, ams OSRAM, Lumentum and Coherent introduced microLED, VCSEL and DWDM products targeting optical interconnects for AI data-center…
$PRTH +34% pre-market after Priore raised the bid to $8.05/sh. Def. deal now signed after ~10 months. With Priore controlling ~55%, this looks largely done. Two very lucrative trades for SSI: +30% first time around, then +40% after re-entering on the pullback. Full pitch👇 https://t.co/EBiGxWJZf2
$PDEX looks like a stable medtech biz with robotics upside thrown in almost for free - Largest customer extended through 2028 - Exclusive hardware partner for Zimmer Biomet’s mBôs platform - Recurring procedure-linked sales - CVRs could add ~$6.80/shr Pitch by @CaptnKirk13 https://t.co/SItNIqKB1K
Weekly Stock GEMs #14 features Vizsla Silver’s shuttered Panuco mine, Beasley’s debt deadline, Wolters Kluwer’s AI selloff and PlasCred’s…
ridiculous report. The way $NBIS does financing is much more sustainable than $CRWV and other neoclouds. There were also claims about falling GPU pricing but Nebius hiked rates by like 17-21% (oracle also hiked pricing for 4+ year equipment). Sum of parts is also something many analysis miss, Clickhouse would likely drive a lot of value to nebius. As well as Avride (with Uber) + their other companies.
Glad $AXTI also went up +12.4% today. It's probably being used like a chess piece in terms of Xi + Trump discussions right now. Since InP substrates would bottleneck the optical buildout by the US for AI. But if they have more control over pricing... I do think there's a lot of room for rerating.
$SIVE and $AAOI, yes for a 2027 timeframe. That's the nuance. Sivers you're coming on with 100M CW DFB laser capacity + 2 external foundries (maybe 300M in total), and all my supply chains mapping maps to larger hyperscaler suppliers. AAOI you're coming on with $471m transceiver revenue + 400K ELS units for 2028 timeframe. With hyperscalers + demand eating up all their capacity. There's just a $600m ATM which presents overhang near term. $NBIS already got re-rated but it's very positive upcoming for Q4 2026 (esp. with price hikes). Legacy memory like $ESMT + (some I haven't named yet) + regular memory names like Samsung, I do think will strongly outperform near term. And obviously CPUs names like $INTC $AMD $ARM as of recent.
I'm not having a fun day since I got sick today. But the bottlenecks are having a good time: $AMD +9.13% | $INTC +14.16% | $ARM +14.33% CPUs go brrr $SIVE +10.32% | $AAOI +3.39% | AMS OSRAM +24.61% Lasers go brrr $EWY +4.08% | $DRAM +2.83% | $MU +2.23% Memory go brrr $NBIS +4.7% | $CRWV +5.03% | $IREN +1.73% Compute go brrr Probably most material developments were CPU:GPU ratio expectations + CPU demand (from new AI releases). As well as optical developments from ECOC 2026 (as seen with $MRVL PR + others) Still a lot to catch up on.
The main duo $SKHY and Samsung are having a fun day. I'm still long memory (eg. $EWY / $DRAM ) since if capacity agreements extend 3-5 years... and your analysts model 2.8-3.3x 2027E. Risk/reward is attractive over time. But I think legacy memory a very interesting trade currently due to ASP hike potential.. It also just so happens these same companies procure memory from even smaller memory companies (that might have higher sensitivity)... So if you want to, you can track $PSMC wafer allocations, and find some interesting companies that likely replace $MU discontinued legacy memory through Alliance or supply directly to Samsung. Won't mention them on X, but just throwing out some research ideas.
We wrote more about TransMedix $TMDX and this insider purchase in an Insider Weekends article yesterday: https://t.co/XBXRgymODn https://t.co/eiKy8mMtAi
@aurelius28 @Investor_NICK_ Long $LLY. Was doing work on $HELP but it ran up a lot after the AtaiBeckley acquisition. We wrote about it recently after some insider purchases: https://t.co/8DZCtkcybL
Imagine what the next line of psychedelic treatments from companies like $HELP and $CMPS will do. Then there is Eli Lilly $LLY with its recent AtaiBeckley acquisition that closed ten days ago. They will be able to put their marketing muscle behind AtaiBeckley's lead candidate (if it gets FDA approval) the way Johnson & Johnson did with Esketamine.
@Investor_NICK_ @aurelius28 TMS and ketamine made a world of difference to their bottom line. Especially when companies like BrainsWay $BWAY were willing to finance the TMS machines for doctors. https://t.co/Y2bQqX0ALu
Copart’s $1.9B Bet on ACV Auctions: a Deep Dive $CPRT $ACVA https://t.co/Z3ICni26v1
Copart $CPRT just acquired $ACVA for $1.9B. The filings came out on the 17th, and I've spent 12 hours a day analyzing everything since. I read so much my eye drops stopped cutting it, had to switch back to vitamin A for the dry eyes. As usual, the reality is way more complicated than anything I've seen on social media so far. I break it all down, and what it means for my Copart thesis. Have fun. (Link in bio/below.)
Michael thank you for taking the time to write this insightful comment. I am not betting on one good looking quarter, however you may be surprised due to the short termism of Wall Street that could be all it takes to move the stock massively. I am not familiar with Hinge's new user experience, I do think $BMBL altering user experience will be good or at least eventually due to them constantly iterating and Whitney doing her best to keep her finger on the pulse of her audience. After listening to interveiws I am glad she is back
@KEDM_COM Pretty sure our most recent letter had liquidation in the mid 30s on 2027 roll fwd…. Stock lower. Nav higher. Insider buying won’t keep them at the controls. $CODI
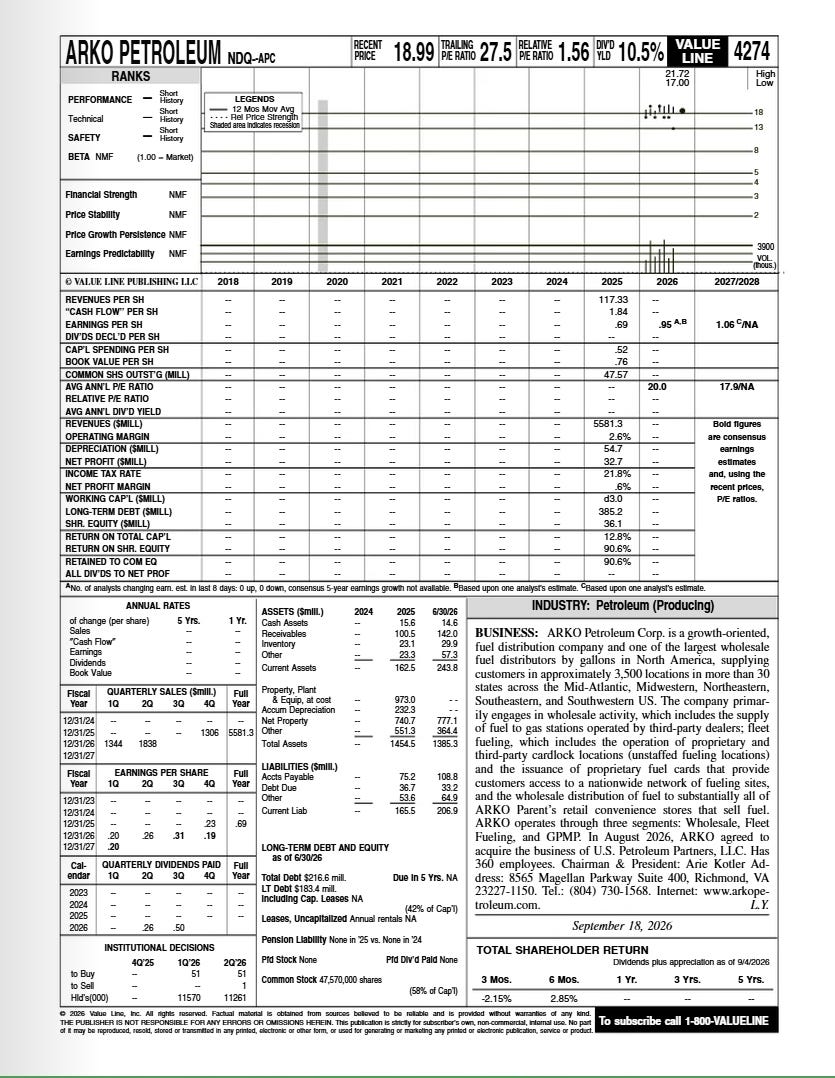
ARKO trades at 3 times estimated 2025 owner’s earnings, while its 73.6% APC stake exceeds its $473 million market cap.
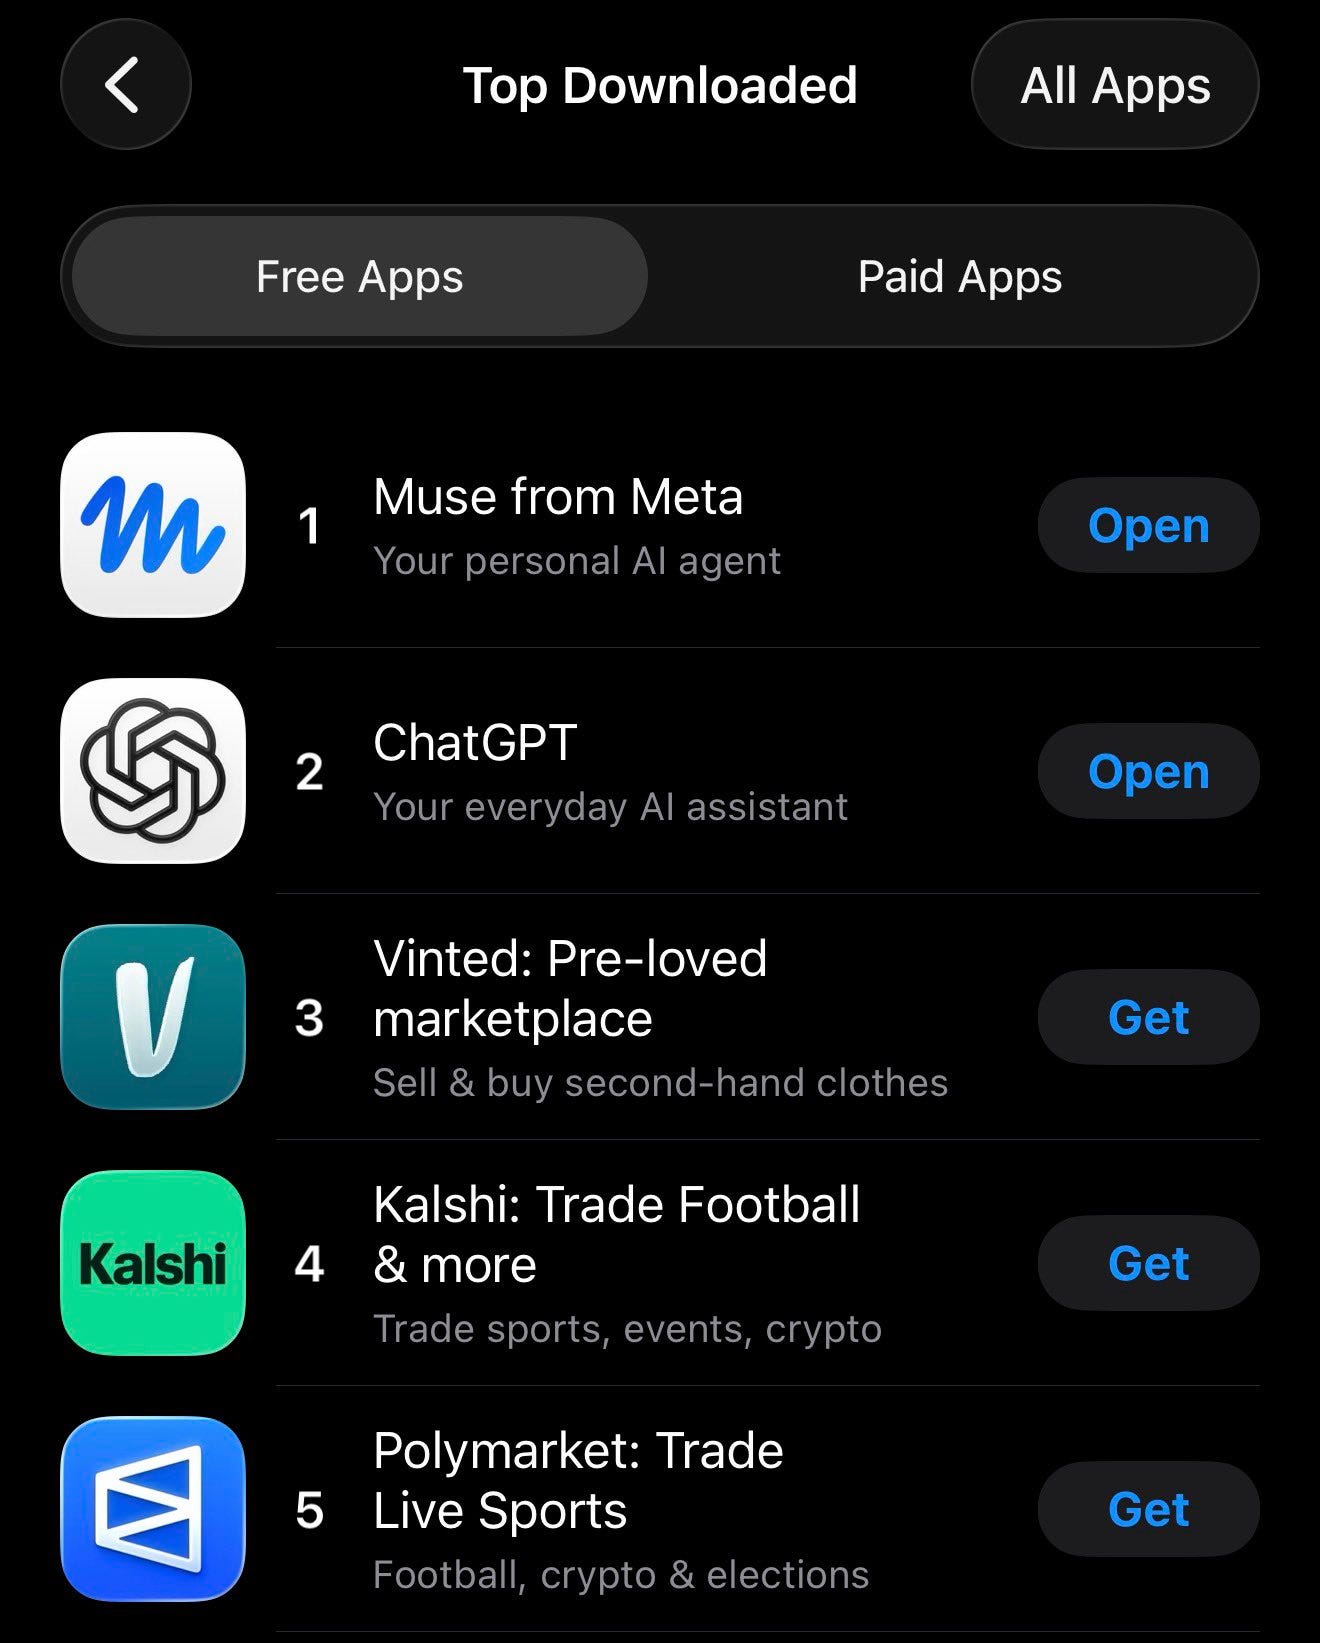
Meta’s Muse AI agent drove an 11% share surge, but OpenAI, Google and Apple could erode its early consumer lead.
$TPB starting to round trip here... way off its early 2026 highs haven't been following this since mid-2025, help me catch up on what's happening lately? https://t.co/HcsiMJXkuq
Wrote about this one recently and own some $MNRO shares + calls... Would be surprised if this isn't sold within next 12 months... https://t.co/ejb0AOkbQ5 https://t.co/g0WyapQYQg
A2Gold’s first Taylor drill holes returned 20.96 g/t AuEq over 1.5m and 209.4 g/t silver over 10.7m, alongside 141.10 g/t gold at…
Tempus AI’s Q2 oncology testing volumes rose 31%, while data and applications revenue grew 28% as its clinical data flywheel expands.
 Bay Area Ideas 2 clicks
*ALIBABA TARGETS 20GW OF DATA CENTER CAPACITY BY 2032 *ALIBABA UNVEILS NEW AI CHIP IT CALLS CHINA'S MOST POWERFUL Sounds like a whole lot more capex coming for $BABA https://t.co/iptpqpNPAE
The crazy thing about $GME is that the entire financial media has no idea the core business has turned around. Gross margins are at all time highs. Unit economics at the store level the best they have ever been. Nat Turner is one of the most strategic board members and is completely missed by legacy and dying media. The company owns 10% of eBay. Six years ago it was dying. And management is buying stock hand over fist. Ryan Cohen just picked up another $26 million today. I’ve been looking at deep value stocks for years. And this one has all the things I look for. See more here: https://t.co/W8q9tPCX8Y
Ethan Allen Launches Search for Next Chief Executive $ETD https://t.co/w9liHmiy2F
nobody, not even the companies themselves, know how agentic commerce ultimately shakes out. it’s way too early. $AMZN’s logistics, fulfillment + distribution moats don’t suddenly become worthless because an AI agent sits upstream of the transaction. the likely endgame isn’t winner take all. it’s partnerships, integrations + economics that give everyone a reason to participate. there’s a massive amount of money to go around.
@piques15 just say thank you for the $META alpha you chose to ignore at 9:35 ET this morning and go on your way. u wasting ur time here when u could be researching a trade for yourself.
Too early to know if Muse adoption fades or has staying power. But one thing is already obvious: distribution is an unfair advantage in mass market consumer products. $META
What's going down faster, $OPEN's stock price or Rabois' credibility as a geopolitical analyst? https://t.co/ThqR7rsRsO
A 12% pick me up from $META to start the week is not a bad outcome given these challenging market times, and highlights the importance of taking a global whole market approach in identifying alpha opportunities in LLM land given fast moving industry dynamics. https://t.co/4UxfR7yyum https://t.co/3UPWQZWZgZ
@hurrahsilver i do and that has zero consequence on today’s $META trade
@gr8tixx all good initiated the monday scouting options trade friday afternoon when $META was down $16
@VagabondInvests went long $SHOP today
Wall Street is missing the turnaround at $GME. They have closed 5,600 stores and gross profit per store has doubled. GameStop is also beginning to open select stores for the first time again. Management buying big in open market. See the full 34-slide deck presentation here: https://t.co/rExF9W5aVI
i say this not to be a dick, but to shake up a behavior i see trap so many retail investors: spending endless hrs buried in market noise, whether it’s fighting over theoretical $TSLA robotaxi fleet sizes yrs out or macro nonsense, while missing one of the biggest and easiest-to-spot single-day trade opportunities in yrs. $META
$OMER Comments from today's investor day with Novo. I think these words are quite bullish for Omeros and their partnership with Novo. https://t.co/ov8OF0gNlQ
@PetePete1832 @__thos not that it matters since i don’t sell anything, share ideas only out of kindness, and owe u nothing; but after dozens of research hrs this wknd i publicly shared my thoughts on $META within minutes of market open, which is also when i executed the bulk of my levered trade. https://t.co/IX2DBFn30s
@ylnuic The AWS win on agentic AI feels meaningfully larger and higher confidence than a theoretical future hit to retail that $AMZN has numerous ways to solve.
I published my article on $GME today and @ryancohen bought another $26.4 million shares of the company in the open market. This is on top of the $20 million he bought just a few days ago. Wall Street suits are sleeping on how much of an improvement GameStop has gone through and are drooling all over their big fat bellies instead of looking at the very impressive unit economics and demand as a collectible hub.
hell of a monday. congrats if ur in the same boat. what a time to be in the agentic AI / CPU biz. $AMZN $INTC $AMD $META
@jacobsimon2002 i continue to add to my $AMZN long, don’t need it lower but discounts always appreciated
@kurniAsept $CSU universe off -2% on a +3% $IGV today is fantastic.
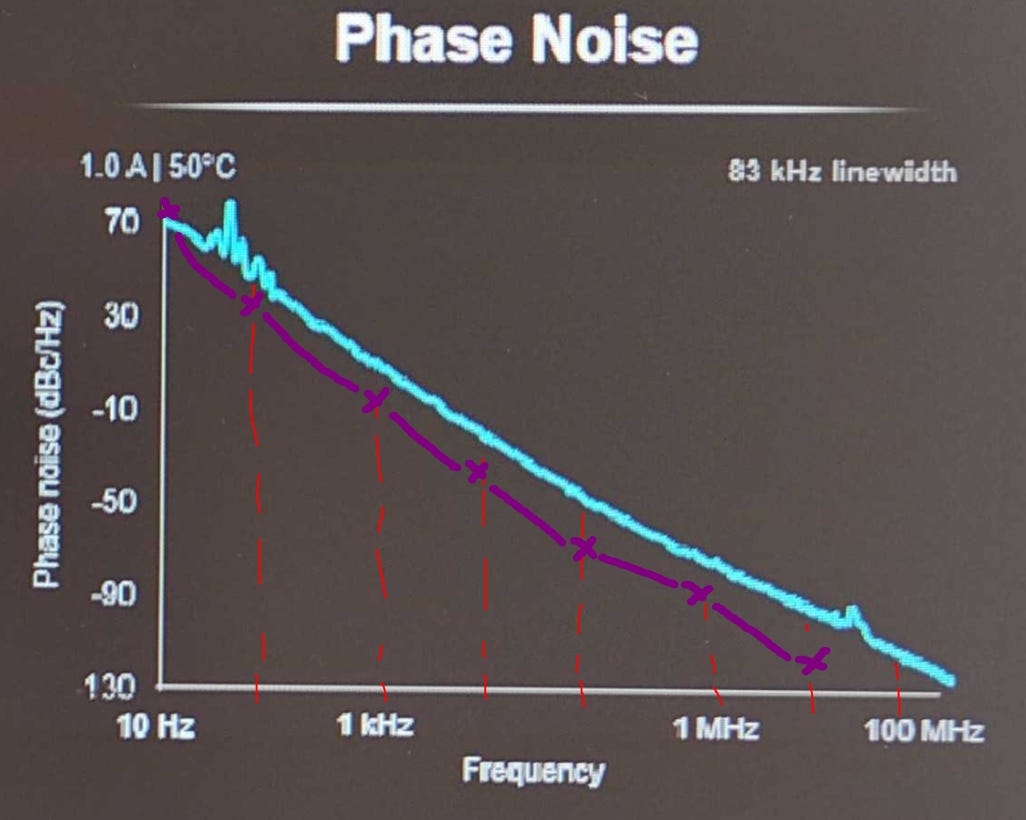
Coherent’s CPO/NPO laser misses 1 MHz effective-linewidth requirements, Irrational Analysis argues.
What’s the best non obvious disintermediation threat from Muse? Uber is obvious… I really don’t care about more than get me from point A to point B when using Uber/Lyft/Empower/Waymo/Curb etc. Muse seems bad for Uber bc $UBER almost always (in my exp) is more expensive. But I just habitually use Uber. Might as well just tell Muse to get me from A to B now cheaply? But probably something much better that hasn’t priced in this yet…
i don’t do that. it’s cheesy, irrelevant, and i dgaf. but for you, how about this: donate $10k to my charitable foundation, which supports pediatric cancer, leukemia and autism causes and from which i take zero compensation or economic benefit, and i’ll post my $META trades from Friday and this morning, currently up roughly $1M.
You read this deal from $NUAI and you think the stock should be up 33%? They just committed to a $200m credit line in which they only have liquidity of $68m. They are 100% going to need to raise equity and likely draw on this Macquarie facility. Also the deal is 5% equity dilution. Anyone buying today is about to get a rug pull from management.
Long $BORR https://t.co/W0xvygRBPr
Trimming a bunch of my $META. This move feels excessive and toppy. https://t.co/1Vbg7xWCg9
$WYFI meaningfully lagging the other Powered Shell Providers…. https://t.co/JWZPbrU54S
Long some $RSP calls. Breadth is completely washed out and implied vol seems cheap. Seasonality is favourable, feels like an attractive place to be long, and cheap on the options side. https://t.co/00h6Oyvnmk
$META has gained about $212B in market cap today, currently up over 12% For perspective, META's market cap has increased by about 22x the market value of $SNAP. Wild moves
@piques15 so many ways to win. we all good. my conviction in $META arrived at 2:30pm ET Friday, grew through the weekend, and resulted in my 2nd most profitable single-day trade in 20 years.
@masayoshisson would u rather be right in your head or win the trade? $META
This thread on $RFIL should help you understand their turnaround journey. It’s not really a data center cooling play. It’s much more: •Diversification of legacy telecom biz, so it’s less cyclical •Cooling solution at the edge for anything that houses electronics & components https://t.co/hj0TNHzR1P
Weird $HPQ 8-K dropped on assuming MSD PC unit declines in 2027 https://t.co/3FmtjYyqnv
@Wayne_Chien1 @AMCOracle It is one of 500 plus shorts. I am having a good day today. $AMC is however a loser for me
@RitzerAdam @valuedontlie $KBR stupid cheap
Feels like $NKE has lost its sole https://t.co/RUaFiVjpG1
ADW Capital continues to increase its stake in Compass Diversified $CODI, now already reflecting 14%. It's also good to see insiders buying shares on the open market. We flagged CODI a few weeks ago. ADW is pushing for a liquidation, stating that a wind‑down could unlock over $26 p/s, well above the current price. As a reminder, CODI’s share price collapsed last year on the accounting mess at its sub Lugano, forcing CODI to declare its 2022-24 financials unreliable. Lugano had hidden financing arrangements and misstated sales, inventory, and receivables. The fallout pushed CODI into forbearance, dividend suspension, reduced borrowing capacity, and eventually covenant breaches. The company has already questioned its ability to continue as a going concern; i.e., there is a good chance they'll liquidate.
@RitzerAdam @valuedontlie Motion Spin o might trade at a persistent discount to $AIT and dividend focused $GPC funds will punt it as well. Maybe there is a run-up to $140 pre-spin, but I’d be more comfortable adding sub <$120 here.
Apes are having a good time. $AMC is up. Hooray
@newmork Do the work. Pokemon is not slowing down. It is not 100% of sales either. When Pokemon fizzles out, One Piece is right behind them. Funko was a large part of $GME sales and then the next collectible replaced them when the fad fizzled.
$MNRO must buy all lubricants, non-lubes and service chemicals from Valvoline and can't market competing products. This is an in-depth partnership. Could there be a price increase? Sure, prices have already gone up this year quite a bit, but it won't be the price gouging type of supply that shops with no vendor will be facing. Two main points here. $MNRO is not in danger of running out of supply and if the price does increase, it won't be to the level of competitors without this type of relationship. I had a discussion with a manager at TiresPlus that points to exactly this. Prices so far this year have increased, but he said that the pricing he is getting from vendors he doesn't have a relationship with is multiples higher and he's going to have to pull the trigger with one of them within weeks.
In Austin trying $CAVA for the first time. Ngl it's pretty good. Not sure it's 80x earnings good, but it's good.
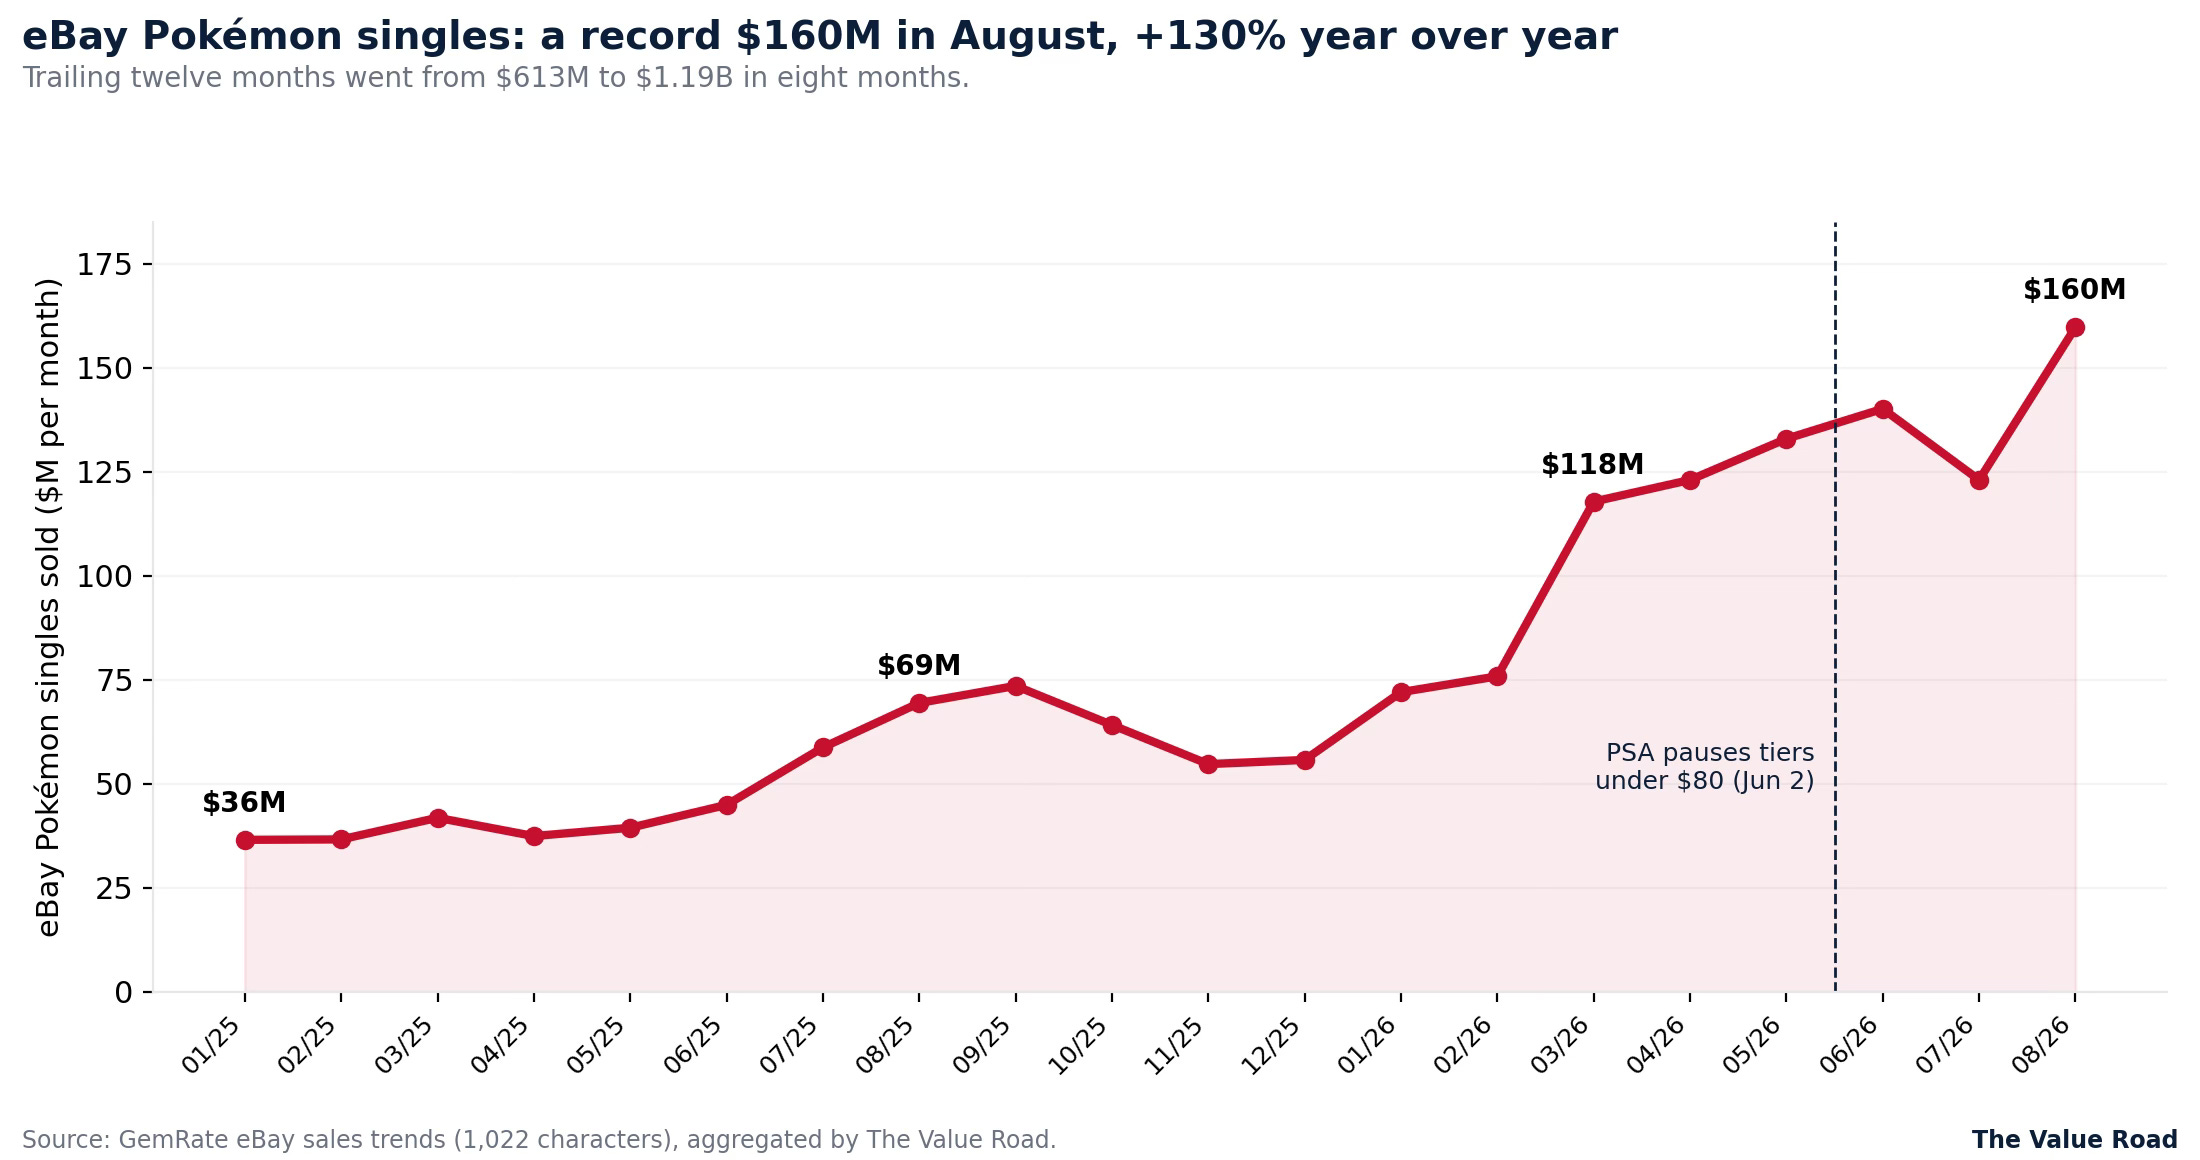
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store…
GameStop $GME is one of the most misunderstood companies in the entire market. Wall Street has left the company for dead. Every sell side firm has dropped coverage and zero hedge funds will own this because of the former meme stock hair. Now the stock trades dirt cheap with $5 billion of cash, $5 billion of ebay stock (10% of the entire company), $300 million of bitcoin and $2.8 billion of zero percent convertible debt. You are buying the core business for $4.1 billion. The core business that has completely transformed itself into a highly cash generative card store. Management has turned around the entire company and it is not a dying retailer anymore. It is a cash generative cash machine flipping Pokemon, Magic The Gathering and One Piece cards. Cards are one of the hottest markets in the entire world right now and Wall Street is asleep at the wheel. Unit economics are stunning. There are 1,600 stores in the U.S. $1.9 million sales per store. 45% gross margins at the store level. Four wall EBITDA per store of $580k. This is a four wall margin of 30.6%. There is very little capex and inventory is mostly financed by vendors and there is a float business with the trade-ins with in-store credit zero percent debt. Management is guiding to $650 million of EBITDA for the full year. They are sandbagging the number HARD. I am pulling data from ebay and GemRate and total Pokemon sales in August were up 30% m/m. The highest monthly sales ever recorded. In addition, the 30th anniversary for Pokemon occurred on September 16th. It was the biggest coordinated Pokemon event in history. I went to a dozen of GameStop's and local card shops and they were all sold out. Lines out the door. The phone ringing off the hook. Wall Street is completely unaware that GameStop is flipping cards in size and has transformed their business model. Finally, Q4 is the company's biggest quarter and there are more events for the 30th anniversary landing in the quarter. For the full year, I am modeling in excess of $850 million of EBITDA, $200 million ahead of management's sandbagged guide. Management likely knows this. Ryan Cohen bought $20 million in the open market, and other C-Suite executives followed along with numerous buys, just days ago. And then the company announced they will be reopening stores, for the first time in many years. The payback on reopens should be less than a year. I see the company trading at 4.7x EV/EBITDA, and over 90% of that EBITDA should convert into free cash flow, or a 20% free cash flow yield on the enterprise value. Wall Street is completely missing the story and asleep at the wheel with drool running down their big fat bellies. There will likely be push back on the ebay acquisition, but I encourage everyone to actually dig into the deal. It could be transformative and there are many synergies that Wall Street idiots are missing. Wall Street suits have no idea how the card market has been gamified and turned into a lottery ticket system that has become extremely addicting on apps like Whatnot. In addition, Ryan Cohen is an All Star capital allocator and operator, an extremely rare combination, and a platform like eBay is right up his wheel house. I built a website below that has a 34-deck slide, highlighting the thesis. Have fun and check out my analysis and website. I am long $GME and find the thesis asymmetric. https://t.co/Re7vRQ6uHG
And the only reason $MNRO has been hurt is because cost conscious customers have been postponing the services that make all the money (tires, brakes, etc). You can only postpone these items for so long. The demand never goes away.... This is a temporary industry issue and $MNRO is winning market share.
@EconomieReel @jeremie0117 There's not even one poll showing Flavio up. Betting market has gotten way over its skis... I'm long $NU and $INTR but Lula losing is not the default assumption to make imo... https://t.co/NlgYYmcXFu
We’re 3+ years into the AI trade. If you spent less than 10 hours this weekend researching $META ‘s Muse launch traction and mapping the market beneficiaries so you could initiate trades overnight or at this morning’s open wtf are you even doing with your time as a trader?
@valuedrift I was watching this and $GEO rally for months and finally put the short on myself... absolutely silly up here.
Working with Belarus? Interesting. $KYIV https://t.co/VnIEmBNVjw
$KBR even cheaper now. https://t.co/TrbW3Yw5S2
AMC is refinancing essentially its entire debt stack at once: $2bn of bonds, an $850mn TL, and a $1.12bn 2L. 6 years ago (and for a few years after), this company was on the verge of bankruptcy, saved by meme stock equity issuance and flexible debt docs. Now it's pitching a refi on the back of a RECORD summer box office. Pricing will tell you how much of the rebound the market believes. $AMC $CNK
ROTE ⬆️ Costs and RWA ⬇️ Bursobank growing 7.1x forward earnings and 0.9x TBV I’m $GLE ful https://t.co/fFzBcgxp3d https://t.co/cfAa7GcsFl
Pfizer offers a 6.22% yield at 9.3 times 2026 consensus EPS, backed by cost cuts and 5% operational growth in its non-COVID portfolio.
 Steven Fiorillo 1 click
Arcturus Therapeutics is advancing ARCT-810 for OTC deficiency after phase 2 data normalized glutamine and ammonia levels, with $191.5…
 C. C. Abbott 1 click
Nice call - 100% agree! Having an exclusive retail partnership with Valvoline may make them even more attractive to a potential buyer now. Did you listen to the CEO speak last week? He know his stuff and they are already winning market share... What also makes this interesting is that not only does a sale to Mavis (who bought Pep Boys) make sense, but so does a piecemeal sale since $MNRO has very distinctive brands in different geographical locations.
Saw a post that "non-AI" stocks have nearly -1 corr to the market. What are some examples of good companies getting left behind by capital flows? Maybe $OTIS at 15x '17 P/E with ~80% of EBIT coming from elevator maintenance? Any other good ones with a 10 year time horizon?
I personally would slightly prefer if the $CENX Oklahoma smelter gets delayed or even cancelled, as it means more capital return, especially at today’s prices Can’t wait to see run-rate EBITDA in Q4 https://t.co/KTvGLbVKhp https://t.co/CD1XFwm9Eu
Corteva will spin off its Pioneer seed business, Vylor, on October 1, leaving crop protection RemainCo that could trade at 6.5-8.5x 2026…
@JerryCap Of course. Although I would think you'd like $BKNG and their mngmt as well.
Local oil change companies using vendors like Halron which get their supply from Shell are running out of OW-20 (includes Walmart / CostCo). Huge benefit to $MNRO who sources directly from Valvoline through an exclusive retail partnership. Soon places like TiresPlus, etc will have to implement massive price hikes that will drive market share for $MNRO. Really interesting situation especially since Ichan has economic interest of 33% in the company (16% share ownership / 16% swap agreement) and recently sold the inferior Pep Boys for a valuation that would price $MNRO at $25+. Now that Pep Boys has closed - wouldn't be surprised to see $MNRO get an offer very soon especially given their prime opportunity to take advantage of coming motor oil shortage.
@JerryCap 1) ASML, Hyperscalers (GOOGL, AMZN?) 2) $FOUR, $GPN, $BKNG? 3) $CSU
$AXTI - Another chance to short it.
Intel's $16.1 billion Q2 revenue rose 25%, while potential SK hynix foundry collaboration could lift U.S.
 Sharon McArd 2 clicks
how i find out Polymarket has 9x leveraged stock trading now. $META https://t.co/ITCS41Fo90
$TMUS, $VZ, $T, teleco's continuing underperformance today after getting sold hard last week. GS last week blamed Instinct and Muse for the selloff given their ability to negotiate and cancel bills: "While US telcos traded down (TMUS -5.5%; AT&T-2% & VZ -3%) on concerns on X chatter around Meta’s Muse and rival AI agent Instinct has focused on their new ability to make outbound calls to U.S. businesses, including negotiating phone and cable bills on behalf of users. This could become a risk for telcos because AI agents can wait on hold, escalate with support teams, switch users to cheaper plans, remove add-ons and claim credits at scale—potentially increasing pressure on ARPU, retention economics and customer-service costs. The same risk applies to European names as these AI assistant role out. But its NOT just telcos as other industries could also face pressure -industries most at risk are those with recurring bills, negotiable pricing, confusing add-ons, high churn incentives and customer-service friction—including cable/broadband, insurance, utilities, banks/credit cards, subscriptions, travel, healthcare billing, retail returns, auto leasing and gyms. If AI agents can persistently call, wait on hold, compare offers, cancel services, claim credits and renegotiate terms on behalf of customers, companies that rely on inertia or under-claimed discounts could face higher retention discounts, lower add-on revenue, more support volume and weaker pricing power. PS – have been using Instinct for a week of so – its pretty impressive once you get past the hesitance of giving access to parts of your life (not brave enough on a bank account) – book restaurants, tennis courts, highlight must read emails – its also picks up inaccuracies of emails and sources what is inaccurate." - GS Sean Johnstone
$META #socialarb https://t.co/0NrrcIczKj https://t.co/XV1iNrv3US
@InvestByRS Yes. Initiated a levered long $META position late Friday. Added substantial leverage at market open today.
Jassy’s gonna need to figure it out. The agents are coming - they’re not going anywhere, and they want to shop on $AMZN. Figure it out
Bernstein on CXMT: “We believe a new fab of max capacity at 100k wpm is being built in Shanghai now, & is due to begin production early next year. There is no mention of this fab in any company filings” Models capex rising 70% YoY through ‘28 to $35B CXMT capex is $ACMR revenue https://t.co/rQXi6eh7PX
$META Muse https://t.co/6kIAS8EU9B https://t.co/XV1iNrv3US
$META Muse is a textbook Social Arb setup as early traction is a genuine surprise. $META is the obvious beneficiary. The off-radar derivative: $AMZN. Meta already uses Amazon Bedrock at scale and has committed to tens of millions of AWS Graviton CPU cores for its agentic AI workloads.
$ACMR seems to be the simplest way to play the inevitable CXMT/YMTC ramp https://t.co/NlvTBGCZSr
@BetterIRR Q: Where does $CODI trade if they execute a major asset sale before year-end? https://t.co/JhnAKOI3hl
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
$BTC breaks out -- moving up about 9000 in a few days. Selling here and will likely repurchase on a pullback. https://t.co/89TnvZWmE2
$BUG $CIBR https://t.co/mp7jCJtmB4
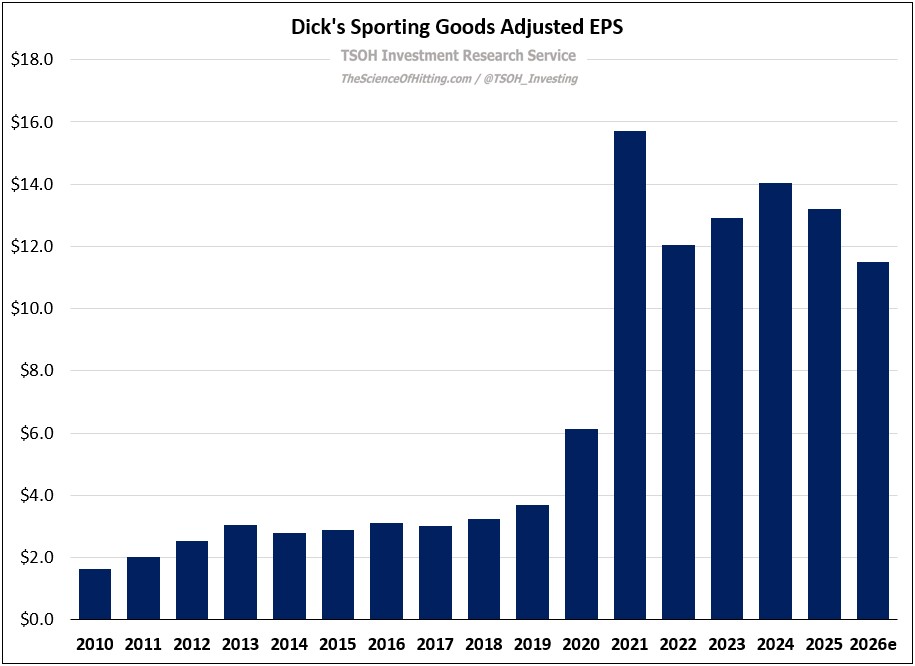
Dick’s Sporting Goods’ $2.4 billion Foot Locker acquisition nearly quadruples its store count and adds international exposure, risking a…
Goldman Sachs posted $20.98 in Q2 EPS on $20.3 billion of revenue and raised its dividend to $5 per share, with M&A and issuance activity…
 Mike Zaccardi, CFA, CMT 2 clicks
Latticework’s weekly briefing spotlights discounted European assets including Barco, Bolloré, Brookfield and D’Ieteren, with catalysts…
Genuine Parts targets NAPA network improvements, Motion’s industrial recovery and a 2027 Automotive-Industrial separation to lift sales,…
 Value Capital Research 2 clicks
Bioventus uses established-product cash flow to cut debt and fund launches, while its 2030 term loan extension and lower margin support its…
 Equity Eagle
