
The Week That Was
August payrolls and soaring diesel prices strengthen the case for a September Fed hike, while HBM costs are compressing AI hardware gross…
Sector
Everything our editor has picked under this sector, best first.
197 stories
August payrolls and soaring diesel prices strengthen the case for a September Fed hike, while HBM costs are compressing AI hardware gross…
He's NOT going full Big Short here but @realsteveeisman walking a much closer line than in the past. "A demise of OpenAI could push the US into an immediate recession." He recommend low vol and P&C ETFs in that scenario. $LVHD $SPLV $KBWP https://t.co/mx8SxT9iRd
@dirtcheapstocks I look for companies like this for my inflation basket. $INFL seems pretty good to me for a lazy version. https://t.co/OkhW0QroSL
During the Iran dip initially there was a lot of behind the scenes AI progress. And so when there was finally relief — in the form of the initial detente -> MOU — things totally ripped. I feel like with these insane $NVDA and $AVGO guides we are almost in this spot again. Hedge funds have delevered, momo has been historically crushed, Warsh has said a lot of hawkish things, and the next FOMC the market expects a hike. Obviously the big overhang is yields. But it feels to me like for all the discussion of guidance/rates/the yield curve… really the bond market just wants the war to end or at least be paused. I am not so sure that the US has no power to at least have things significantly deescalate when it wants (maybe into midterms). It’s like, we can “lose” a war, but Iran can still recognize that with time its leverage will decrease, its economy will be destroyed further… like it seems a bit naive just to think that because the war is going badly, Iran has no desire to see it wind down. This latest tit for tat for example hasn’t been that crazy. So IF you think that we get some sort of detente, which is really what I think yields need — are we not kind of a coiled spring here and running back a similar setup to when things started ripping?
$KLAR seems too easy… obviously recession=write-offs, but the value proposition to consumers would strengthen? What am I missing?
$QXO finally in my valuation zone, acquired shares this afternoon. Rates present a challenge, soft commodities surging and geopolitical could further stress inflation/yields but you usually do not get deal when everything is firing on all cylinders
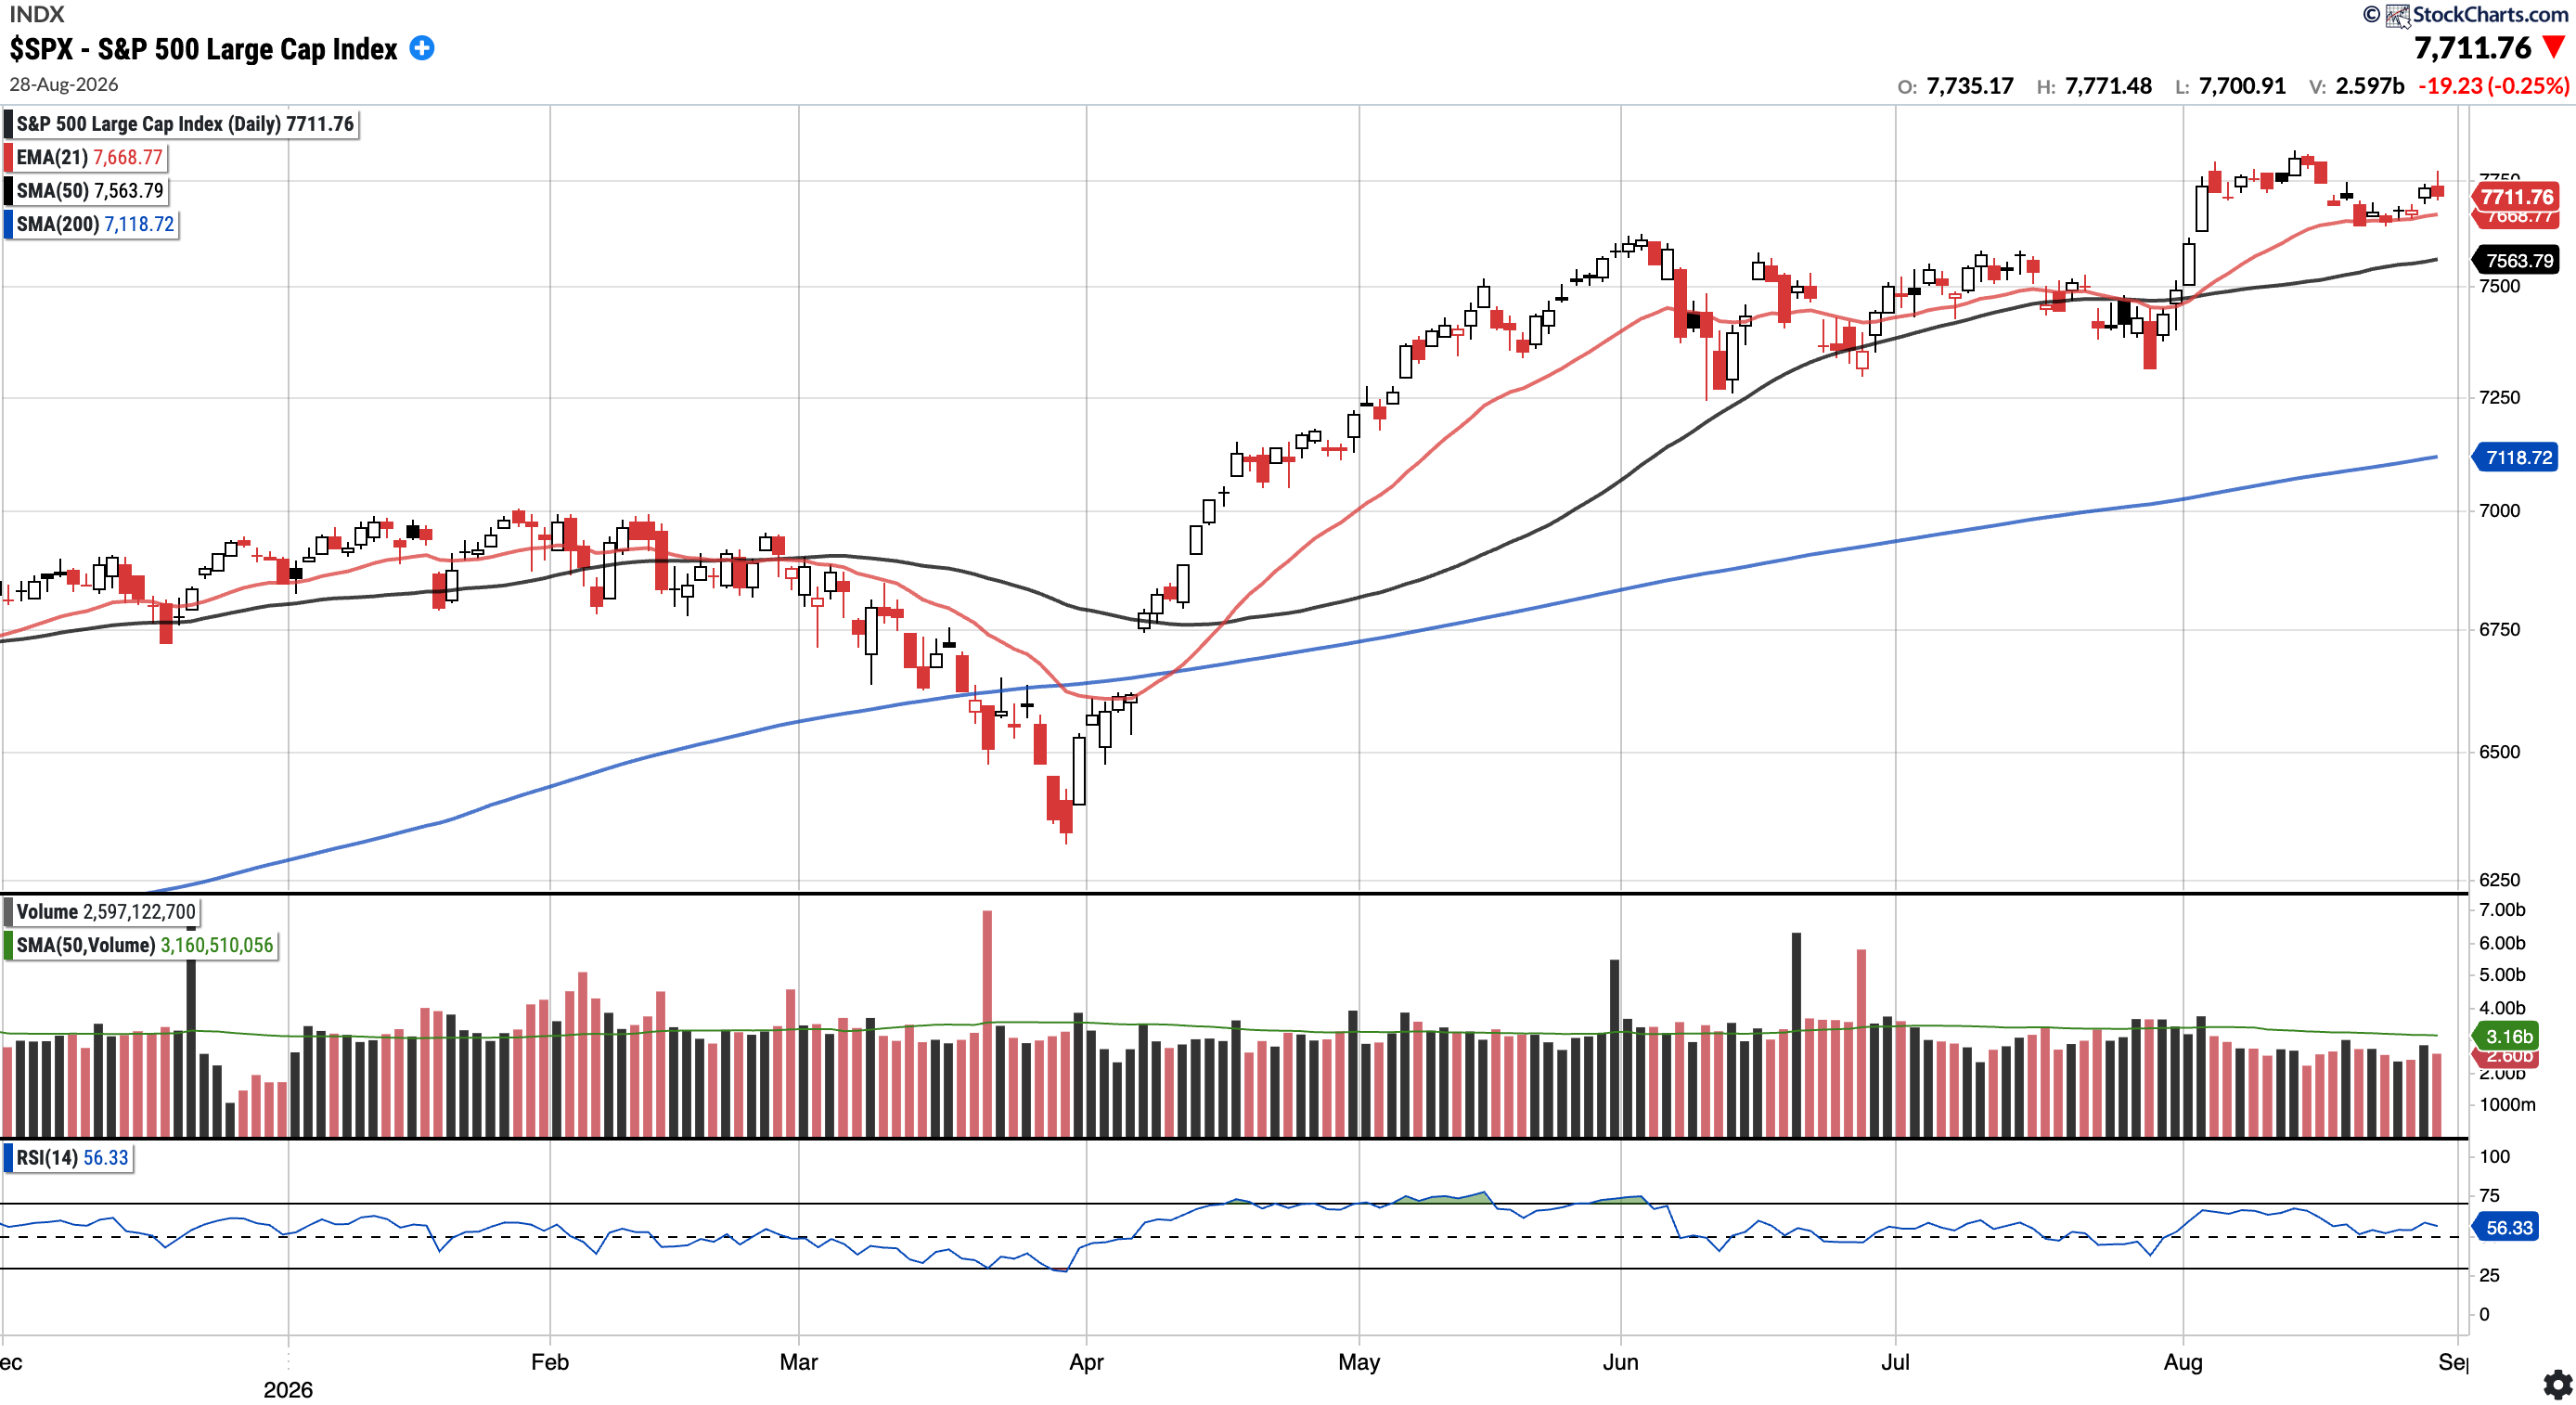
The week of August 31 features U.S. manufacturing, jobs and services data, while the S&P 500 and Nasdaq hold above key moving averages and…
@ryanTesling @elliotrades worry isn’t something i do often. a rate hike is a known risk investors won’t like short term, but it changes nothing about my larger $AMZN thesis.
@davey_juice @ThainRos $EWZ might go lower. I don't have a strong opinion on where big components like Vale and Petrobras go, could be down more. I think $INTR and $NU will keep growing fast enough to offset macro jitters.
@davey_juice @ThainRos I own a lot of $NU and $INTR but think Lula is going to win, so that's not ideal. Flavio polls look a little better, but he's still a bad candidate. Colombia only went to Abelardo by 1 pt. Lula is incumbent, more popular than Petro, and their electorate is more leftist.
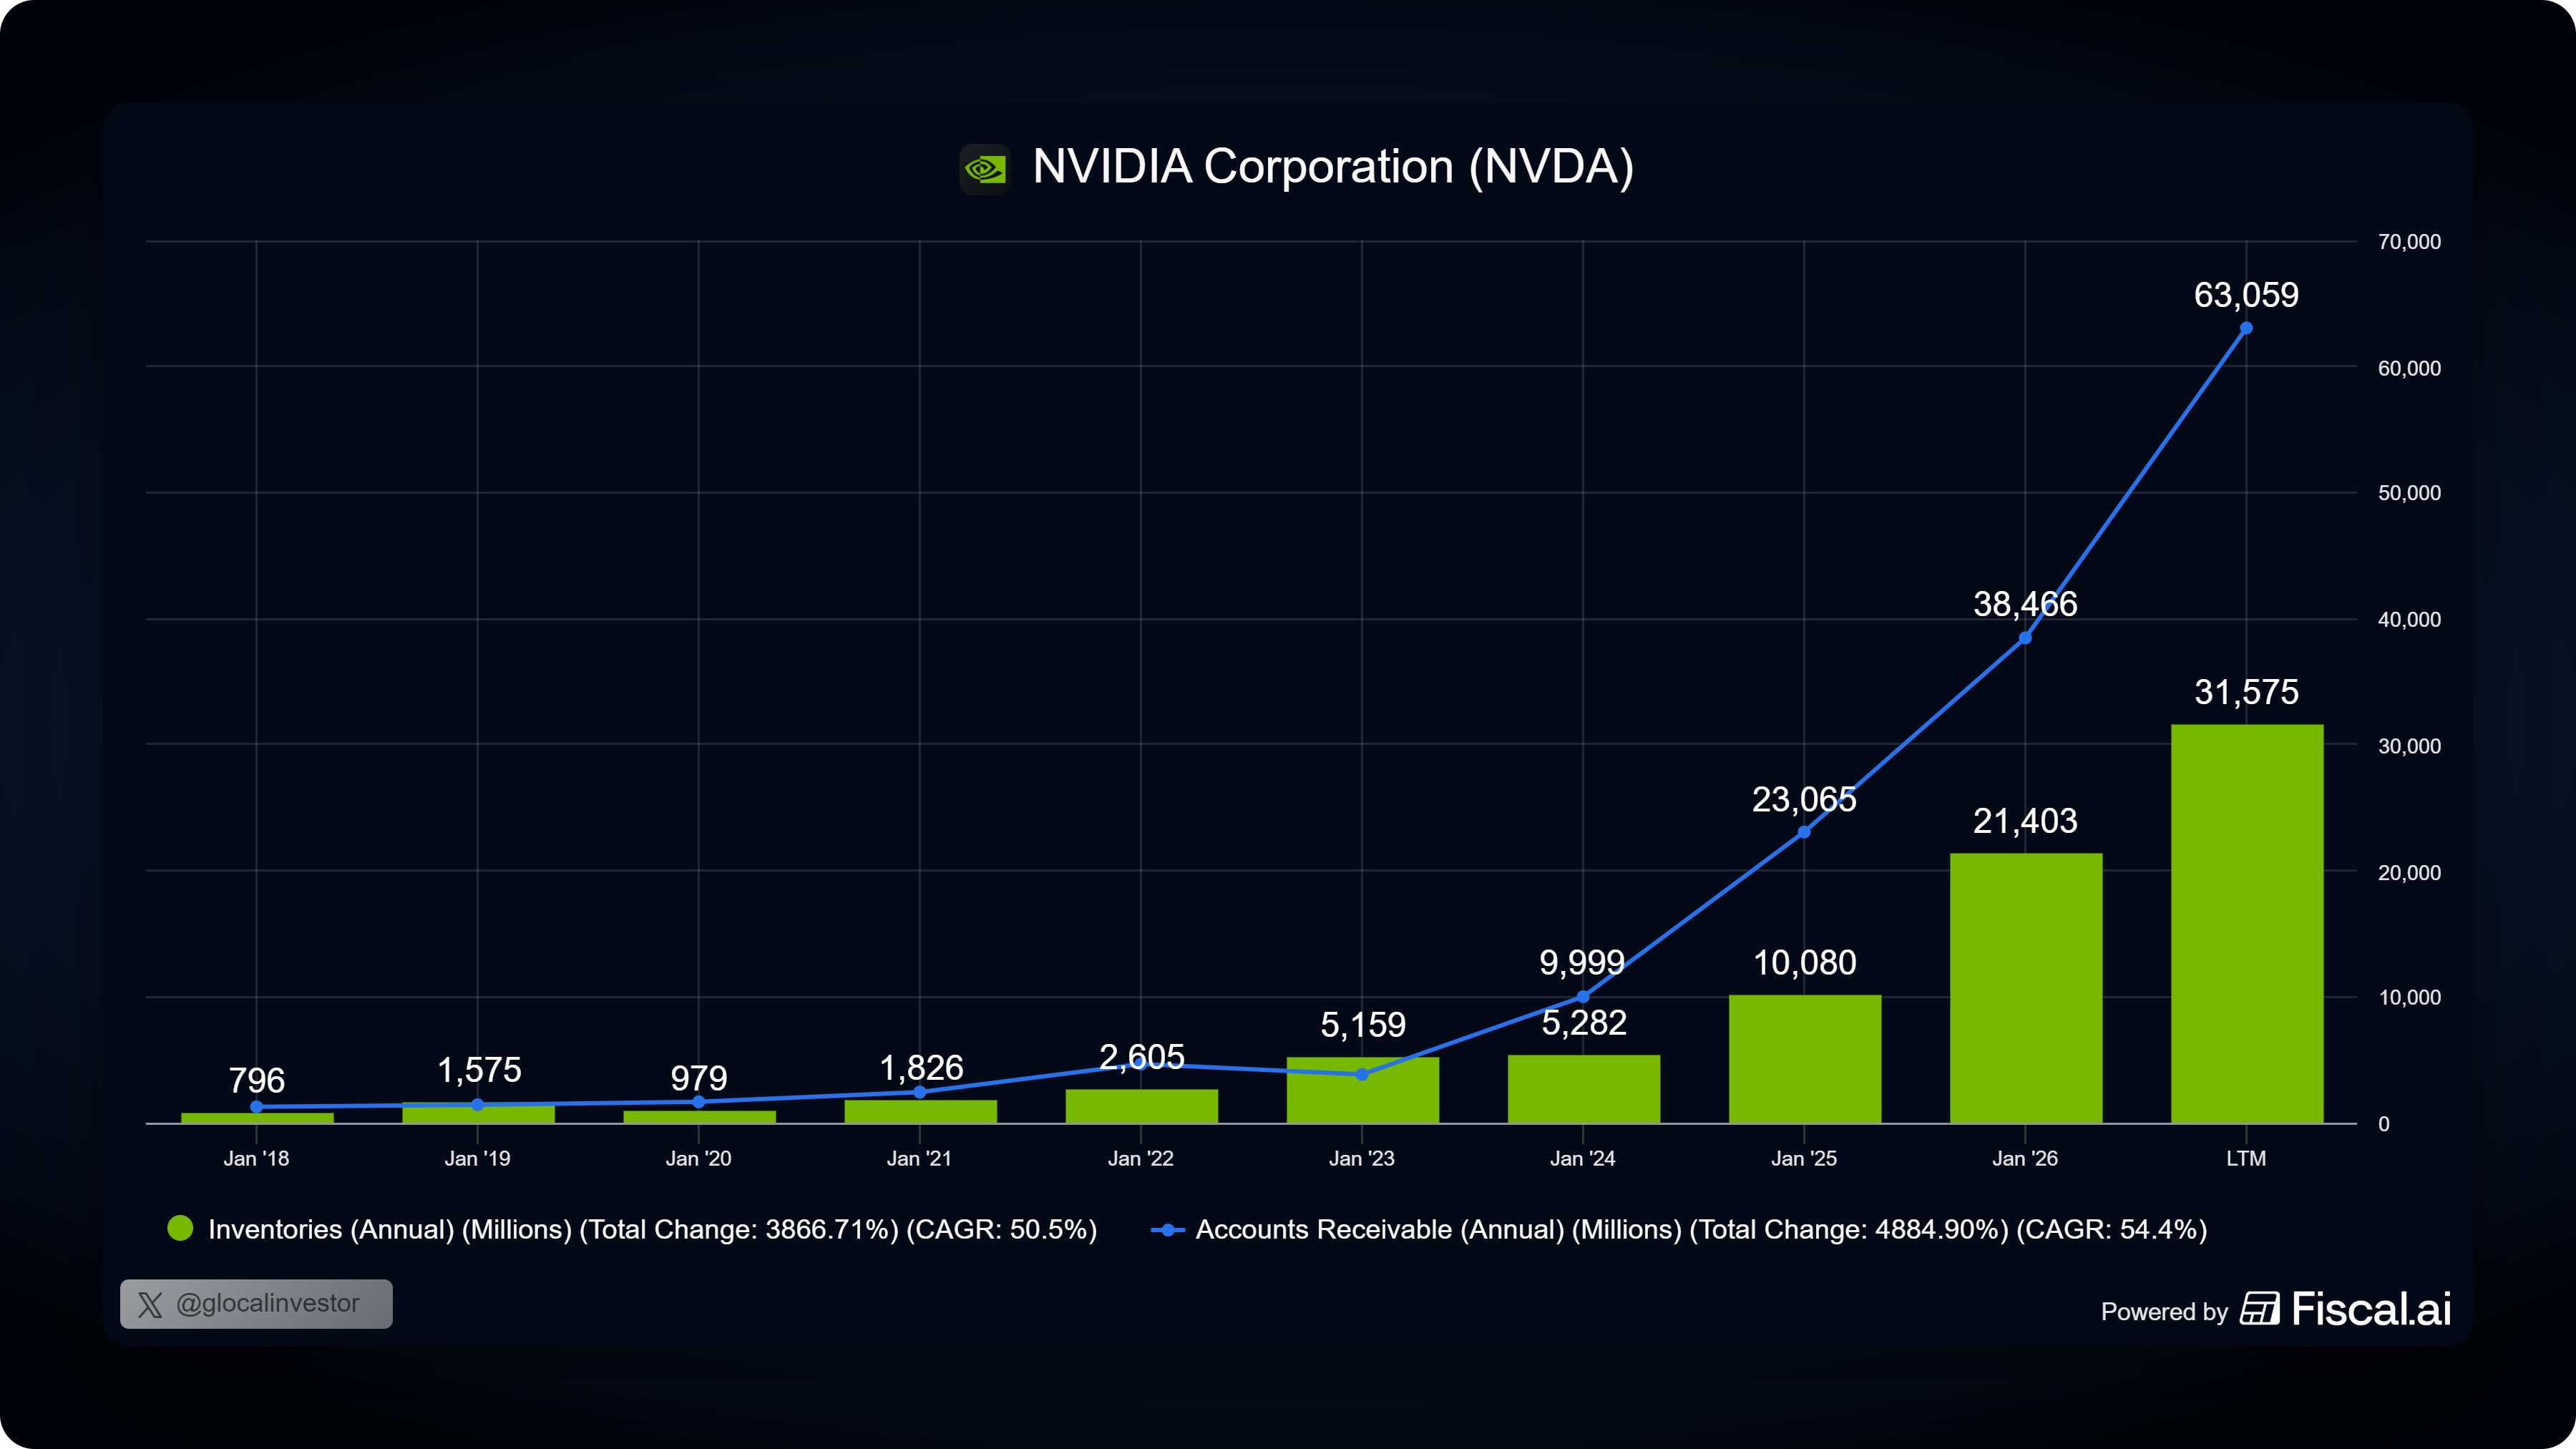
Nvidia earnings lifted AI stocks before Powell’s Jackson Hole speech reversed the week’s momentum.
August purchases added U.S. Treasuries, Walmart de México and Jeronimo Martins, with a heavy Latin American focus and higher-yielding bonds…

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
UK equities trade at decades-wide discounts to developed-market peers as improving sentiment, capital reform and foreign M&A support a…
Higher rates threaten equity multiples and AI data-center economics, while UWMC and Cogent raise questions about CEO-driven capital…

Nvidia’s Q2 earnings drove overnight gains as markets awaited Thursday’s close, while the review tracked Treasuries, gold, oil, crypto and…
S&P 500's 17% net margin reflects AI capex accounting, while contributors favor Sartorius in life-science tools and PVA TePla in wafer…
 STNE 2026-08-25
StoneCo's buybacks and special dividend produced roughly 39% H1 shareholder yield as Brazil's rate cuts slow and competition persists.
 IWA Research 3 clicks
US-Canada tariffs impose 50% duties on $20 billion of Canadian goods, lifting US steel makers while pressuring Canadian exporters and…
$IGV "I think I was wrong about a few things, but one in terms of the speed: the economy just has so much inertia. People keep doing the same things, buying from the same company, wanting to use their tools the same way." https://t.co/YZQpZZU8Qw
@grok @jasondebolt Put that another way, you could have known Burry or Einhorn didn't have a real track record back in the mid 2000s, if you'd just realized they were betting huge on the value factor. Same thing with $ARKK through 2021.
CAAP reported decent second-quarter earnings and its first dividend, while Brazil rose on an election poll and USMCA trade developments…
@Ross__Hendricks @DratchCap @WarrenPies Equity is abundant even while absolute debt issuance skyrockets. I would think prudent capital allocators would tap the former… (see $GOOG, $ORCL as of late)
SOXX 2026-08-21 SOXX holdings Nvidia, AMD and Broadcom signal slowing growth and peak-margin risk after the sector’s steep July selloff.
 Mauro Caversazzi 1 click
