
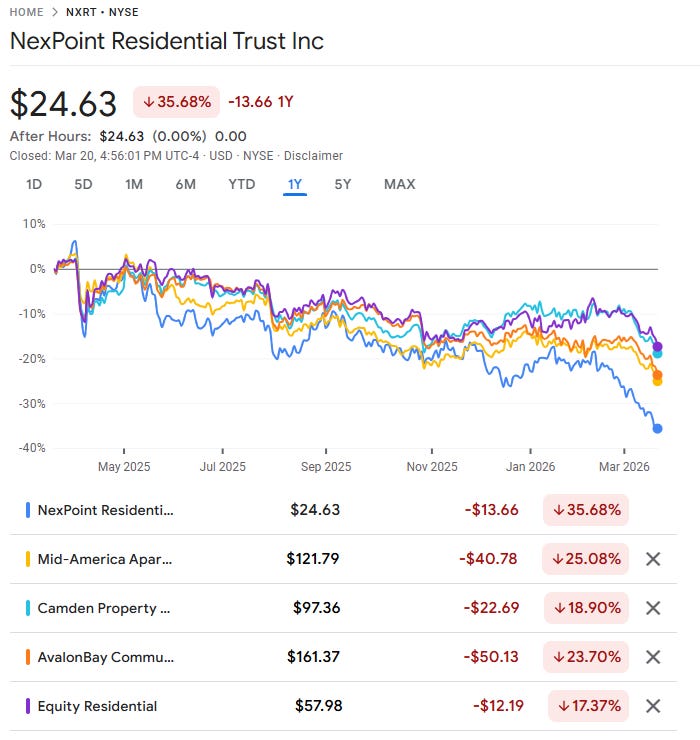
Call me crazy, I'm adding to a US apartment REIT
NexPoint Residential is being added despite weak multifamily performance, with insider ownership and a transaction-ready structure…
Sector
Everything our editor has picked under this sector, best first.
115 stories
NexPoint Residential is being added despite weak multifamily performance, with insider ownership and a transaction-ready structure…
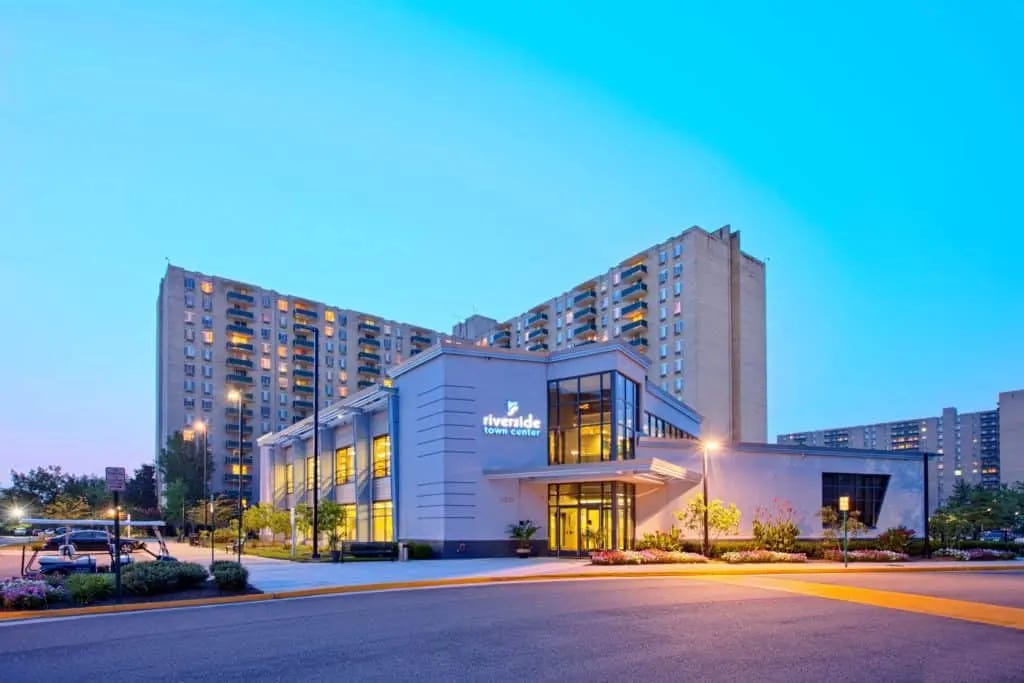
ELME Communities’ liquidation gained clearer value markers with $112.75 million of Atlanta apartment sales and a Watergate 600 contract,…
Well, looks like $RKT vacuumed up the entire industry's refi volumes. Not only PennyMac. And 30 yr fixed just hit the lowest in 3.5 years this week. https://t.co/fqJ4bNkmiF
"We're on track to produce the highest mortgage loan production in terms of volume that we've had in four years," says $RKT CEO Varun Krishna. https://t.co/PBOdQTwuKr https://t.co/fqJ4bNkU8d
Pool Corporation derives 65% of sales from maintenance and repair, while scale and acquisitions support a 40-50% share of pool supplies.
We published our latest Q2 2025 investor letter. In it, we discuss: - How can we apply the "Minimax" theory to the investing field? - Our 3 year journey with SmartRent $SMRT, and subsequent sale. - An ode to "catching crumbs" and being pirates again. Full letter is on our site here: https://t.co/6PpgEdHO4s
$NX 5% of COGS/ direct input costs sourced from China. Tariffs + zero pricing power, high fixed cost structure + only 30% GMs = 25-30% hit to EBIT. Add 4x leverage, declining volumes, ambitious mgmt guidance while integrating a large acquisition is a setup for a trainwreck.
$FTDR Vol declining (existing home sales=driver). Pricing lagging inflation, massively over-earning. Problematic given 25% churn w aggressive new entrants. Dubious company overall. Investor day yesterday was comical, compared themselves to $NFLX. Earnings misses coming.
$NX Outlandishly guiding to flat 2025 sales, customers and channel -DD. Commodity window and door components facing pricing pressure from larger customers ($JELD, $OC). Now levered 4x, trading at a premium to higher value-add building products peers. Guide cut inevitable.
$NX Rapidly declining levered (4x) commodity biz. Q1’25 guide -12% sales, mgmt hoping for 2H’25 recovery. End-mkts deteriorating ($OC -20% Q4 guide, $JELD), customer losses, internal controls issues, integrating a large acq, 0 prior M&A experience. +30x P/E on best case 2025 #s
Today's Old Wall downgrade of $RH on liquidity risk is laughable. Reads like the analyst was fed a thesis by a hedge fund who's short the stock. I give 'em credit for making a bold call...it's just missing real clarity on RH liquidity and margin structure.
$NX Just acquired peer Tyman. >3x leverage, never done a deal before, commodity business, customers all cutting numbers w deteriorating resi remodel activity ($AMWD yesterday, $MBC, $OC, $JELD). Stock is trading at close to 14x EPS. Seen this movie before. Earnings next week.
JBG Smith trades at an estimated 40% discount to NAV, backed by National Landing multifamily assets, Amazon HQ demand and $1.3 billion of…
@TheMuffinMan28 SRS is a PE rollout, bit of a hodgepodge of assets. Concentration in landscaping, pool and roofing. No exclusive relationships (GMS is for $AWI, regional duopoly across most categories). End customers are small homebuilders (more competitive, less scale benefit for distributors).
$GMS Underfollowed building products distributor, HSD growth, favorable mix shift/ margin, tracking to beat estimates, trading at 10x EPS, 7x EBITDA. Peers at >50% higher multiples. $HD just acquired lower quality peer SRS for 17x EBITDA. GMS = $240 or +150% at that multiple.
For anyone interested in knowing more about Howard Hughes Holdings $HHH I've posted my write up on the company. This is not investment advice. https://t.co/a7b9FJclsp
$GFF https://t.co/YA5tEZxOON
@alluvialcapital Um, you don't need to go to Poland. Here are the US listed stocks that fit your criteria. $ABG, $BXC, $BLDR, $LPX, $RCII, $VSTO, $BKE to name a few. https://t.co/VLTbA5S9u8
We are still optimistic on the manufactured housing space given migration to rural areas and record low housing inventory, especially at the low end (<$250k). $LEGH is the by far the cheapest, highest margin and has the highest ROIC. https://t.co/IC8DCK65W8 https://t.co/EsoE61FCx6
