
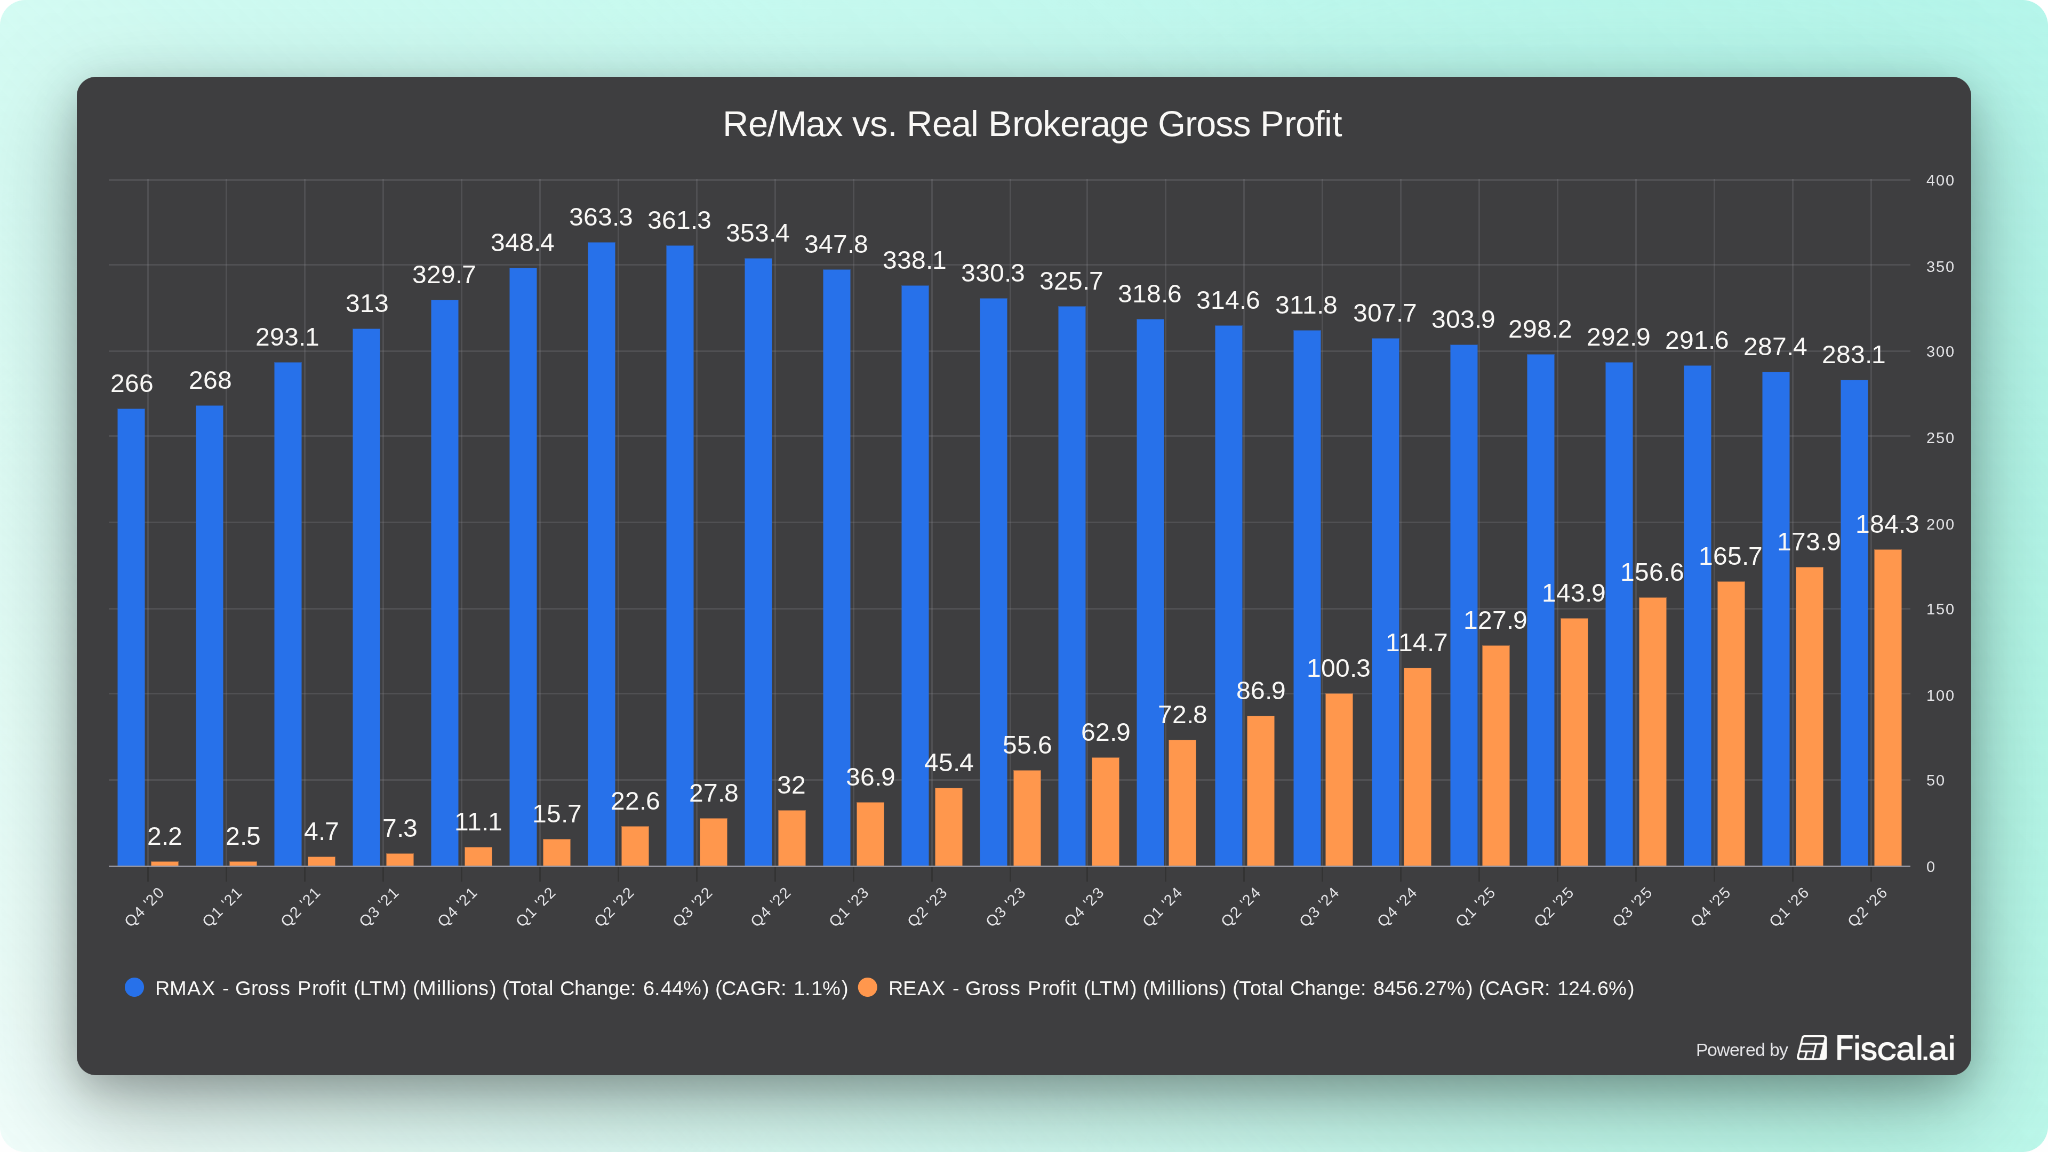
The Real Brokerage: Transformation (Ticker: REAX)
Real Brokerage’s RE/MAX acquisition would triple its agent count, diversify revenue with franchise fees and expand share during a weak U.S.
Sector
Everything our editor has picked under this sector, best first.
115 stories
Real Brokerage’s RE/MAX acquisition would triple its agent count, diversify revenue with franchise fees and expand share during a weak U.S.
Must read imo on $OPEN. Scott raises some great points about the potential if things go right. I have no position rn, and have a more pessimistic view than Scott on the value of Eric Jackson's involvement (my view: he certainly kickstarted but unfortunately showed his true colors stalking a random celebrity for no reason. He is a liability now).
Aveanna benefits as Medicaid shifts ventilator care home, while UK housebuilder scarcity and El Niño create separate long-term tailwinds.
I don't know what people expected for the $RKT print and guide. Always puts and takes, but this was a solid print in this environment. $UWMC just went through the windshield and my guess is that $RKT has some share gains to be had there. Gain on sale in the Pro channel was tight in the quarter so perhaps that reflects some of that.
 OTIS · long
Otis Worldwide's largest global elevator installed base generates 95% recurring revenue, with service margins above 90% supporting a…
Floor & Decor’s same-store sales improved to minus 2%, while $45 million of tariff refunds lifted second-quarter gross profit and operating…

Floor & Decor’s same-store sales improved to minus 2% in 2Q26, while $45 million of tariff refunds lifted profit and funded pricing,…
Builders FirstSource reported Q2 2026 sales down 9% to $3.9 billion as weak housing demand and aggressive competitor pricing cut EBITDA…
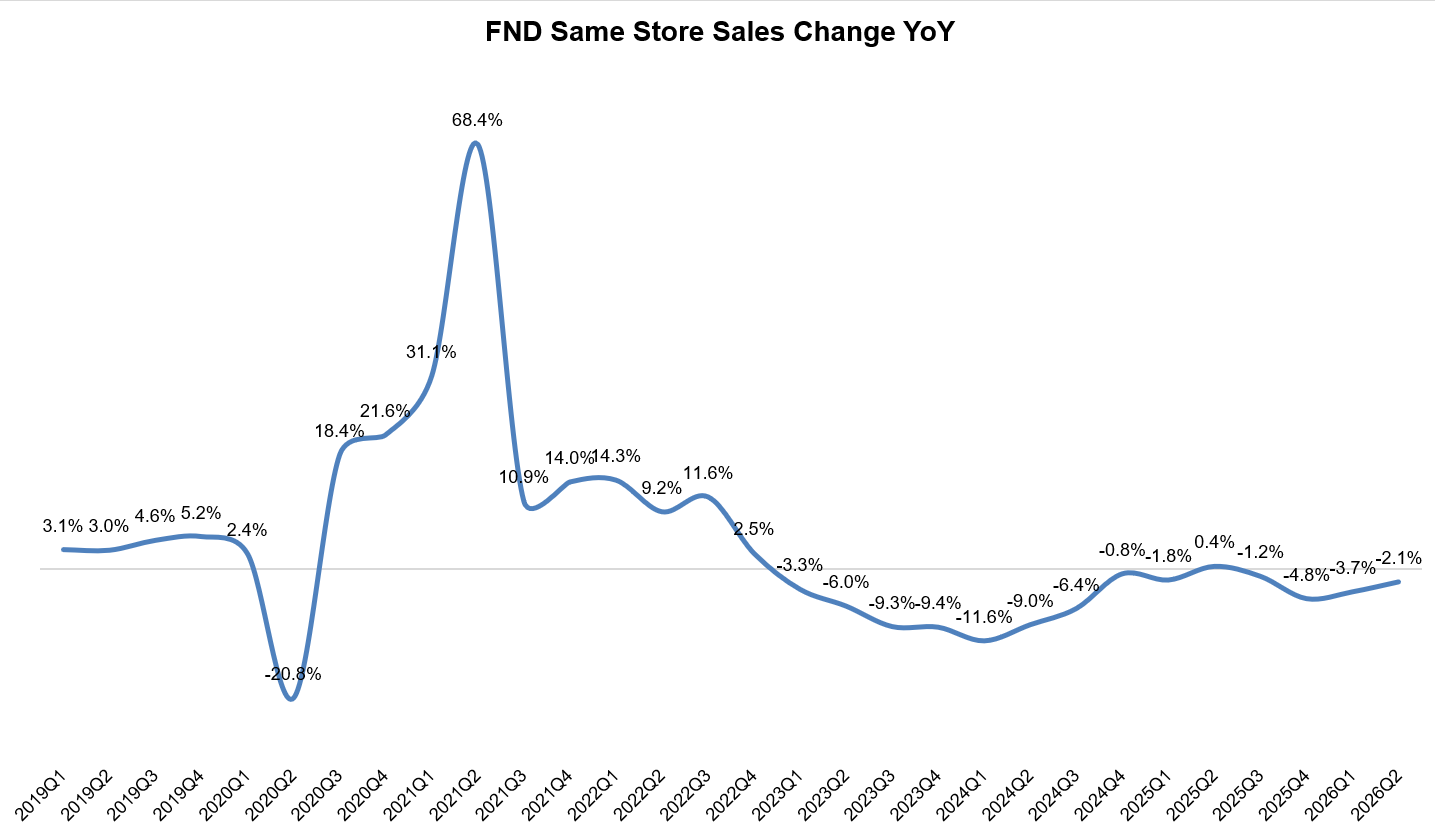
Floor & Decor held 2026 guidance after a 2Q beat, with comps improving through June; tariff refunds lifted margins and may fund pricing…
 ZG · long
Zillow is pitched as a long with a $72 target, implying 58% upside from trough earnings and a trough valuation multiple.
 QXO · long
QXO, led by Brad Jacobs, is consolidating North America’s fragmented building-products distribution industry after rapidly building scale…
Thanks again to @realsteveeisman for having me on his podcast again. It's always fun chopping it up with Steve. We talked about a lot of things: the ever shifting dynamics of the residential real estate market ($Z/$ZG, $COMP $RKT, $CSGP etc.), structural problems in for-profit education (it's not just AI), and why I'm short $GOOG among other things. You can listen to the episode here! https://t.co/PdhE7ro93h
Alpha where you least expect it... Over the past 3-months the FURNITURE space has delivered monster upside relative to the indices. Many of these legacy companies have pristine balance sheets, generate cash, and continue to modestly grow their order books despite the ongoing weakness in housing. These stocks in some cases were trading at close to zero EV ($BSET, $ETD) when including their real estate holdings. They remain cheap and have tons of earnings leverage to a housing upturn. 3-month returns: $BSET 47.7% $BOBS 30.8% $HOFT 17.5% $WSM 17.2% $LZB 14.7% $HVT 13.3% $SPX 6.4%
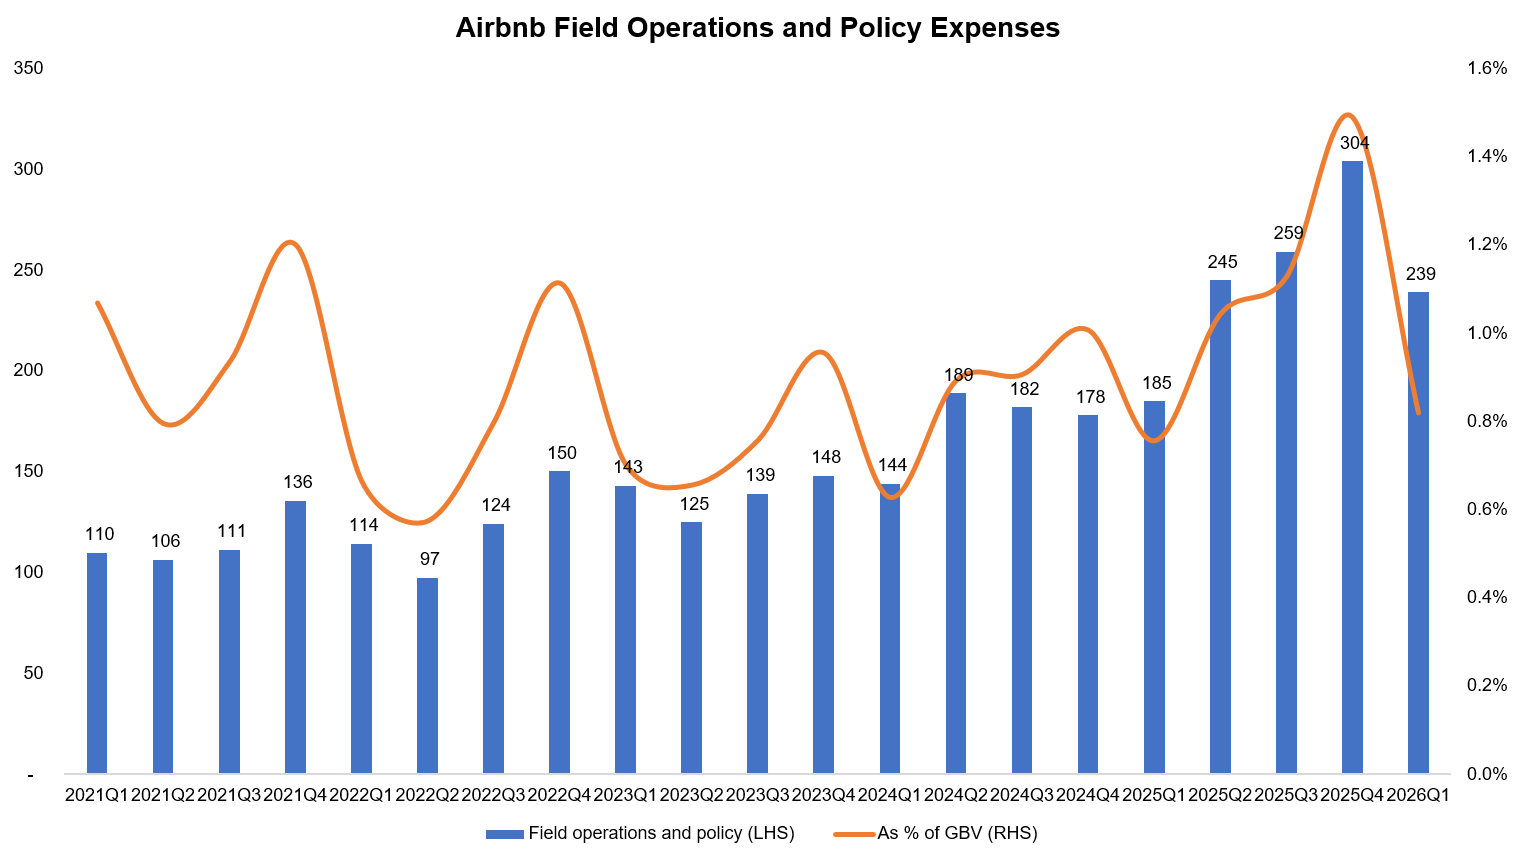
Airbnb spent 1.1% of 2025 GBV on field operations and policy as regulatory costs persisted; New York’s short-term-rental crackdown cut…
Sector action is bizarre today --- travel/discretionary (ex amazon (who posted very lousy prime sales) are surging), housing and adjacent like furniture ($w $wsm), biotech adjacent bid ($rgen, $medp) and waste stocks ($wcn). You want to derrick micron, I get it. And I get gas prices lower, market expects to fade out rate cuts that were priced moving forward as Warsh moves to trim mean/new data versus actually being hawkish, and some impact on a name like $hd off the housing bill. But all of these things are at the margin and known leading up to today --- so why target, kbh (on relatively inline to disappointing numbers yesterday) Expedia today versus yesterday? Market moves in very funny ways recently
$FGMC $3.5B mkt cap tiny home builder. $1M sales. -1,000% GMs. Incinerating cash. 83% SPAC redemption, only $14M in cash. Auditor: "substantial going concern doubts.” Modular homes industry littered with recent bankruptcies. Dubious leadership backgrounds.
$QXO gang anyone have a current cap table, wanted to run some numbers but its hard to keep up with all the issuance/debt offerings.... Pro forma suggests there is around 1.1B shares outstanding? (will that include all the financing to get Topbuild closed (I believe so)? + around $8B in net debt (pro forma) So at $14 a share - that would be roughly $23B EV value? Anyone confirm this or tell me which pieces are wrong (for Kodiak, beacon and Topbuild) Roughly $2B EBITDA off their press release (probably up for debate, rates/economy, then need to look how much synergies might be backed into that) So 4x leveraged (means likely more shares need to get issued to de-risk especially with interest rate risks and transmission to demand) so 11.5x with mote dilution (likely).....getting close but not there yet - still think you need to wait for 10x or < Last and most important question does the math around Beacon change - 15x is meaty for a distributor multiple so unlikely they walk. But with the 45/55 split (is there floor conditions or will TopBuild eat that difference if/when they vote later this month (if not anyone know what the break fee is). Thanks in advance
#Quad4 looming in June. To be clear, Quad4 is horrible for retail stocks — with the only exception being housing-linked retail like $RH $FND $HD etc…
MasterBrand's all-stock merger with American Woodmark creates the largest cabinet maker, trading at 7.7 times trough EBITDA including…
You wouldn't know it based on the way investors on this platform talk about homebuilders and the housing market in general but Berkshire Hathaway's deal for $TMHC is the THIRD announced takeout of a publicly traded homebuilder this year. Sentiment in the space has rarely been worse than it is now, but some longer term thinkers see the opportunity... $XHB $ITB $TPH $UHG
Atlas Engineered Products reported Q1 revenue down 15.5%, gross margin at 3%, and a $1.73 million loss while drawing $2 million on its…

Installed Building Products and Mettler-Toledo, down 38% and 32%, test whether lower valuations reflect deteriorating moats or cyclical…
The SF housing market is on fire. Should bode very well for $FPH's Candlestick project, including finding financing partners. https://t.co/vFjXoS2coK

Floor & Decor cut 2026 guidance after 1Q same-store sales fell 3.7%, while shrinking new-store formats, cutting comparable-store SG&A and…
