
Meritage Homes: Cheaper On Book Than Any Year-End In A Decade
 Tim Travis 5 clicks
Sector
Everything our editor has picked under this sector, best first.
115 stories
Tim Travis 5 clicksHow’s that $OPEN working out? https://t.co/5eKiKeh6lz
Keith Rabois belongs in jail. $OPEN https://t.co/NO4rrL3URv
@rabois @MarkNeuman18 @HHGF99 $OPEN
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
Bad home in a troubled neighborhood? $DFH @BearCaveEmail https://t.co/ia5jNdAZ79 https://t.co/3vE2Slewdx
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
CEO and chairman of $DFH has a significant commitments in related party land banking asset manager, and from which he has already received over $10m in distributions? 🆒🆒🆒 More like a Dreamfinder's job amirite? https://t.co/VxLk8cFt5D
Lennar cut build times to 116 days and adopted an asset-light land model, while gross margin fell to 15.8% from 27.5% as land costs rose.
Lennar grew from a Miami builder into one of America’s two largest homebuilders, controlling land largely through options and land banks…
Lennar’s second audio program examines the homebuilder’s business for professional investors and housing analysts.
Monster run past few days in retail -- $SHOP, $URBN, $EBAY, $ETSY $SHAK etc. especially considering where oil and diesel have traded and the results from $DPZ today..... seems selective still many laggards in each of those verticals - someone making a rates/inflation play or pure rotation slop as they sell chips? Weird(er) is the strength in rate sensitive plays like $w and even $trex relative t the rest of housing like $QXO, $BLDR, $low Opportunities in-between sectors to make our own call based on where you view the data
I'm not publicly telling people that $FNMA and $FMCC are safe investments and then telling them I sold after the fact. I'm not charging people for ideas like the above. Any prospective client can request my audited performance and it'll be provided with the interaction memorialized for request and review by auditors.
@MMTLP4ME88 @ericjackson @rabois @mikealfred @APompliano @philrosenn @dayetweets @nejatian Am still short as $OPEN is valued at over 2x book.
A Credit-Score Shift at Fannie and Freddie Is Shaking Up the Mortgage Market $FICO https://t.co/lqXRQVDFAT
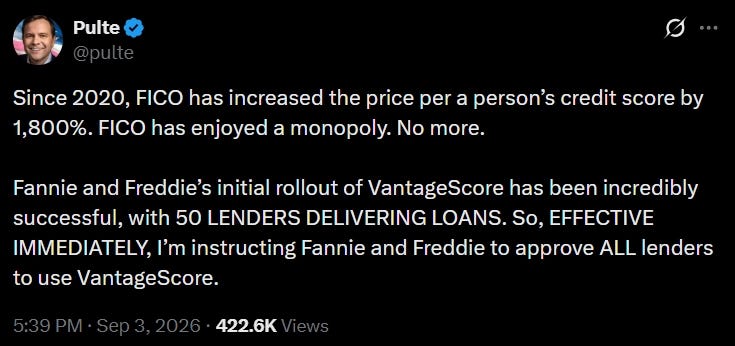
FICO’s mortgage credit-score monopoly sits at the center of a GSE-dominated U.S.
$OPBK: Korean American depositor focus across Southern CA, TX, NV, WA. LTM Owner's Earnings=27.32m 7.8x multiple. 3.7% dividend. At book. 12 full service branches and 1 loan production office (LPO). SBA preferred lender status allows them to unload 75% of loans at a premium. Focused on real estate and housing. 1h 2026 closed 5 LPOS due to "limited market demand" was outside core geography. NPLS +22.7% from YE 2025 to Q2 2026. Cost of deposits end of Q2 2.93%, more than 50% are CDs which is bad as they are not sticky and rate sensitive.
$OC: Trading at an $11B market cap and 5x EBITDA, Owens Corning (NYSE: OC) presents a compelling asymmetric investment thesis as a forecasted >90% probability 2026/2027 "Super El Niño" prepares to drive massive, non-discretionary, insurance-funded roofing repair demand across the Southeast United States. Historical parallels from the 2015–2016 and 2023–2024 El Niño cycles demonstrate clear operating leverage, where severe storm activity doubled roofing EBIT and generated 2x to 3x stock returns within 12 to 24 months. Modeling a 35% (base) to ~50% (bull) EBITDA expansion at a standard 9x EV/EBITDA multiple points to a 2x base-case to nearly 3x bull-case upside over the next 12 months, supported by a ~2.5% dividend yield and tactical plant expansions in Ohio and Alabama. Primary risks include asphalt input price spikes linked to high crude oil prices and ongoing integration or tariff friction from the $3.9B Masonite acquisition. However, the thesis features a deep margin of safety anchored by a elevated trough EBITDA margin floor of 24–34% (up from 13–16% in past cycles), cost-saving vertical integration via in-house asphalt oxidation, and strict insurance policy timelines that compel homeowners to replace damaged roofs regardless of broader macroeconomic weakness.
UPDATE: Berkshire Hathaway appears to have paused $LEN buying. It’s the first two-trading-day gap in its disclosed buying since it began building its stake on Sept. 17. https://t.co/bDtucKUWSA
Lowe’s trades at 15x earnings after a 23% decline, with weak housing and high rates pressuring growth while inventory discipline supports…
 Seeking Profits
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Based on Hunterbrook Media's reporting, at the time of publication Hunterbrook Capital is short $MRP, short $LEN, and long a basket of comparable securities. Positions may change at any time. This article is not investment advice or any recommendation. See full disclosures below.
Millrose management told Goldman Sachs its Lennar home purchases were a rent-to-own pilot, with a renter often lined up before $MRP buys. We found approximately 95% of more than 1,000 home addresses bought from $LEN were actually listed for rent to the public. https://t.co/szKAaqaBoN
 SITE · long
SiteOne Landscape Supply, a 673-branch distributor, reaches roughly half of U.S.
