

Lee Roach on X
From $23 bucks per share to $2.61 and collapsing after market from crap earnings. When does $GEOS become a buy?
Sector
Everything our editor has picked under this sector, best first.
From $23 bucks per share to $2.61 and collapsing after market from crap earnings. When does $GEOS become a buy?

@kiwicarrotcake double winner. $FLR made a great return on its cash investment, and will win business from $SMR and other SMRs.

Rick Rule argues copper needs $250 billion of capital and says 30-year uranium contracts are reshaping mine financing.
India’s 236 GWh battery target boosts local electrolyte-salt makers, while Mirion’s radiation monitors and Overwatch’s passive drone…
Chord Energy trades at 3x mid-cycle EV/EBITDA with a 15% free-cash-flow yield at $75 WTI, while repurchasing shares and expanding its…
 Ron Ferrie 4 clicks
 ODC · long
Oil-Dri Corporation of America produces cat litter and operates agriculture, recreation and renewable diesel businesses.

Situational Awareness 2.0 is coming. I think Leopold's early ideas were directionally right from $SNDK to $BE. Even his recent ones like Taiyo Yuden, I do see MLCCs becoming a bottleneck in 2027. Unfortunately, due to excessive leverage and crowded longs... Positioning left him vulnerable to liquidation before he got to see longer horizon ideas play out. I think it's fun to see fund managers actually have unique ideas in similar sectors. So hope he can make a comeback. I learned a lot of lessons myself to in terms of being more narrow with long selections, so very excited for 2027.
 BH · short
Biglari Holdings short thesis targets a conglomerate spanning restaurants, oil and gas, insurance and media.
APA’s Q3 free cash flow more than doubled to $699 million, funding $537 million of shareholder returns and debt reduction as it pursues a…
 IWA Research
Considering selling very long-dated ATM/OTM calls in the refiners. $VLO $MPC The worm has turned. May bounce again but I think it highly likely the next 2-3 years will not be as lucrative for the sector as the past year.
Monte Investments rotated Nvidia into Alphabet before earnings and reviews Knife River’s margin squeeze, AMD’s World Labs acquisition, and…
Just now reading the $NXT call from yesterday's analyst day. Management was bullish AF. Might add to my long. "We talked about doing $3.7 billion this fiscal year and $5.2 billion in fiscal 2030... We've raised guidance I covered at our last earnings call, we expect to deliver $4.3 billion this year. And now we're taking up our fiscal 2030 guidance to over $7.5 billion."
Perma-Fix's Q3 gross margin fell to 3.1% from 14.6% as Hanford delays and fixed costs drove cash burn and potential dilution.
 Number Cruncher

About five years from the bubble burst and $XLE still outperforming $XLK
@sidecarcap Both $ECRO and $RNGE using coal as a launching pad to do something bigger. $500m of NOLs and data center potential, respectively

Chevron nears $5 bn deal for Blackstone-backed oil producer in US Gulf $CVX
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.

@CihunSol Quite a few. The insiders of Pampa Energia $PAM have been consistently buying. So have the insiders of Liberty Latin America $LILA, especially their preferred shares. Oddly enough so has a cluster of insiders from GameStop $GME Too many to list.
 DVFI · long
Diversified Gas & Oil’s $500 million 9.75% senior secured notes due 2029 are rated a buy.

Here's my November 8 update on $NTWO (you can read most of it for free):
Peabody Energy trades at 2.7 to 2.9 times consensus EBITDA after Centurion delays cut Q4 guidance, with $434 million cash, $297 million…
 Bang For The Buck 5 clicks
OMSE trades just above net cash despite growth, earnings and no debt, with Aramco concentration, reporting controls and liquidity the chief…
 Daryl Davis
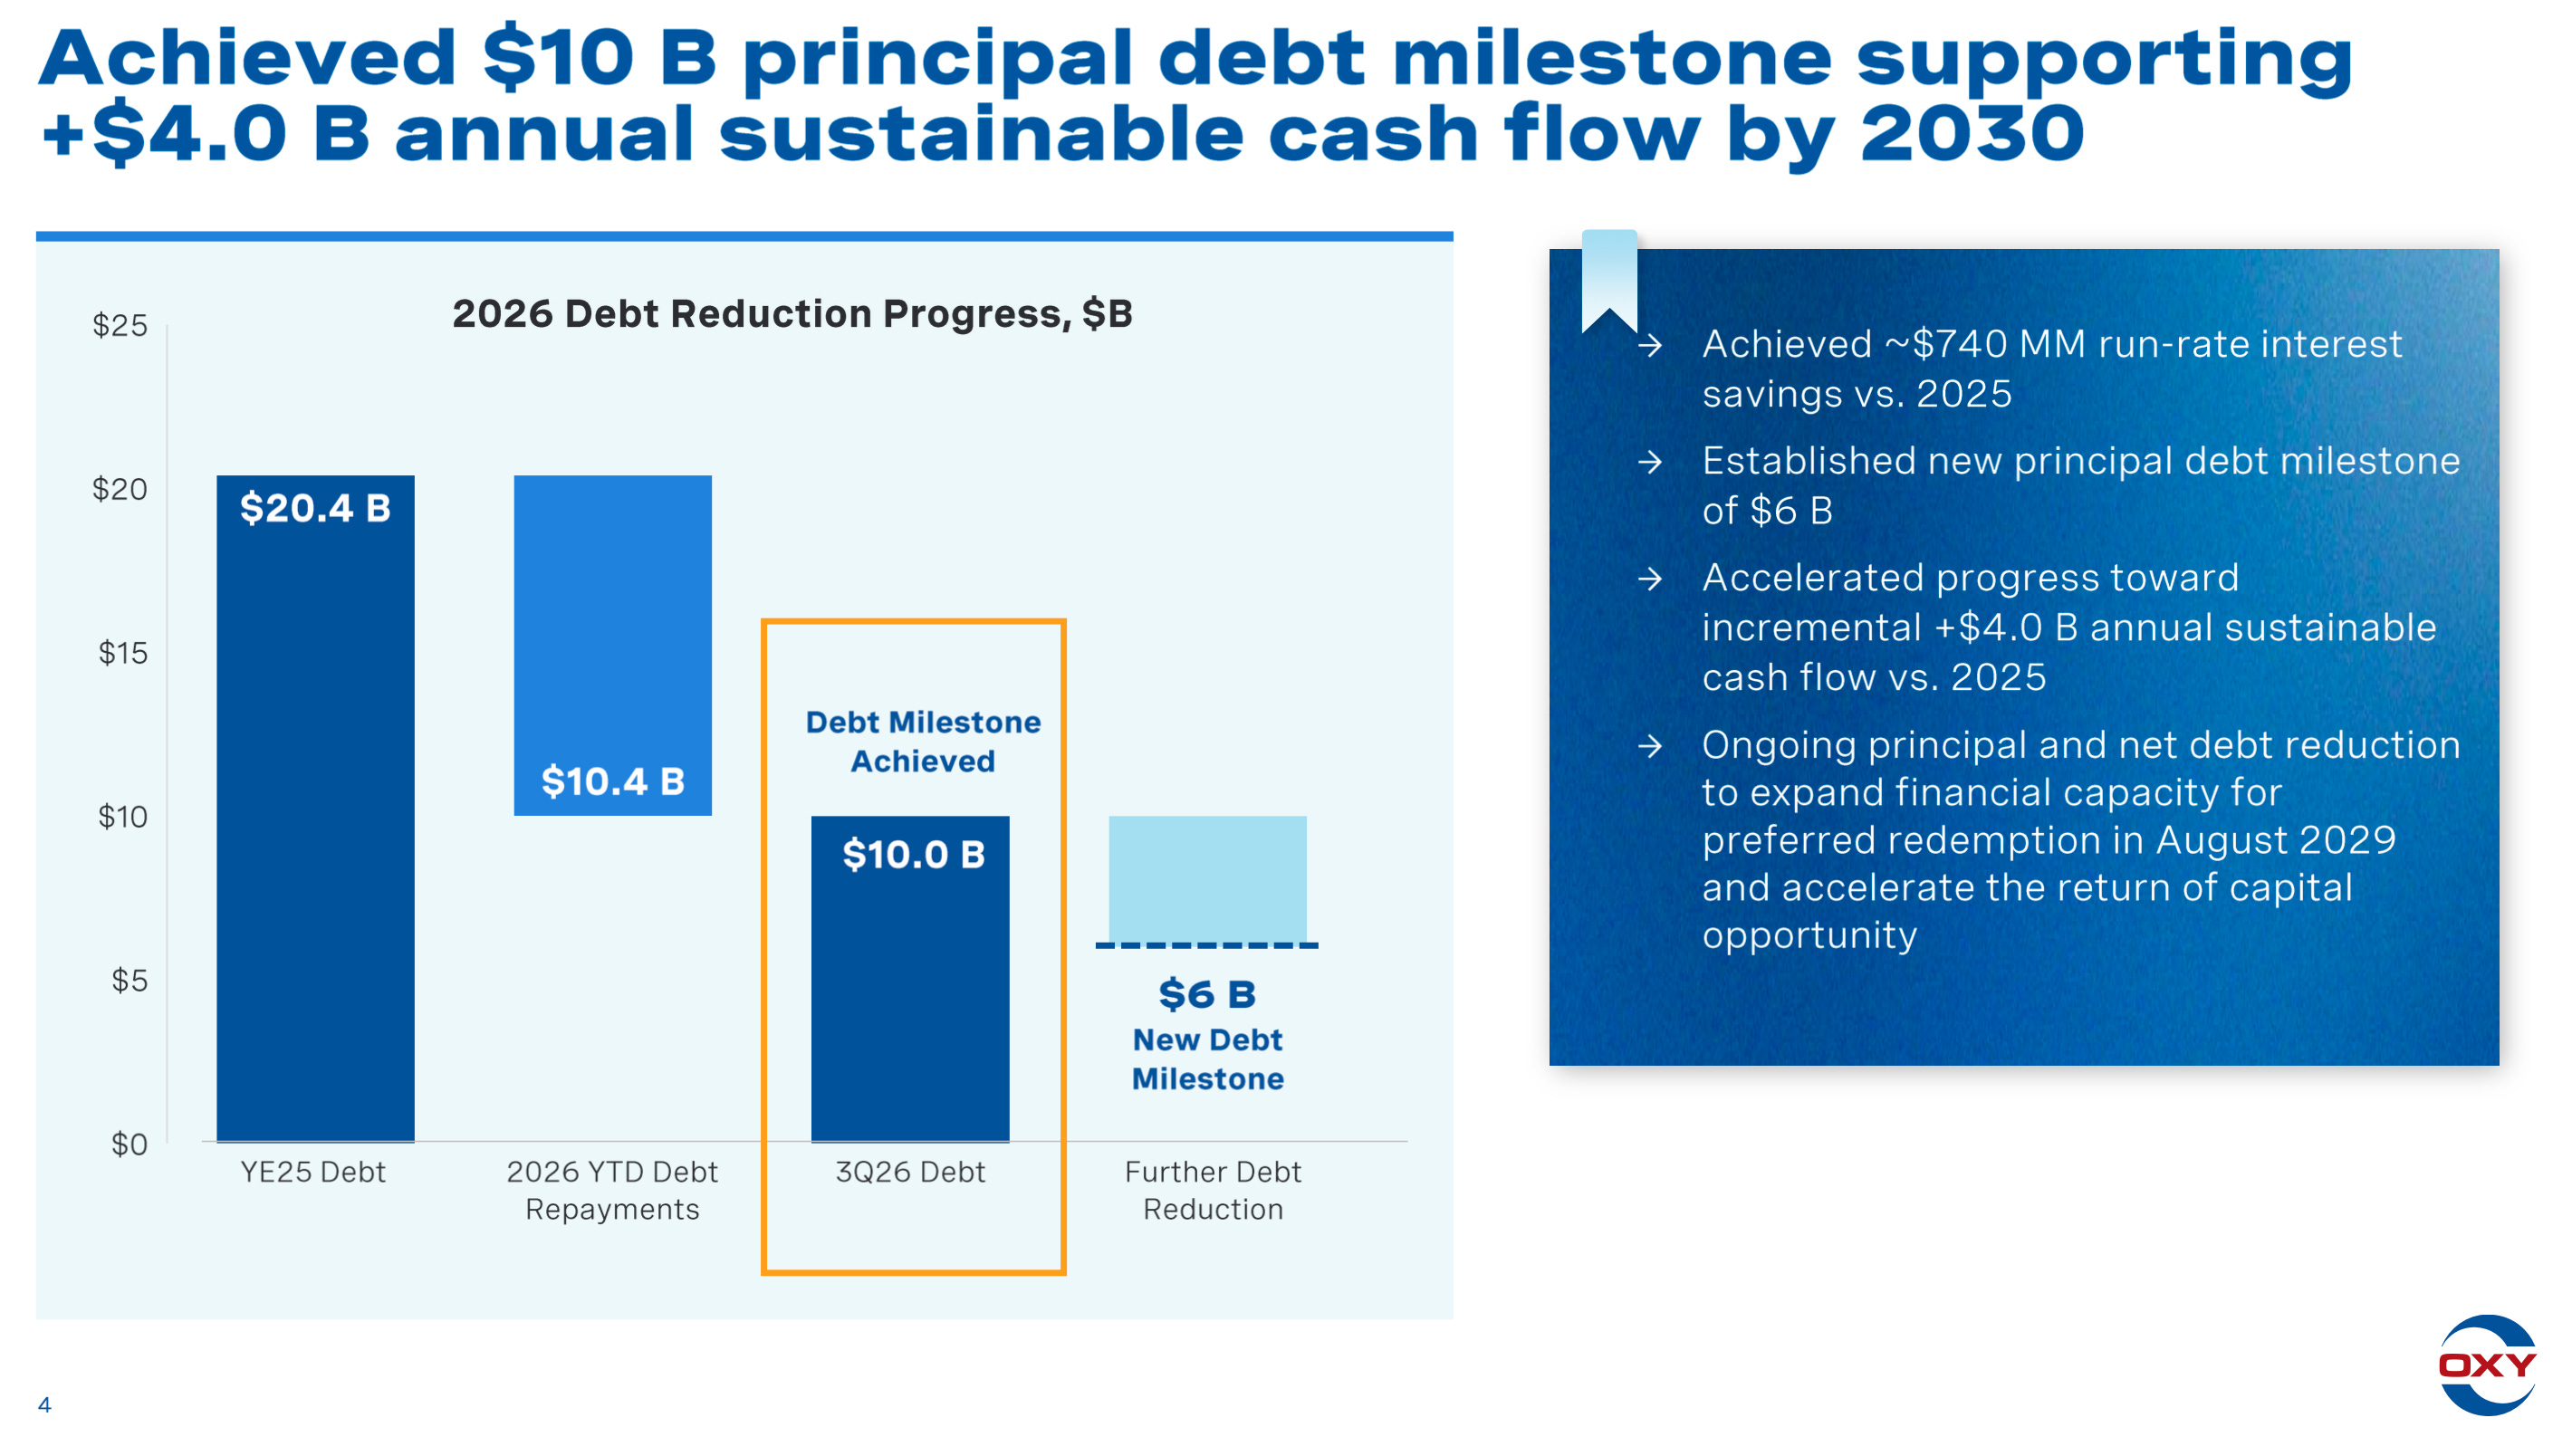
Occidental Petroleum reached its $10 billion debt target early and targets $6.4 billion to $6.5 billion of 2027 free cash flow at $65 WTI,…
When companies report in trillions, its time to revalue that currency. 🇨🇴 $EC
Kimbell Royalty Partners targets an 11% normalized yield through third-party drilling royalties, with distributions sensitive to oil and…
 Atlas Diary 4 clicks
Petrobras posted record 3Q26 production and earnings, but higher investment needs are shrinking dividends as a possible Lula IV government…
 Bernard Zambonin 9 clicks
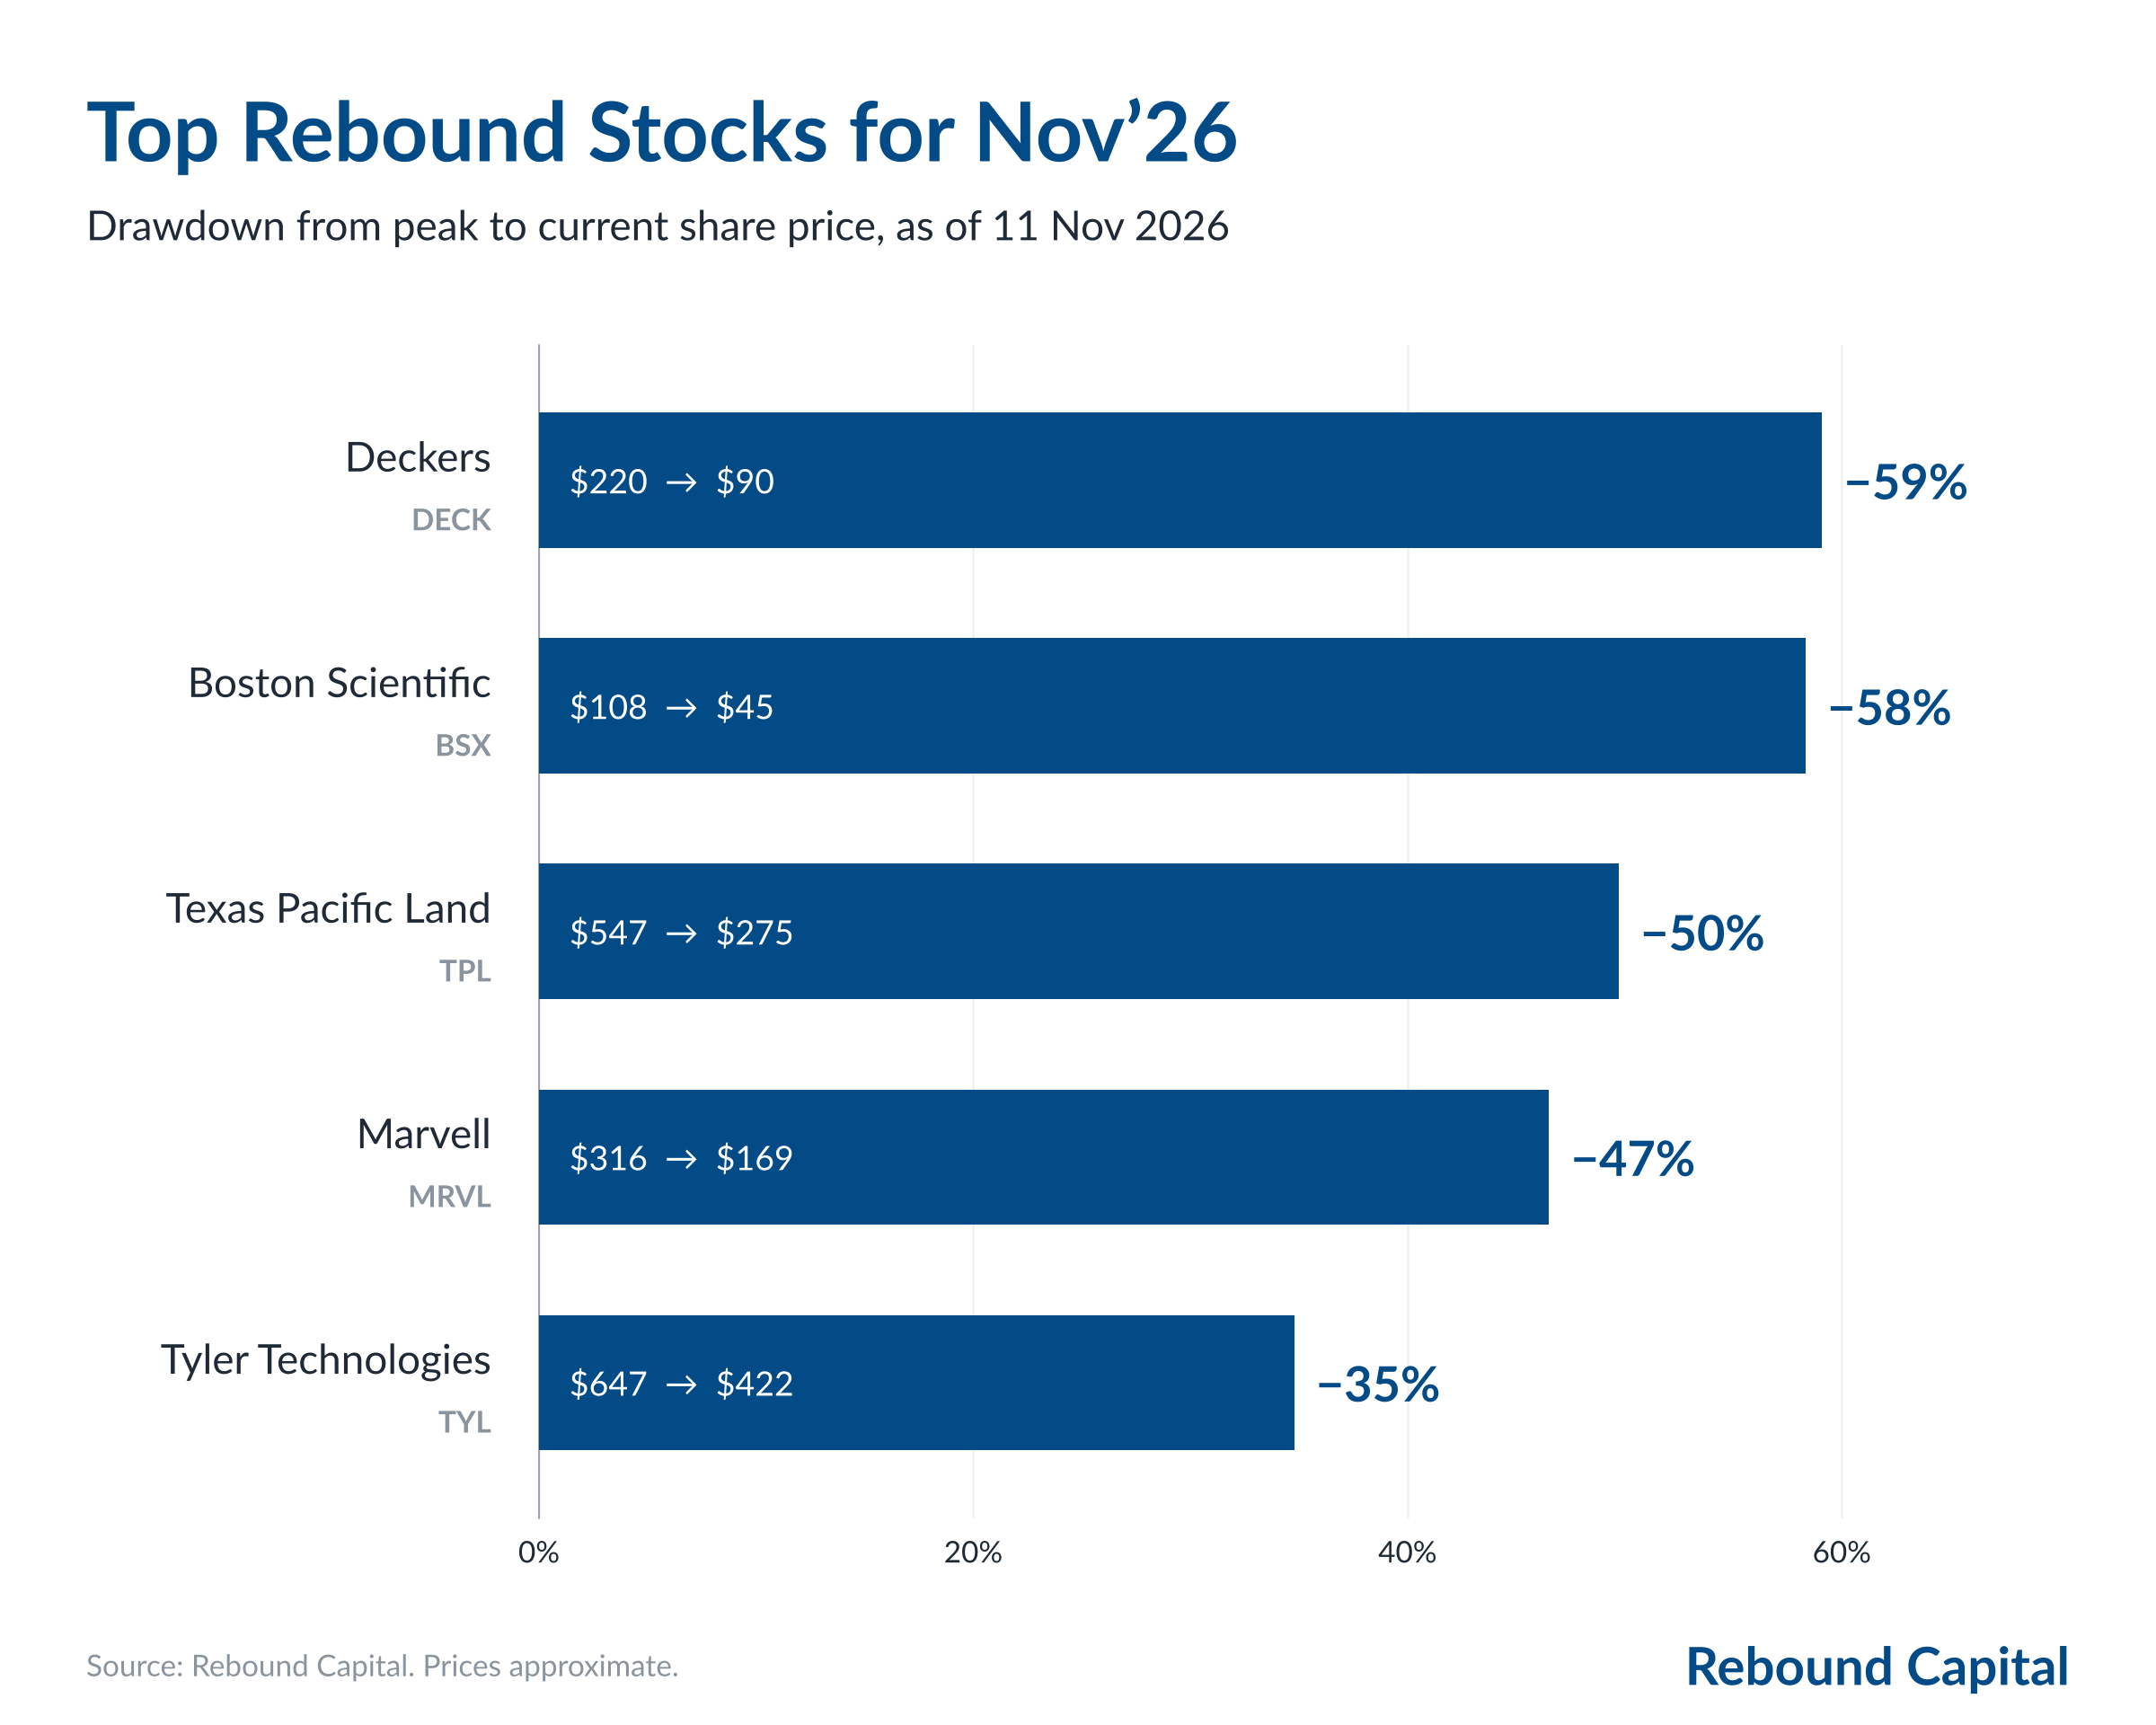
Texas Pacific Land's 50% selloff reflects faded data-center expectations, while its Permian royalty business generated $498 million of 2025…
Par Pacific's Q3 revenue rose 52% to $3.05 billion, while refining margins, integrated logistics and $226 million net cash support earnings…
 Blake Winiecki

$SHLS & $ARRY Merger / Short Report Review
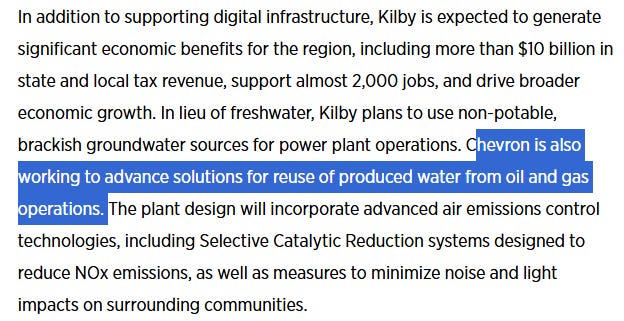
WaterBridge grew Q3 revenue 16.9% year over year as Speedway Phase I lifted produced-water volumes, while pursuing large-scale data center…
Fervo Energy raised $2 billion in its May IPO, then fell nearly 70% below issue price after a Morpheus short report, despite targeting 1 GW…
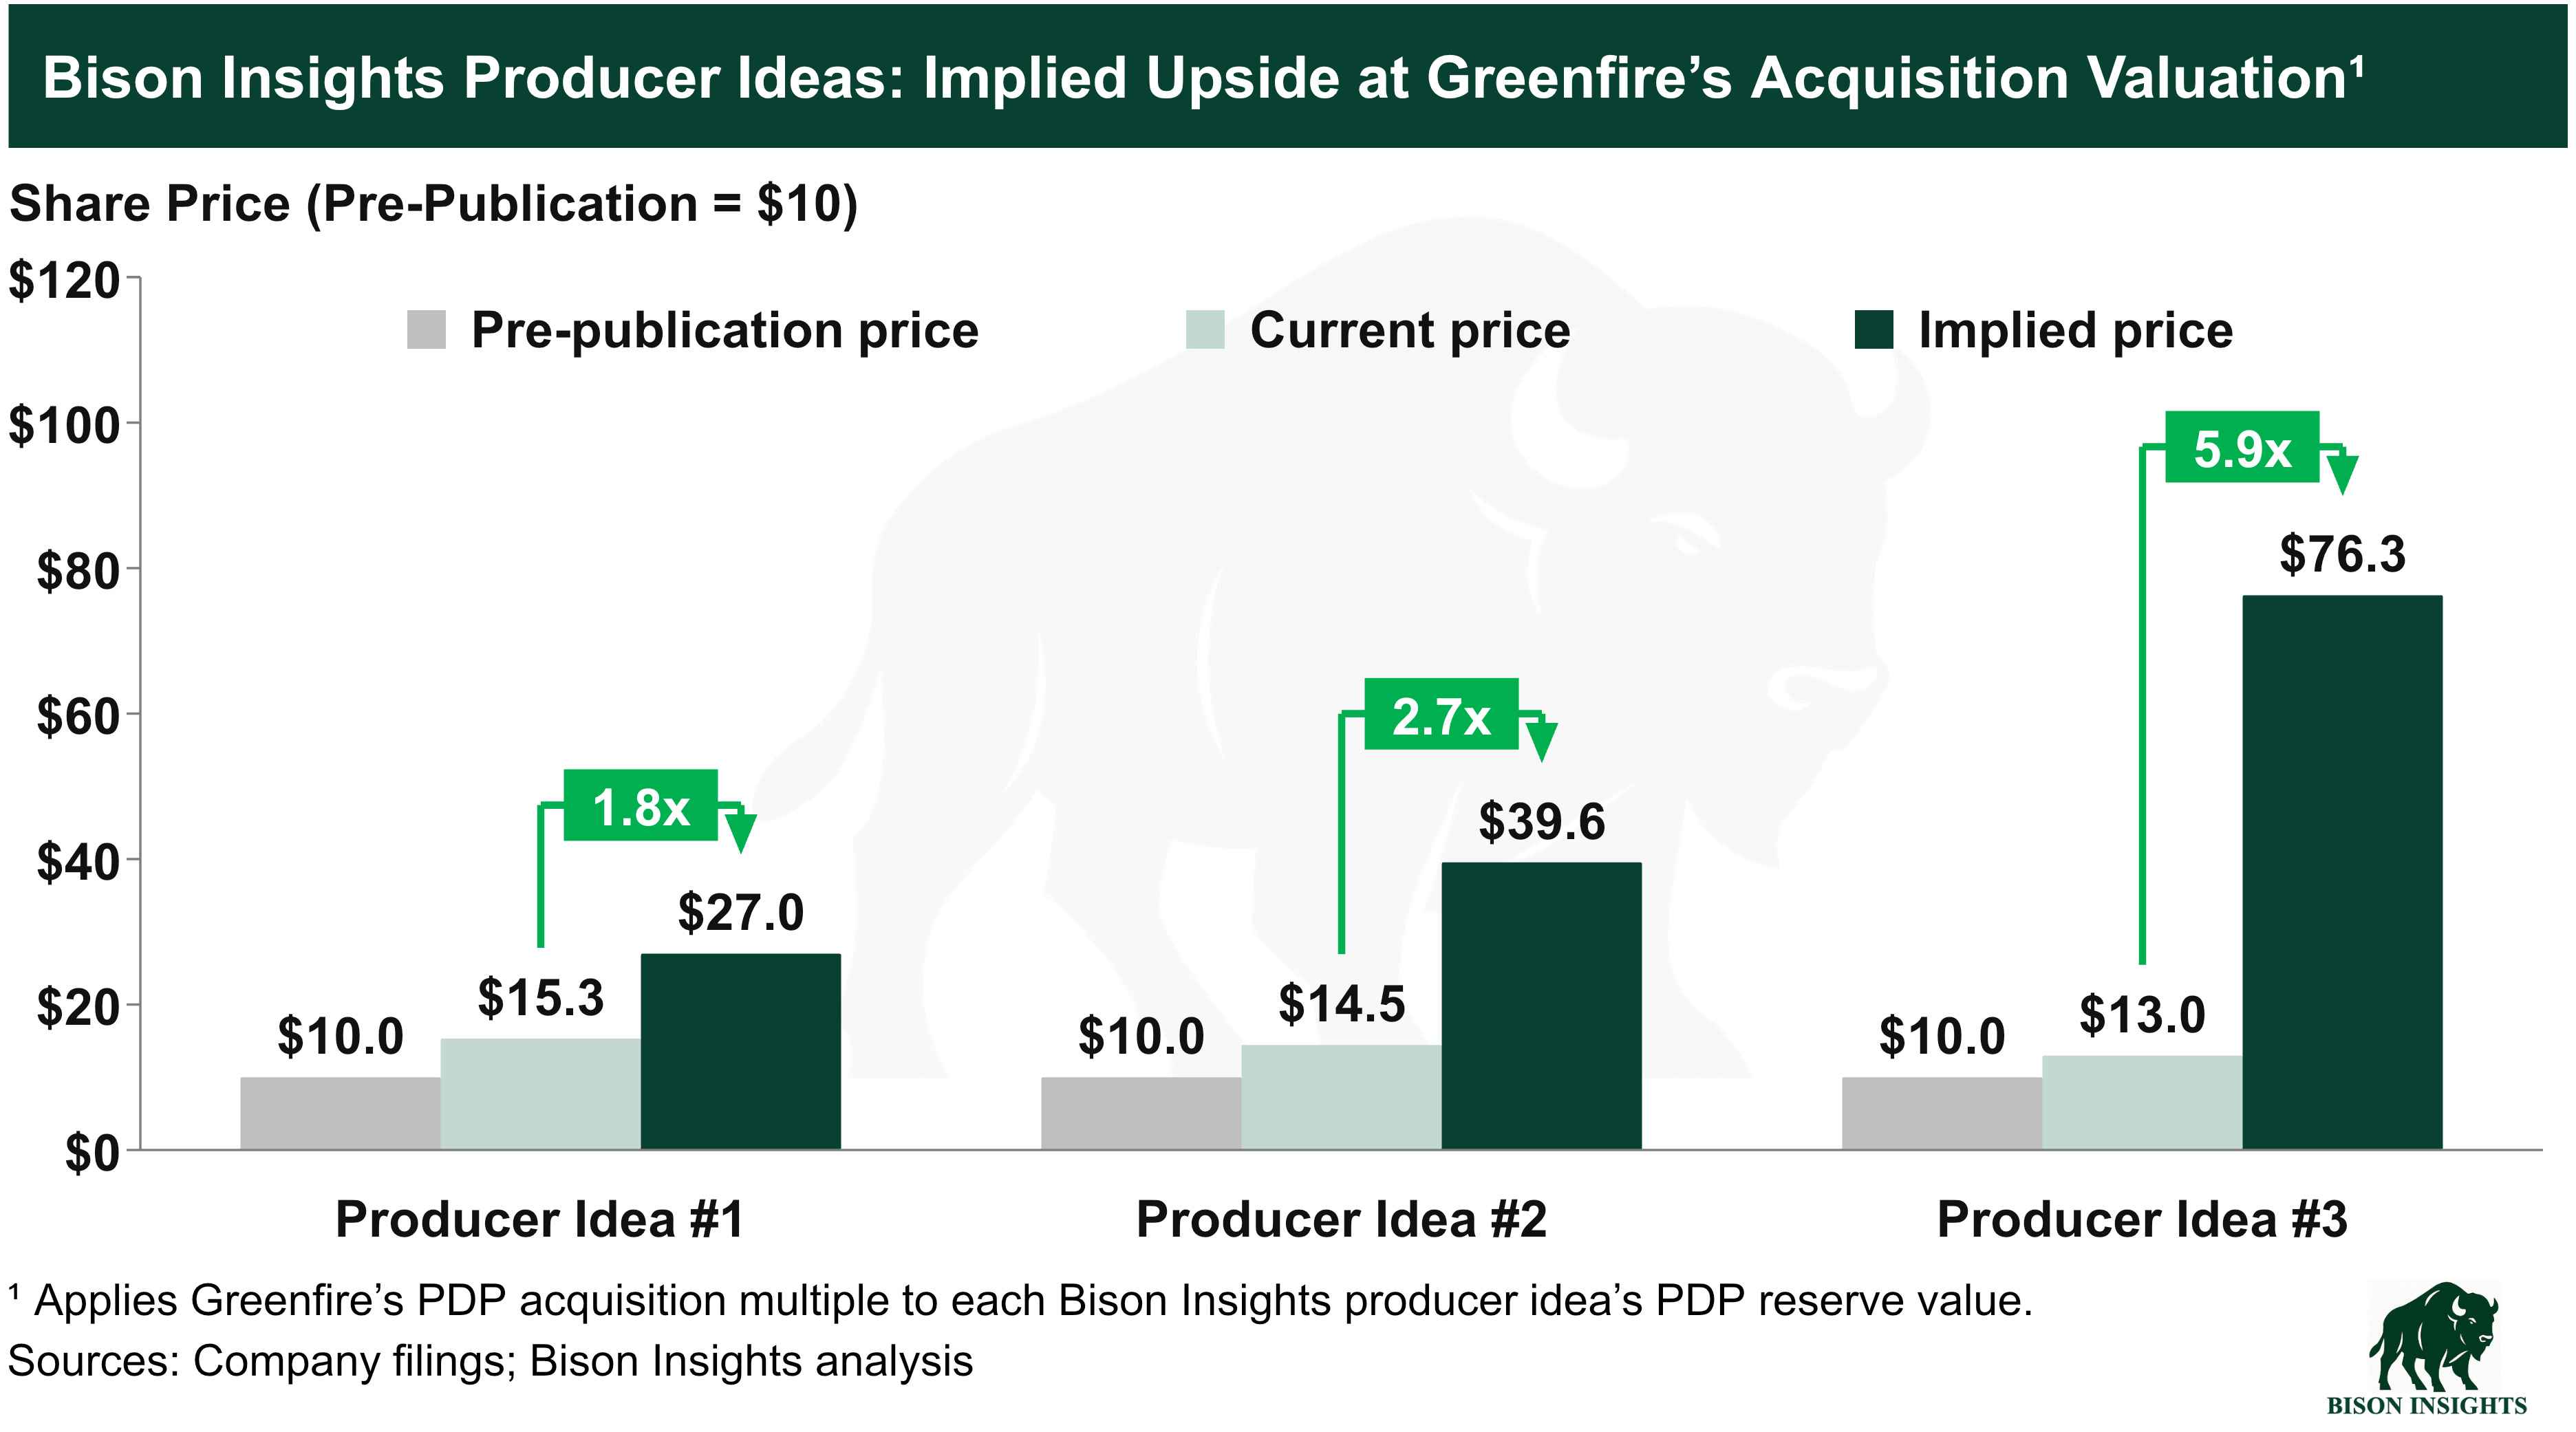
Strathcona Resources will acquire Greenfire Resources for C$2.8 billion including debt, valuing the Canadian heavy-oil producer at up to a…

Occidental Petroleum generated $4.3 billion of Q3 EBITDA and cut principal debt to $10 billion, but each $1 WTI decline reduces annual…
"signed a preliminary deal Monday to explore investments" Exxon Takes First Step Toward Investing in Venezuela $XOM
We're not far from a banker pitching $GEV or $CAT on buying $PTON for behind-the-meter power.

$SOC imploding couldn't have happened to a dumber group of assholes.

Yeah, if you're focused on some sort of biofuel or energy play - $GPRE is almost certainly the best play from this point on. $ANDE just paid 4.25x ethanol assets that are very similar to what GPRE has. GPRE likely $30 if not $40+ by end of 2027 especially with higher likelihood of year-round E15 getting passed and with CA E15 beginning 1/1/2027. Plus GPRE spoke on call that they're likely buying back shares from this point on. By end of Q4 GPRE will be in a net cash position, including unmonetized 45Z credits, and is trading at like 3x 2027 EBITDA.
"Sen. Chuck Grassley, R-Iowa, said this week that Republicans should agree to Democrats’ demands for a two-year cost extension on the Supplemental Nutrition Assistance Program in order to pass a farm bill that also allows the sale of #E15 fuel nationwide and year round, DTN/Progressive Farmer reported." $GPRE $ALTO

$CKX situation is a good reminder that there's shellco optionality in these nanocaps.

@kingdomcapadv I still cannot believe something happened to $CKX This must be AI slop😅
Nextracker's $6 billion order book supports cross-selling battery storage and inverters, now 22% of revenue, though acquisition-led growth…
 Investor Overview 4 clicks

$IPCO buybacks restarted, Waterous taking out $GFR as expected... SAGD assets consolidating quickly
Blue Dolphin Energy trades near 1.3 times earnings as its Texas refinery benefits from diesel shortages, with projected 2026 EBITDA of $111…
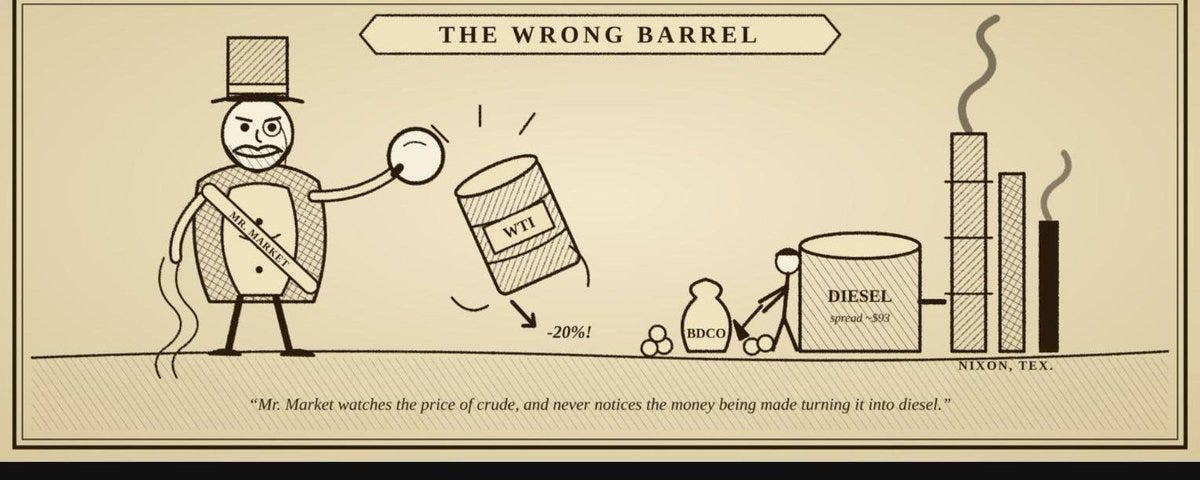
Blue Dolphin’s 15,000-barrel-per-day Texas refinery earned $2.18 per share in first-half 2026 as diesel shortages widened crack spreads,…
Western Midstream targets $3.2 billion EBITDA and $2.3 billion distributable cash flow in 2027 as Pathfinder Pipeline and North Loving II…
 Melissa Tucker

David and I also discussed Japan, oil, AI, prediction markets, Elon Musk and $SPCX, Taiwan and Ukraine, and numerous other topics. We also provide a recap of several investment ideas that we shared at our recent conference. Full interview is here: 2/2
 HNRG · long
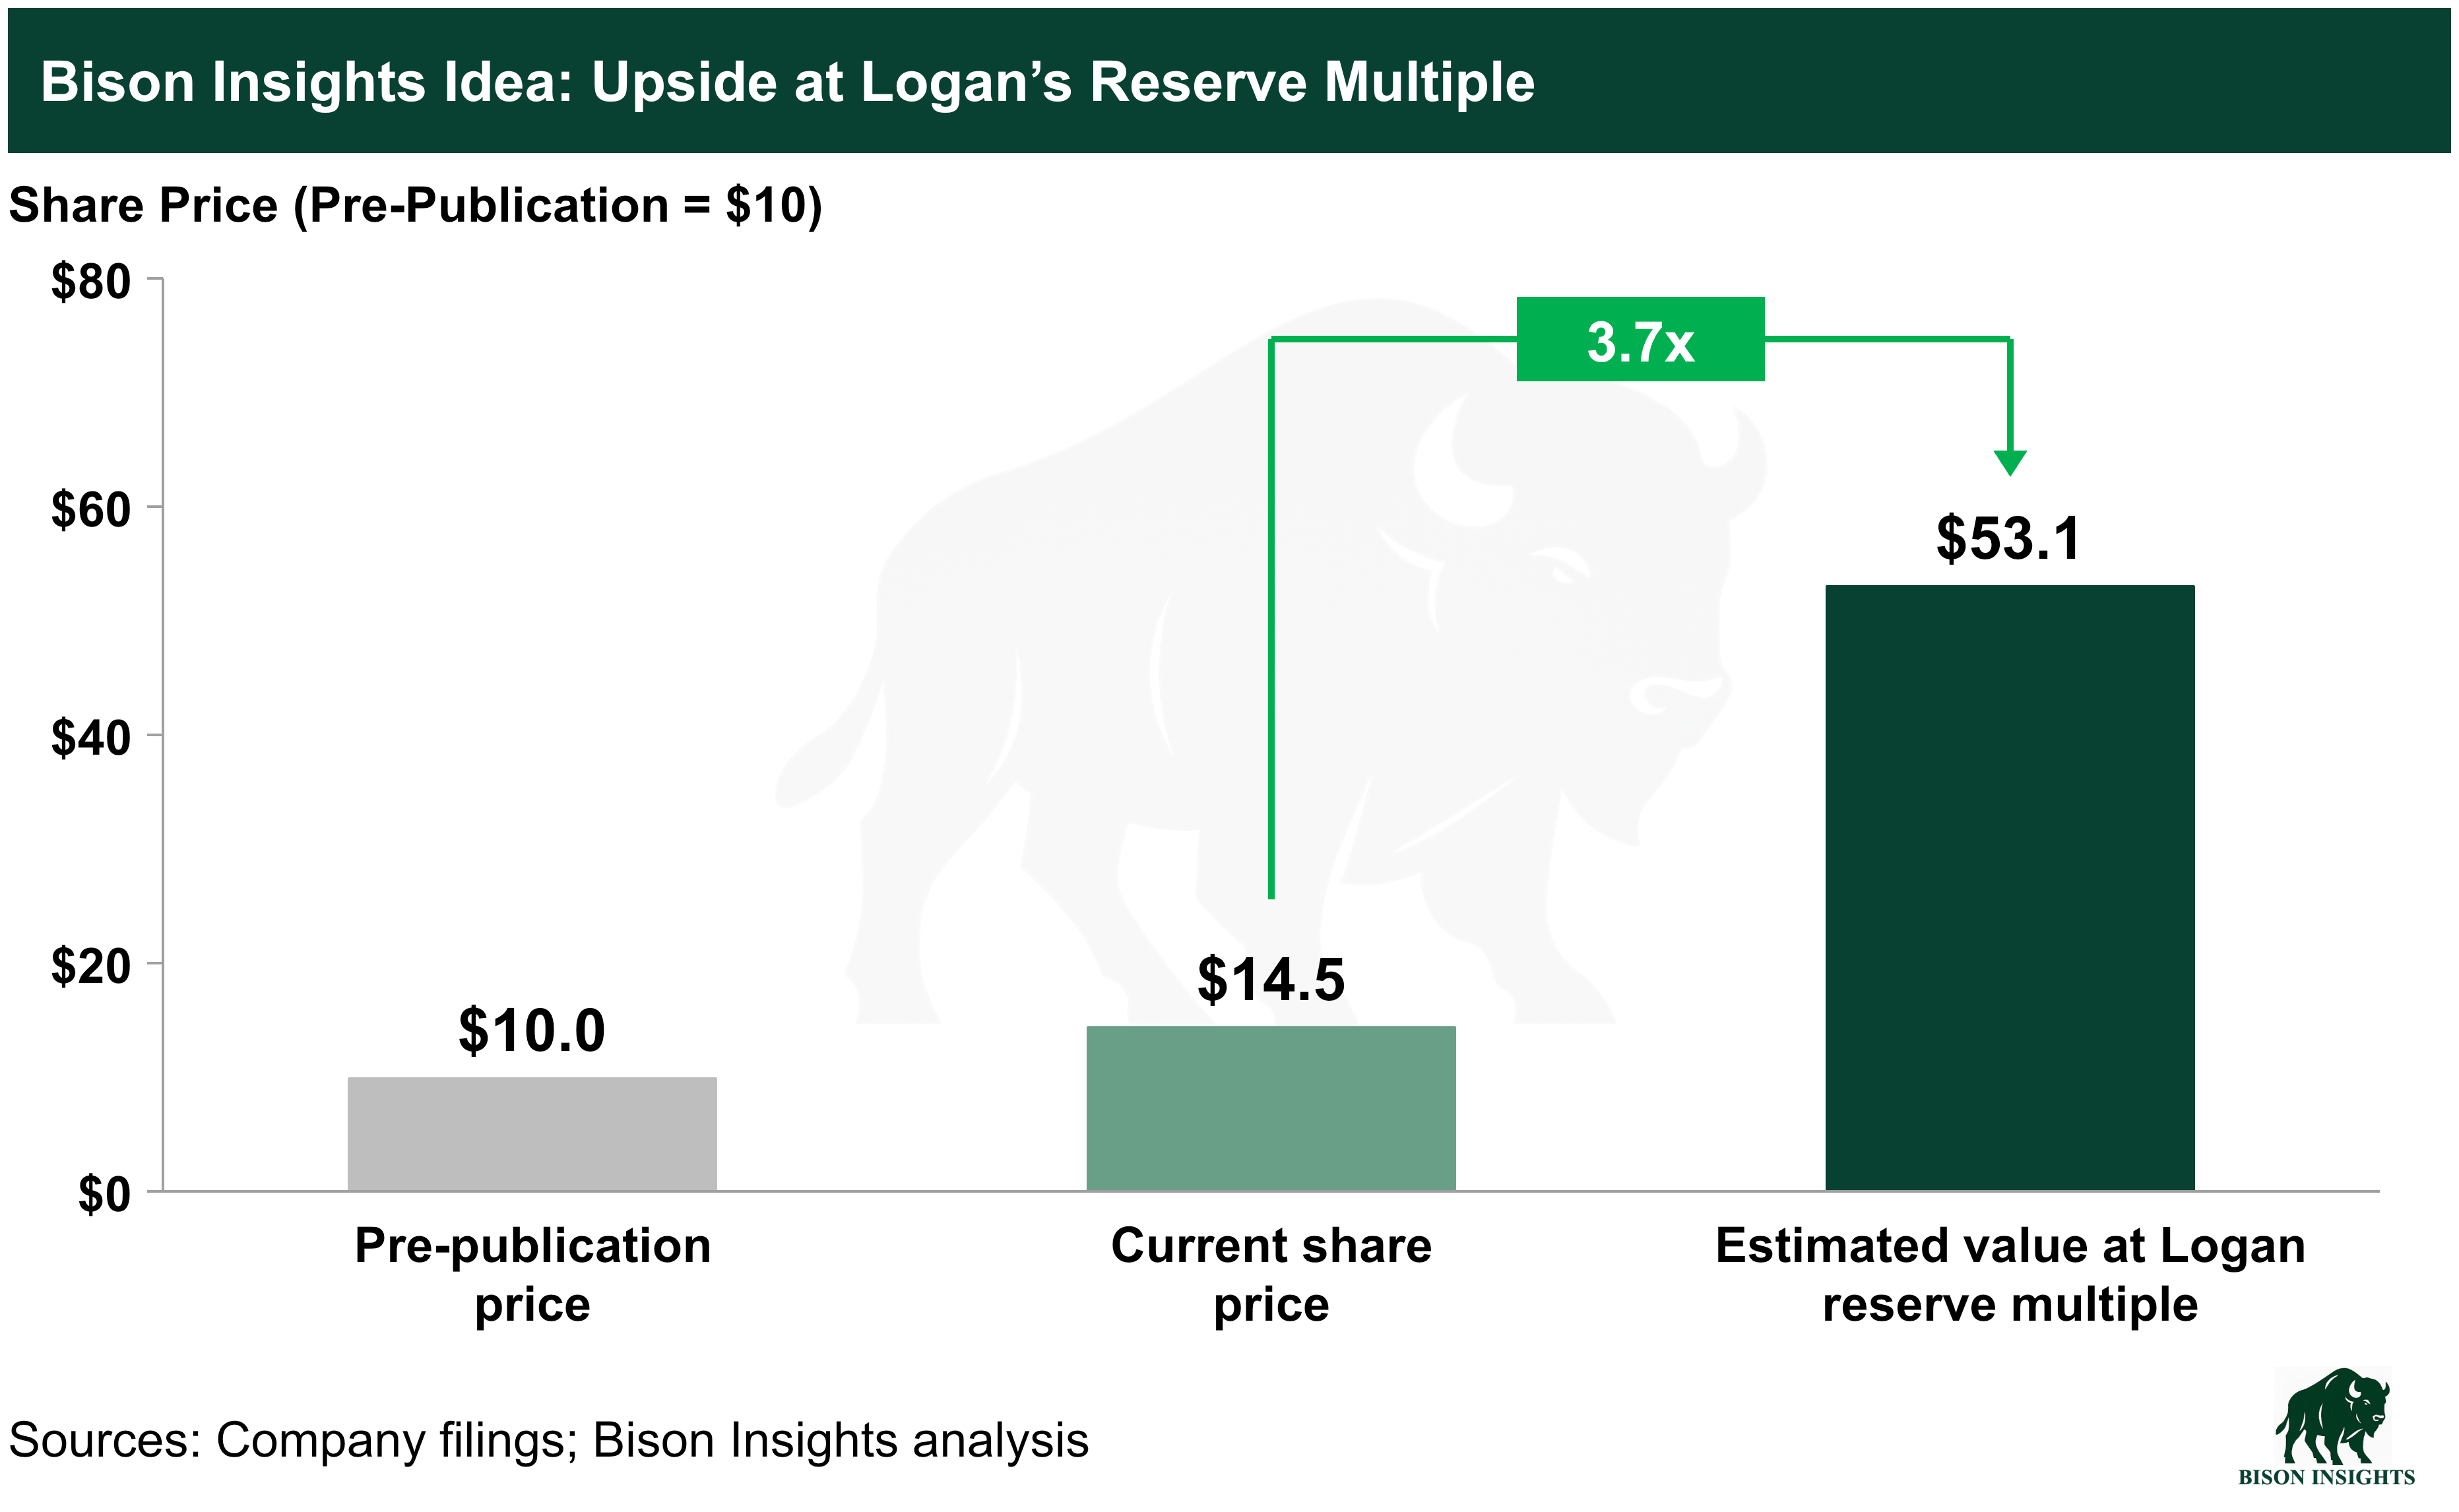
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
Transocean’s 25.6% selloff reflects oil-market shorting and weak Q3 headlines, while debt reduction after the Valaris acquisition could…
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
@HunterAllen4 And what keeps the Navy locked in is licensing. Only two U.S. plants hold NRC licenses to make fuel from high-enriched uranium, and both are $BWXT's, Erwin and Lynchburg. The 10-K calls Nuclear Fuel Services the sole provider of Navy fuel.
Western Midstream raised 2026 EBITDA guidance by $250 million to at least $2.85 billion as organic projects and the Brazos Delaware…
 Gary Gambino
Over the next three years $GPRE earnings are going to exceed its entire enterprise value.... That's insane and it isn't based on any temporary factor such as the Iran war. These are durable, sustainable earnings. How does the market possibly come to a $14 valuation on this? Insane.
EQT becomes the largest U.S. natural-gas producer after acquiring Range Resources, with takeover speculation centered on Berkshire Hathaway…
@WaterworldCapi1 Do you like any of the power shell names? $WULF seems more interesting
There is a reason $ANDE just paid 4.25x ethanol production for three ethanol plants. Based on that - $GPRE would be valued at least at $35 per share factoring in converts if not $40+. The market is completely missing this (and $ALTO)! An acquisition literally just validated this days ago.
$GPRE has generated ~$280M of EBITDA through the first 9 months of the year. Based on today's report, $GPRE enterprise value as of 9/30 was ~$1.3B which does not include the 45Z credits. If we include them... EV = $1.085B. Are you kidding me? How is this stock not $30+???

Data centers need power delivered on schedule, not just efficient generation. $EROC builds on-site power systems around natural-gas reciprocating engines, a different technology from the turbines in short supply. These engines can supply AI data centers before grid connections or gas turbines become available. In our view, their role is broadening from temporary backup toward sustained operation as turbine shortages persist. 1. ERock has a 470MW equipment order from Anthropic. 2. It is delivering a 366MW generation project with El Paso Electric to support $META’s data-center campus, with initial commercial operation targeted for mid-2027. 3. Production commitments extend into 2028, giving ERock demand visibility while making assembly capacity and delivery execution more important. ERock sources engine assemblies from specialists, then integrates them with electrical equipment and control software. In our view, that ability to commission a complete power system quickly is the company’s main advantage. For a customer with computing equipment waiting for electricity, earlier delivery can outweigh the higher fuel efficiency of a combined-cycle plant. Delays or cost overruns would weaken that case. In our view, the next test is whether ERock can convert these commitments into operating systems on schedule and profitably.

@Kyle_Landau_88 stricter energy policy good for $BE
@ChrisMi99288379 data center build out could slow but stricter energy policy for data center build out probably helps $BE
$ANDE just paid 4.25x ethanol production to acquire three ethanol plants in North Dakota and Indiana: I expect further consolidation.... both $ALTO and $GPRE trade at <1x ethanol production and have similar 45Q and 45Z benefits. Huge upside for these two...

@fundiescapital $OKLO straight down from $200 to $20. Another Sam Altman master class.

Fair point, but that’s precisely why I prefer expressing this as a relative-value trade rather than an outright long on refining. I’m not underwriting peak-cycle margins. The question is whether $CVI’s 13% puke reflects a deterioration in relative intrinsic value or simply the market reflexively punishing a leveraged, dilutive acquisition at the top of the cycle. Those are two very different things…
@FishtownCap I understand the reaction, but $CVI paid ~3.5x 2026E EBITDA. The fact that refining equities have rallied 200% doesn’t necessarily mean the assets were purchased at an inflated valuation. The real question is what normalized EBITDA looks like. That’s where the debate should be…
Someone convince me that $CVI underperforming the entire refining complex by ~15–20% in two days is fundamentally justified, rather than a knee-jerk reaction to the acquisition compounded by technical selling from the equity raise. I understand the dilution, leverage, and cycle concerns. But this looks like an extraordinary relative-value dislocation…
On $FLNC departures 😵
Fantastic quarter from $ALTO - massive beat. 45Z credits continue to expand. Columbia now at $0.30 / gallon! Looks like a run rate of >$7M a quarter now. Management confirmed they expect exports to Europe to resume in 2027 - a large reason being the depreciation of the Brazilian Real post Brazilian elections... ALTO Adjusted EBITDA was pretty stunning. Despite lower crush margins they essentially matched Q3 2026. They can now produce profitable quarters, quarter after quarter, even if crush margins are low. The company paid off another $6.5M in debt and has now paid off $26.5M YTD on a loan that has a 10% interest rate. Sounds like Pekin will be at either a $0.30 or $0.40 / gallon run-rate in 2027 as they have also been able to partner with farmers to purchase low carbon corn. Some of these additional profits will be shared with the farmer. Sounds like we'll also get an update soon on Pekin CO2 monetization opportunities to get the 45Q utilization credit on currently vented CO2 from the wet mills. Columbia is also having the extra CO2 storage tank installed in Q4. Management has yet to guide the additional millions the Columbia plant will earn in 2027 due to this - would expect an update on the next call. Fantastic earnings, fantastic call... stock should be much higher. Management additionally confirmed that zero shares were sold using the ATM and that it wasn't contemplated at all even when the shares were in the $5-$6 range and certainly not now. This should be of zero concern at these levels.
Energy Fuels' $UUUU made $54.86 of gross profit on each pound of uranium it sold in Q3, nearly 3x the $19.16 of a year ago, as its realized price rose to $88.90/lb and its cost fell to $34.04/lb. Grade at its Pinyon Plain mine in Arizona recovered to 1.04% from Q2's 0.71%, as management expected, but $UUUU mined just 385k pounds in Q3, so its unchanged 2.0-2.5M guide needs 875k-1.375M mined in Q4, more than double Q3's pace. Heavy rare earth prices jumped in Q3, with European dysprosium oxide up 150% to $3,500/kg and terbium oxide up 42% to $6,745/kg ($8,250 as of October 30), the two oxides $UUUU's ~$104M heavy rare earth circuit is being built to make from as early as Q1 2028. At October 30 prices, a full year at that circuit's capacity, up to 21 tonnes of terbium oxide and 122 of dysprosium oxide, would sell for ~$600M, if prices hold and the Donald Project, an Australian mineral sands mine it's earning into, gets built to supply the feed. The net loss tripled to $52.4M, but $28.0M of it was other loss, mostly mark-to-market losses on its securities portfolio, and $9.0M was deal costs. $UUUU sold no stock through its at-the-market (ATM) program in Q3, but buying VAC, the German magnet maker it agreed to acquire in June, still takes ~$718M of cash at a close expected as soon as Q1 2027. That cash would turn ~$156M of net cash ($856M of cash and securities less the $700M convertible) into ~$560M of net debt, unless $UUUU sells more stock first. At ~$7.18/share, $UUUU is a ~$1.90B company, below the $8-10 bear case in my June deep dive and below the $2.0-2.5B I put on just the uranium business plus net cash in my August 10 update. So I read $7.18 as the market pricing the VAC cash call and more ATM sales, not the uranium margins or the rare earth prices, which both moved $UUUU's way in Q3. Some questions on my mind: 1) Funding: How much of the new $500M ATM $UUUU sells below $8, and whether the $725M government loan finalizes first. 2) Mining: Whether Q4 mined pounds reach the 875k-1.375M that the 2.0-2.5M guide needs. 3) Donald: Whether the Donald Project reaches a final investment decision by year-end, since its monazite sand is the feed the heavy rare earth circuit is sized for.
And btw I love $FSLR and am admitting this…
Peabody $BTU collapsing faster than my "performance" in bed with my wife.

BREAKING: $BTU management expects Centurion to turn profitable sometime this century.
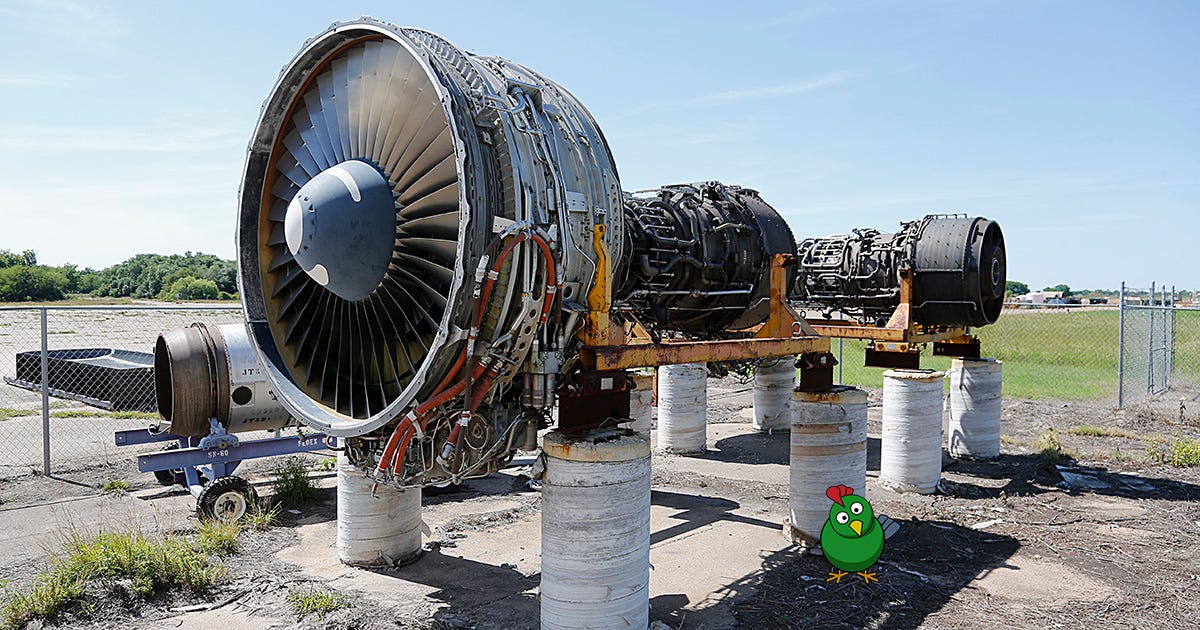
Used aircraft engines can be repurposed as gas turbines, easing data center power constraints while tightening aviation supply.
The 13% puke today is the market questioning whether $CVI is using peak-cycle earnings to justify a transformative acquisition (nearly doubling nameplate capacity). The $MPC assets may be attractive, but shareholders are absorbing dilution, additional debt, and the risk that refining margins normalize before the company can meaningfully delever… $CVI was always sub-scale, so there’s a legitimate strategic rationale here. The irony is that the best time to buy cyclical assets is usually when you can least afford to finance them…
TOYO Co., Ltd $TOYO went from a $123.9M working capital deficit and a going-concern warning to $29.8M of positive working capital in six months. Here’s the balance sheet: → Cash: $103.5M as of June 30, plus $20.0M of restricted cash, up from $51.6M as of December 31, helped by $52.6M of net proceeds from the June offering and its at-the-market (ATM) program. → Debt: $25.7M of short-term bank loans and $51.4M owed on the VSUN loan, including interest, which VSUN (the Vietnamese panel maker $TOYO was carved out of) extended to June 17, 2028, plus $37.6M of leases. → Working capital: $29.8M, vs. a $123.9M deficit as of December 31 that had drawn the auditor’s going-concern paragraph. The $52.6M of offering and ATM cash and the VSUN extension, which moved the $51.4M loan out of current liabilities, account for $104.0M of the $153.7M improvement, and $TOYO said substantial doubt no longer exists. → Customer prepayments: $114.0M of contract liabilities (products customers have paid for but $TOYO hasn’t delivered), including $64.7M from related parties. Before June 30, current liabilities had exceeded current assets at every balance sheet date since December 2023. The June offering (4,545,456 shares at $11.00) and the ATM (414,495 shares at an average $13.78) also raised $TOYO’s share count 13.1% to 42.7M as of June 30, from 37.8M as of March 31. So the balance sheet is no longer the risk it was in March, but part of the cash is customers’ prepayments, and the $51.4M VSUN loan comes due in June 2028.
Watch prison companies like $GEO and coal names like $BTU. If dems sweep these probably fall and become buying opportunities.
Transocean enters its Valaris merger with 109 of 110 available deepwater rigs contracted and 313 million shares sold short, despite weaker…
Enterprise Products Partners has pulled growth spending into 2026, while Energy Transfer’s contracted projects offer clearer EBITDA growth…
 The Alpha Analyst 5 clicks
Read the 6-K’s explanation of the margin increase here: Continue reading here for what $TOYO’s balance sheet looks like after the June offering:
Read the 8-K on all three exits here: Here’s my September 21 update on $FLNC (free to read):
Fluence Energy’s $FLNC CEO, CFO, and chief customer success officer just left on October 30, effective immediately, six weeks after its fourth guidance cut in 19 months! The press release says CEO Julian Nebreda, CFO Ahmed Pasha, and John Zahurancik “stepped down.” But the 8-K says all three will be eligible for benefits under $FLNC’s executive severance plan, which only pays out on an involuntary termination or a “good reason” resignation. So I read the exits as the board pushing all three out. The interim CEO and CFO come from $FLNC’s two co-founders and major shareholders, Siemens $SIEGY and $AES: → Interim CEO Axel Meier: Retired in June as CFO of Siemens’ Smart Infrastructure division and has been a $FLNC director since January 2020, through all four guidance cuts. → Interim CFO Ricardo Roizen: A former CFO of AES Andes, a Chile-based AES affiliate, seconded for up to 90 days unless extended, with AES Andes still paying his salary. With Bernerd Da Santos, AES COO from 2017 to 2023, running operations since September 15, Siemens and AES veterans now hold $FLNC’s CEO, CFO, and COO seats. Nebreda, Pasha, and Zahurancik all came from AES as well, so the board hasn’t turned to outsiders for the top three seats, at least until its searches for a permanent CEO and CFO finish. AES also buys $FLNC’s systems and negotiates change orders and settlements with $FLNC, so the interim CFO is now on a customer’s payroll. $FLNC also delayed its FY2027 guidance. Pasha said on September 16 that $FLNC planned to provide “a detailed business plan and a financial update for fiscal year 2027” when it reported FY2026 results. The November 2 release now says FY2027 guidance “is expected to be provided at a later date.” So the FY2026 results on November 23 will show how Q4 went, but not how much of the ~$2.9B of backlog scheduled for FY2027 $FLNC expects to deliver. The release says $FLNC is prioritizing profitable growth “through disciplined pricing and a streamlined cost structure,” which I read as fewer low-margin orders and cost cuts. At ~$5.40/share, $FLNC trades between the $3.93 bear case and the $7.67 low end of the base case in my September 21 update. Would you say replacing Nebreda and Pasha was overdue? But with an interim CEO, a CFO on loan from AES, and no FY2027 guide, I’d rather see three numbers before giving the new team any credit: 1) Revenue: Q4 vs. the ~$810M the September guide implied. 2) Houston: Output at the contract manufacturing plant behind most of the September 16 cut, vs. the 11 units/day it was supposed to run. 3) Cash: The balance as of September 30, vs. $365M as of June 30.
@kiwicarrotcake still might be a good gamble. Just saying that sure as night follows day, $OKLO will spend some of its kitty and probably not wisely.
those assumptions though. - given trajectory of capex, don't you think it will continue in 2026? - given history of dilution, more seems likely - $OKLO did 3 acquisitions in 2026 afaik (Atomic Alchemy, ARMEC, Creative Engineers). Assuming none in the next 13 months seems unlikely.
Peabody $BTU is looking pretty good here imo. I’m sure they will screw up Centurion and will fall post earnings but it’s cheap here with irreplaceable assets and no net debt.
This is a “just sell shitcos everyday” no matter the technicals kind of market. $QBTS $OKLO $DJT $RGTI
At what price does $SOC become an attractive long-duration call option on the eventual restart of Santa Ynez? $3? $2? $1.50? Obviously, the question is whether the equity can survive the liquidity runway without getting diluted into oblivion. But at some price, the asymmetry has to become compelling…
Calumet and other refiners sold off alongside AI names, but the RIN thesis for renewable fuel earnings remains unchanged ahead of Q3…
BP’s profits surge to new record on high fuel prices $BP
Woah, massive $PESI news out tonight... DOE breaks ground on new cleanup system at Hanford Site - Elkhorn Media Group
TOYO Co., Ltd’s $TOYO strategy chief says full output at its Texas panel plant would bring in “about $140 million a year” of U.S. tax credits, 85.6% of its market cap, and $TOYO leaves them out of its forecasts. Regardless of how the four U.S. trade actions on its Ethiopian cells turn out, $TOYO’s answer is to make more in the U.S., which has plenty of panel capacity but few cell plants. The Solar Energy Industries Association’s October update counts 75.3 GW of operating U.S. module capacity, but $TOYO’s deck counts just 3.2 GW of operating U.S. cell capacity, citing SEIA’s September data, so most U.S. panel makers still rely on imported cells. Texas modules qualify for the Section 45X production credit, a U.S. tax credit earned on each unit of solar equipment made in the U.S. For modules, it’s $0.07/W at full value through 2029, then 75%, 50%, and 25% of full value in 2030-2032, and nothing after. $TOYO said on July 21 that its Texas subsidiary expects to be eligible to claim the credits for its 2025 tax year, which covers the plant’s first months of production. But Rhone Resch, $TOYO’s Chief Strategy Officer, said on the Q2 call that $TOYO will quantify the credits only after its tax, legal, and accounting work is done. For the panels themselves, $TOYO announced $185.6M of purchase orders under two master agreements with U.S. developers on June 10, and ~$240M of binding contracts signed “since mid-June” on September 28, with deliveries through H1 2027. The releases don’t say whether the two overlap, so to stay conservative, I only count the ~$240M. If priced like $TOYO’s H1 2026 module sales (~$0.25/W), ~$240M would be ~1 GW of panels, or ~6 months of the Texas plant’s 2 GW nameplate.
Chevron’s Q3 revenue rose 35% to $65.2 billion and EBITDA 75% to $20.2 billion, while production trailed guidance and refining margins…
@SamSamutecht I can’t tell you what to buy but I’m meaningfully long $AMZN, $BE and $HOOD. My investment objectives and risk tolerance may be very different from yours. What makes sense for me might not make sense for you.

Sold some of my $PAA calls that I bought on April 1st as hedges against the Iran War crisis Just sold them for roughly 4x Was kind of mad at myself for not buying refiners but then realized that I did okay with these MLP calls/LEAPs @blondesnmoney would appreciate this Good enough to post, good enough to sell as my analyst would say

nearly the entirety of big pharma and big oil making fresh 52 week highs today..... $LLY $XOM $JNJ $GILD $CVX $ABV $COP $LNG $AMGN etc etc all 52 Week highs
nearly the entirety of big pharma and big oil making fresh 52 week highs today..... dems gonna take the senate... $LLY $XOM $JNJ $GILD $CVX $ABV $COP $LNG $AMGN etc etc all 52 Week highs
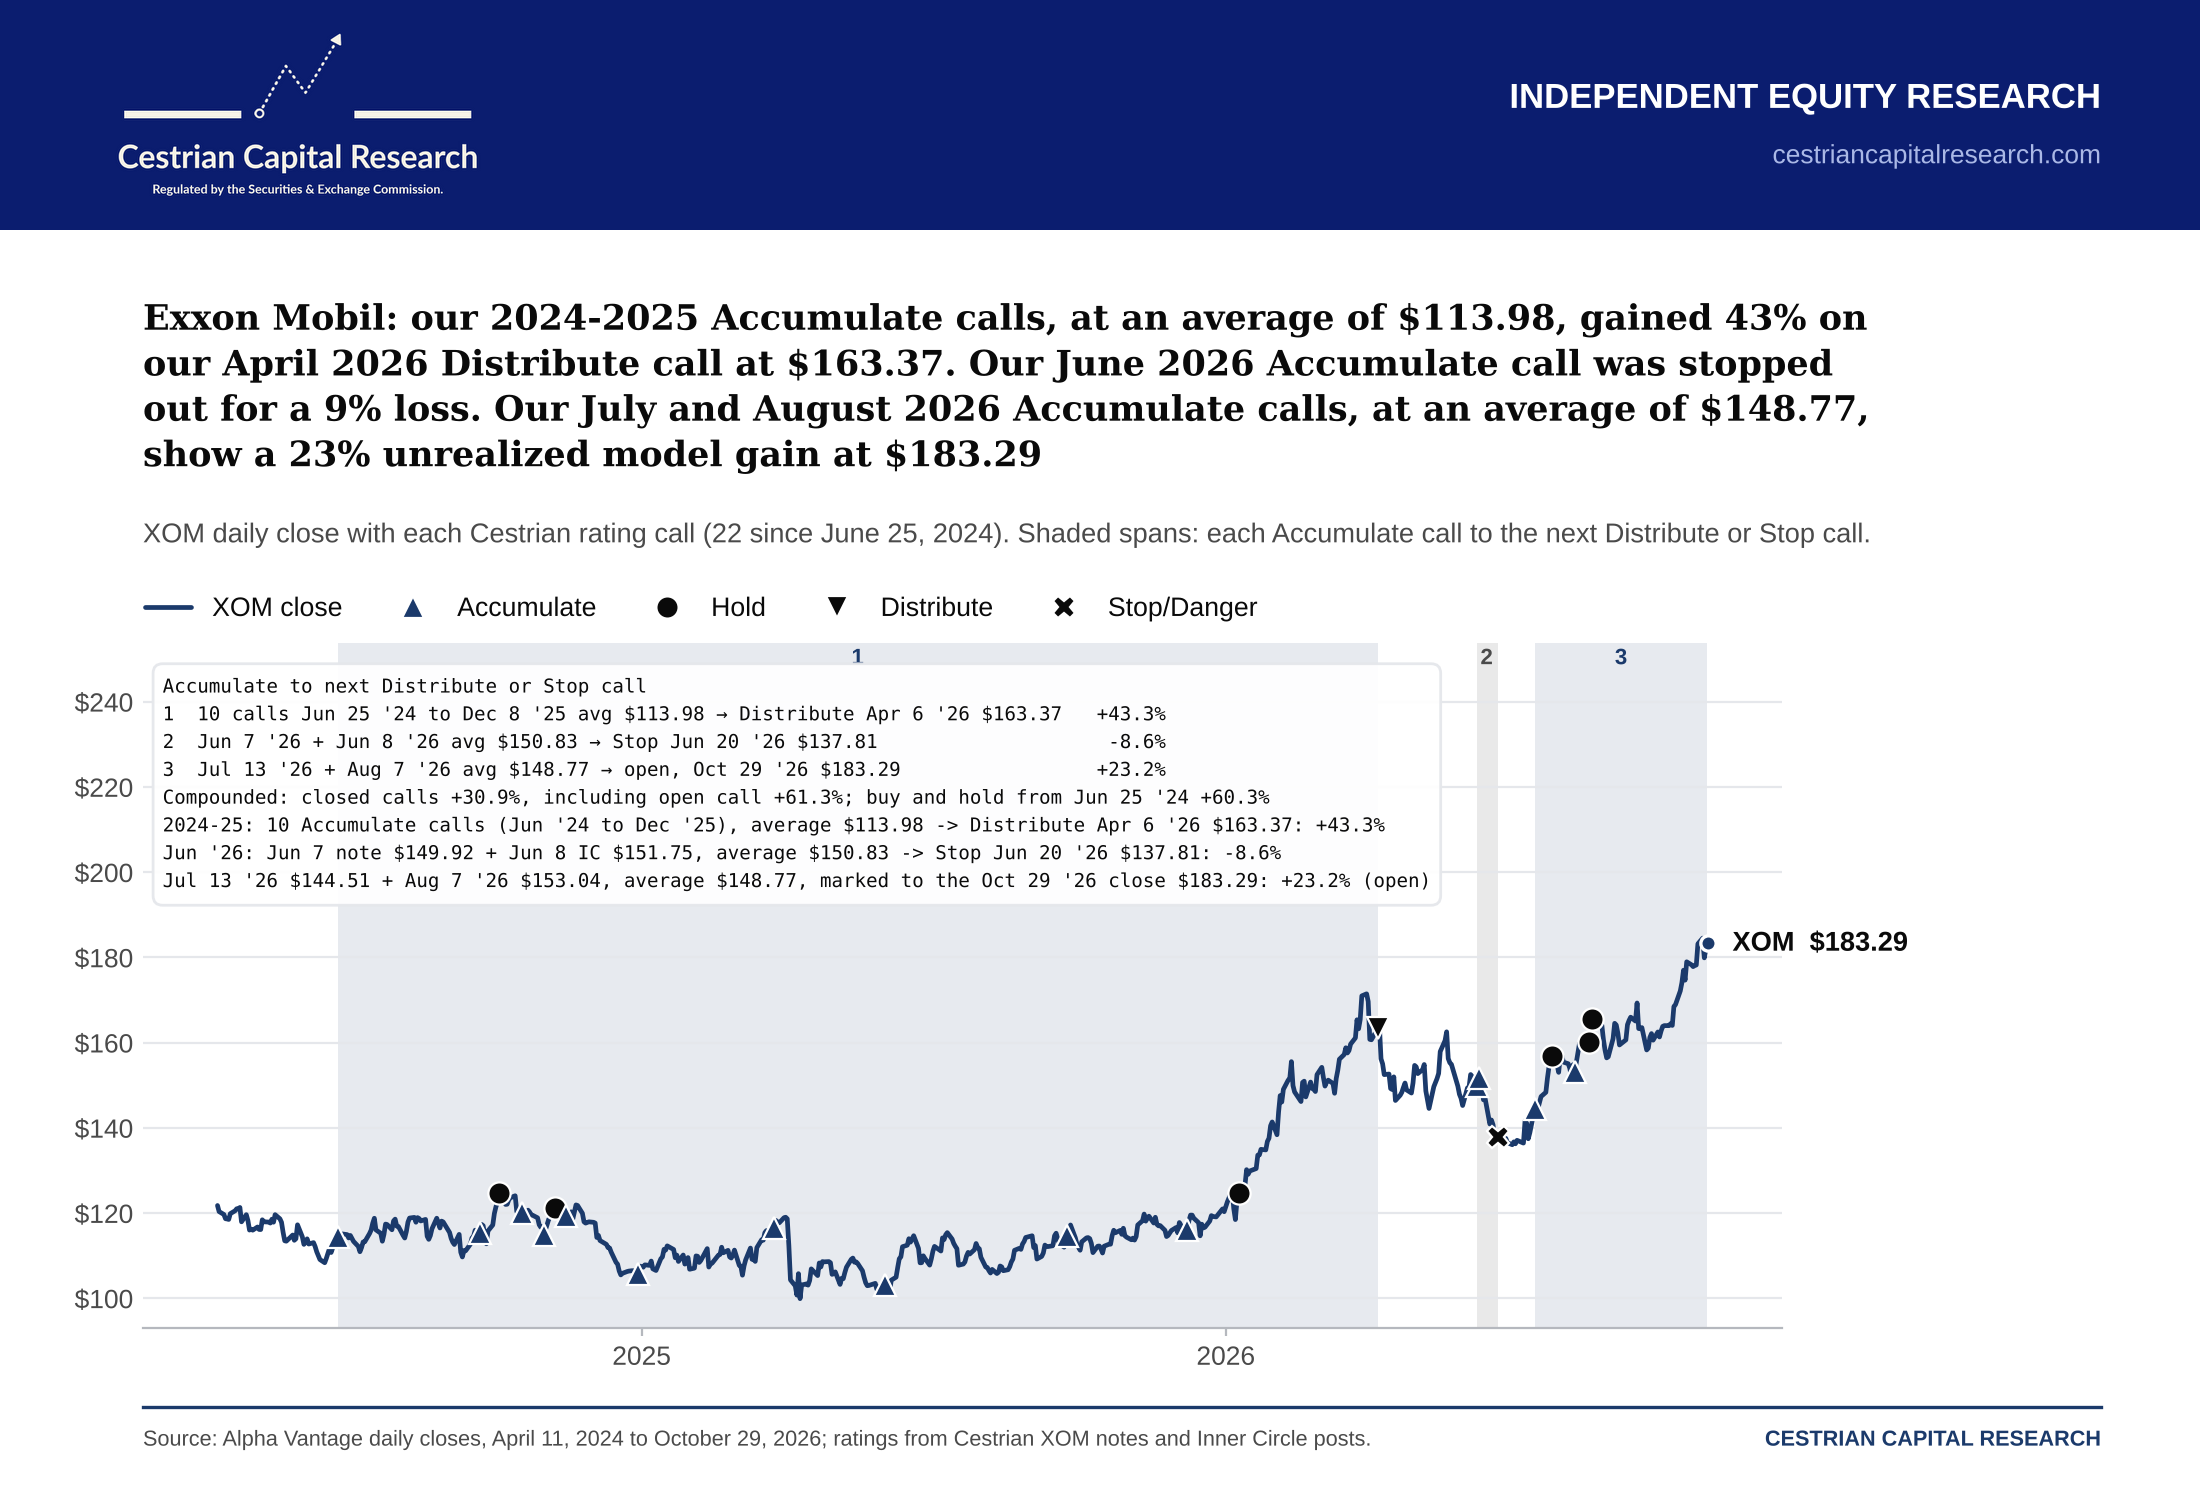
ExxonMobil’s Q3 revenue rose 33% to $113.2 billion as refining earned $9.1 billion, surpassing upstream; the company set 2027 buybacks at…

Based on Hunterbrook Media’s reporting, at the time of publication Hunterbrook Capital is short $BE. Positions may change at any time. This thread is not investment advice or any recommendation. See full disclosures on our website.
I expect an earnings beat against analyst estimates. The price of ethanol rocketed during the quarter, and I don't think the market or analysts understand how the $ALTO hedging works on their specialty alcohols. No one noticed by Q2, despite being amazing, was adversely impacted due to this and EPS should have been higher than reported. Q3 should benefit where Q2 was hurt and EPS are likely to be higher than they should be as compared to Adjusted EBITDA.
One of the reasons that Brazil started to take a lot of the ethanol export volume was a sharp appreciation in the Brazilian Real which leads Brazilian producers to favor ethanol vs sugar production. The sharp depreciation in the Real following the election will reverse this and lead to greater sugar production moving forward. Very bullish for $ALTO and $GPRE.
$FSLR interesting here at ~7–8x 2027 earnings with 44GW of contracted backlog. Q3 bookings at ~$0.36/W were largely negotiated pre-232, while management is already quoting higher prices on new business. Think the first meaningful post-232 contracts will be particularly informative as to normalized earnings power and ultimately where this should trade…
Continue reading here for the $357M Texas cell plant $TOYO’s term sheet is tied to:
On December 4, TOYO Co., Ltd’s $TOYO Ethiopian cells start paying a 15% U.S. tariff, unless Commerce approves its request for relief. Section 232 of the Trade Expansion Act of 1962 lets the U.S. president restrict imports that threaten national security. On August 6, 2026, a proclamation added a 15% tariff, from December 4, on the ingots, wafers, cells, and modules made from polysilicon, for Ethiopia and most other countries, plus minimum import prices of $0.22 per watt (/W) for cells and $0.38/W for modules. The proclamation also created an onshoring program, run by Commerce, that grants relief to companies building U.S. polysilicon, wafer, or cell plants, as long as construction under an approved plan begins by January 20, 2029. Section 232 helps $TOYO’s Texas panels but hurts its Ethiopian cells: 1) Texas modules: Imported panels will face the $0.38/W minimum import price from December 4, above the $0.33/W average in Q2 2026 for U.S. utility-scale modules, per the Solar Energy Industries Association (SEIA) and Wood Mackenzie. 2) Ethiopian cells: $TOYO’s cells are imports too, so from December 4, 2026, they pay the 15% tariff and must clear the $0.22/W minimum price. Rhone Resch, $TOYO’s Chief Strategy Officer, said at its October 6 Analyst Day that using Ethiopian cells means $TOYO’s Texas panels are “not a purely U.S. product,” and that $TOYO has presented Commerce a term sheet for onshoring relief tied to its planned Texas cell plant, though he said many such agreements probably won’t come until after December 4. Notably, Jeffrey Kessler, Commerce’s Under Secretary for Industry and Security, praised $TOYO at its October 6 ribbon-cutting in Texas for “committing to use exclusively US polysilicon,” and his department approves onshoring plans. Still, 30% of the polysilicon in $TOYO’s Ethiopian cells comes from Malaysia. CEO Takahiko Onozuka said on the Q2 call that $TOYO anticipates its Ethiopian cells “will be eligible for the relief under the framework now taking shape.” But he also said in the August 19 release that $TOYO expects an impact on its H2 2026 results, “though the magnitude is not yet certain.” So Section 232 should lift prices for $TOYO’s Texas panels, but it taxes the Ethiopian cells those panels are made from unless Commerce approves $TOYO’s term sheet. I won’t be comfortable with Section 232 until Commerce approves the term sheet, and Resch expects many such agreements only after the tariff starts on December 4.
An excerpt from our article about Expand Energy $EXE that we published this morning after Danny Brown took over as the new CEO this week: Natural gas may not be the first thing that comes to mind when you think about the AI boom. But as companies race to build data centers, finding enough electricity to power them is becoming just as important as getting hold of the top GPU chips from NVIDIA $NVDA Expand Energy is a company you might recognize by its old name, Chesapeake Energy. Chesapeake has quite a history. It was one of the biggest names in America’s shale gas boom, built aggressively by its co-founder Aubrey McClendon. But its rapid expansion came with enormous debt, and the company eventually ended up in bankruptcy in 2020. Today, it looks very different. Following its merger with Southwestern Energy, Chesapeake became Expand Energy, creating the largest natural gas producer in the United States. The company is performing well, with our quant model IA Score rating it a 90 (a higher score is better), even though natural gas prices haven’t enjoyed the same strength as oil. That is what caught my attention. Natural gas producers typically do well when gas prices rise and struggle when they fall. Yet Expand appears to be building a business that could benefit from more than just a recovery in commodity prices. And now, with Danny Brown taking over as CEO, the company is entering another interesting chapter. To understand the opportunity and why this company is worth watching, we need to rewind the tape and go back to where it all started: Chesapeake Energy.
Simran Jeet Singh recounts pricing oil through WTI’s -$37.63 collapse, then explains crypto perpetual funding arbitrage, market making and…
Continue reading here for my bear, base, and bull cases for $TOYO at those multiples:
First Solar $FSLR trades at 6.7x TTM EBITDA and 10.4x TTM net income, while TOYO Co., Ltd $TOYO trades at just 0.9x and 2.0x. At $3.83/share, $TOYO has a market cap of $163.6M and an EV of $137.2M ($163.6M + $25.7M of bank loans + $51.4M owed to VSUN, an affiliate - $103.5M of cash). It trades at 0.9x TTM EBITDA of $156.4M, 2.0x TTM net income of $80.5M, and 0.78x its $209.8M of book value. Since 80.7% of its H1 revenue came from U.S. end customers, $TOYO’s closest comps are four other listed solar manufacturers selling into the U.S. (TTM multiples as of the October 26 close): → First Solar $FSLR (U.S. thin-film panel maker): 6.7x EV/EBITDA, 10.4x P/E, 1.75x P/B, and down 47.2% from its 2026 high. → Canadian Solar $CSIQ (panel and battery storage maker): 18.8x EV/EBITDA, a net loss, 0.22x P/B, and down 65.2%. → JinkoSolar $JKS (China-based panel maker): A net loss, 0.19x P/B, and down 72.7%. → T1 Energy $TE (Texas panel assembler building a U.S. cell plant): Negative EBITDA, a net loss, 2.95x P/B, and down 82.4%. So the market prices $TOYO’s earnings at 0.9x EBITDA, less than a seventh of First Solar’s 6.7x, a multiple that only makes sense if the four U.S. trade actions on its Ethiopian cells wipe out most of those earnings. Only $TE has fallen further from its 2026 high. I was originally going to write up T1 Energy until I found $TOYO, which offers a more attractive setup mainly because (1) it’s profitable, with $80.5M of TTM net income vs. T1’s $367.8M net loss, (2) it trades at 0.78x book vs. T1’s 2.95x, and (3) it has $26.4M of net cash vs. T1’s $629.2M of net debt.
GE Vernova raised guidance for a third straight quarter as Power and Electrification drove backlog growth, while Wind showed an early…
Melissa Tucker 2 clicks @ada_lawren $FLNC starts reporting U.S. output vs its own forecast with these results, and Houston was at ~3 units/day in September vs the 11/day plan. FY27 already has ~$2.9B of scheduled backlog, so it comes down to whether they can build it.

Rick Bensignor is on fire Long $OIH vs $XOP The insane alpha valuation continues. Join our conference today. John Roque on deck. Mary Ann Bartels in the hole. Replays to follow. @InTheKnowTrader @dachartlife @RyanDetrick @alphatrends @MarkNewtonCMT @FrankCappelleri @davevermilion

@Stansberry @nickchodge $UUUU oh it is you...
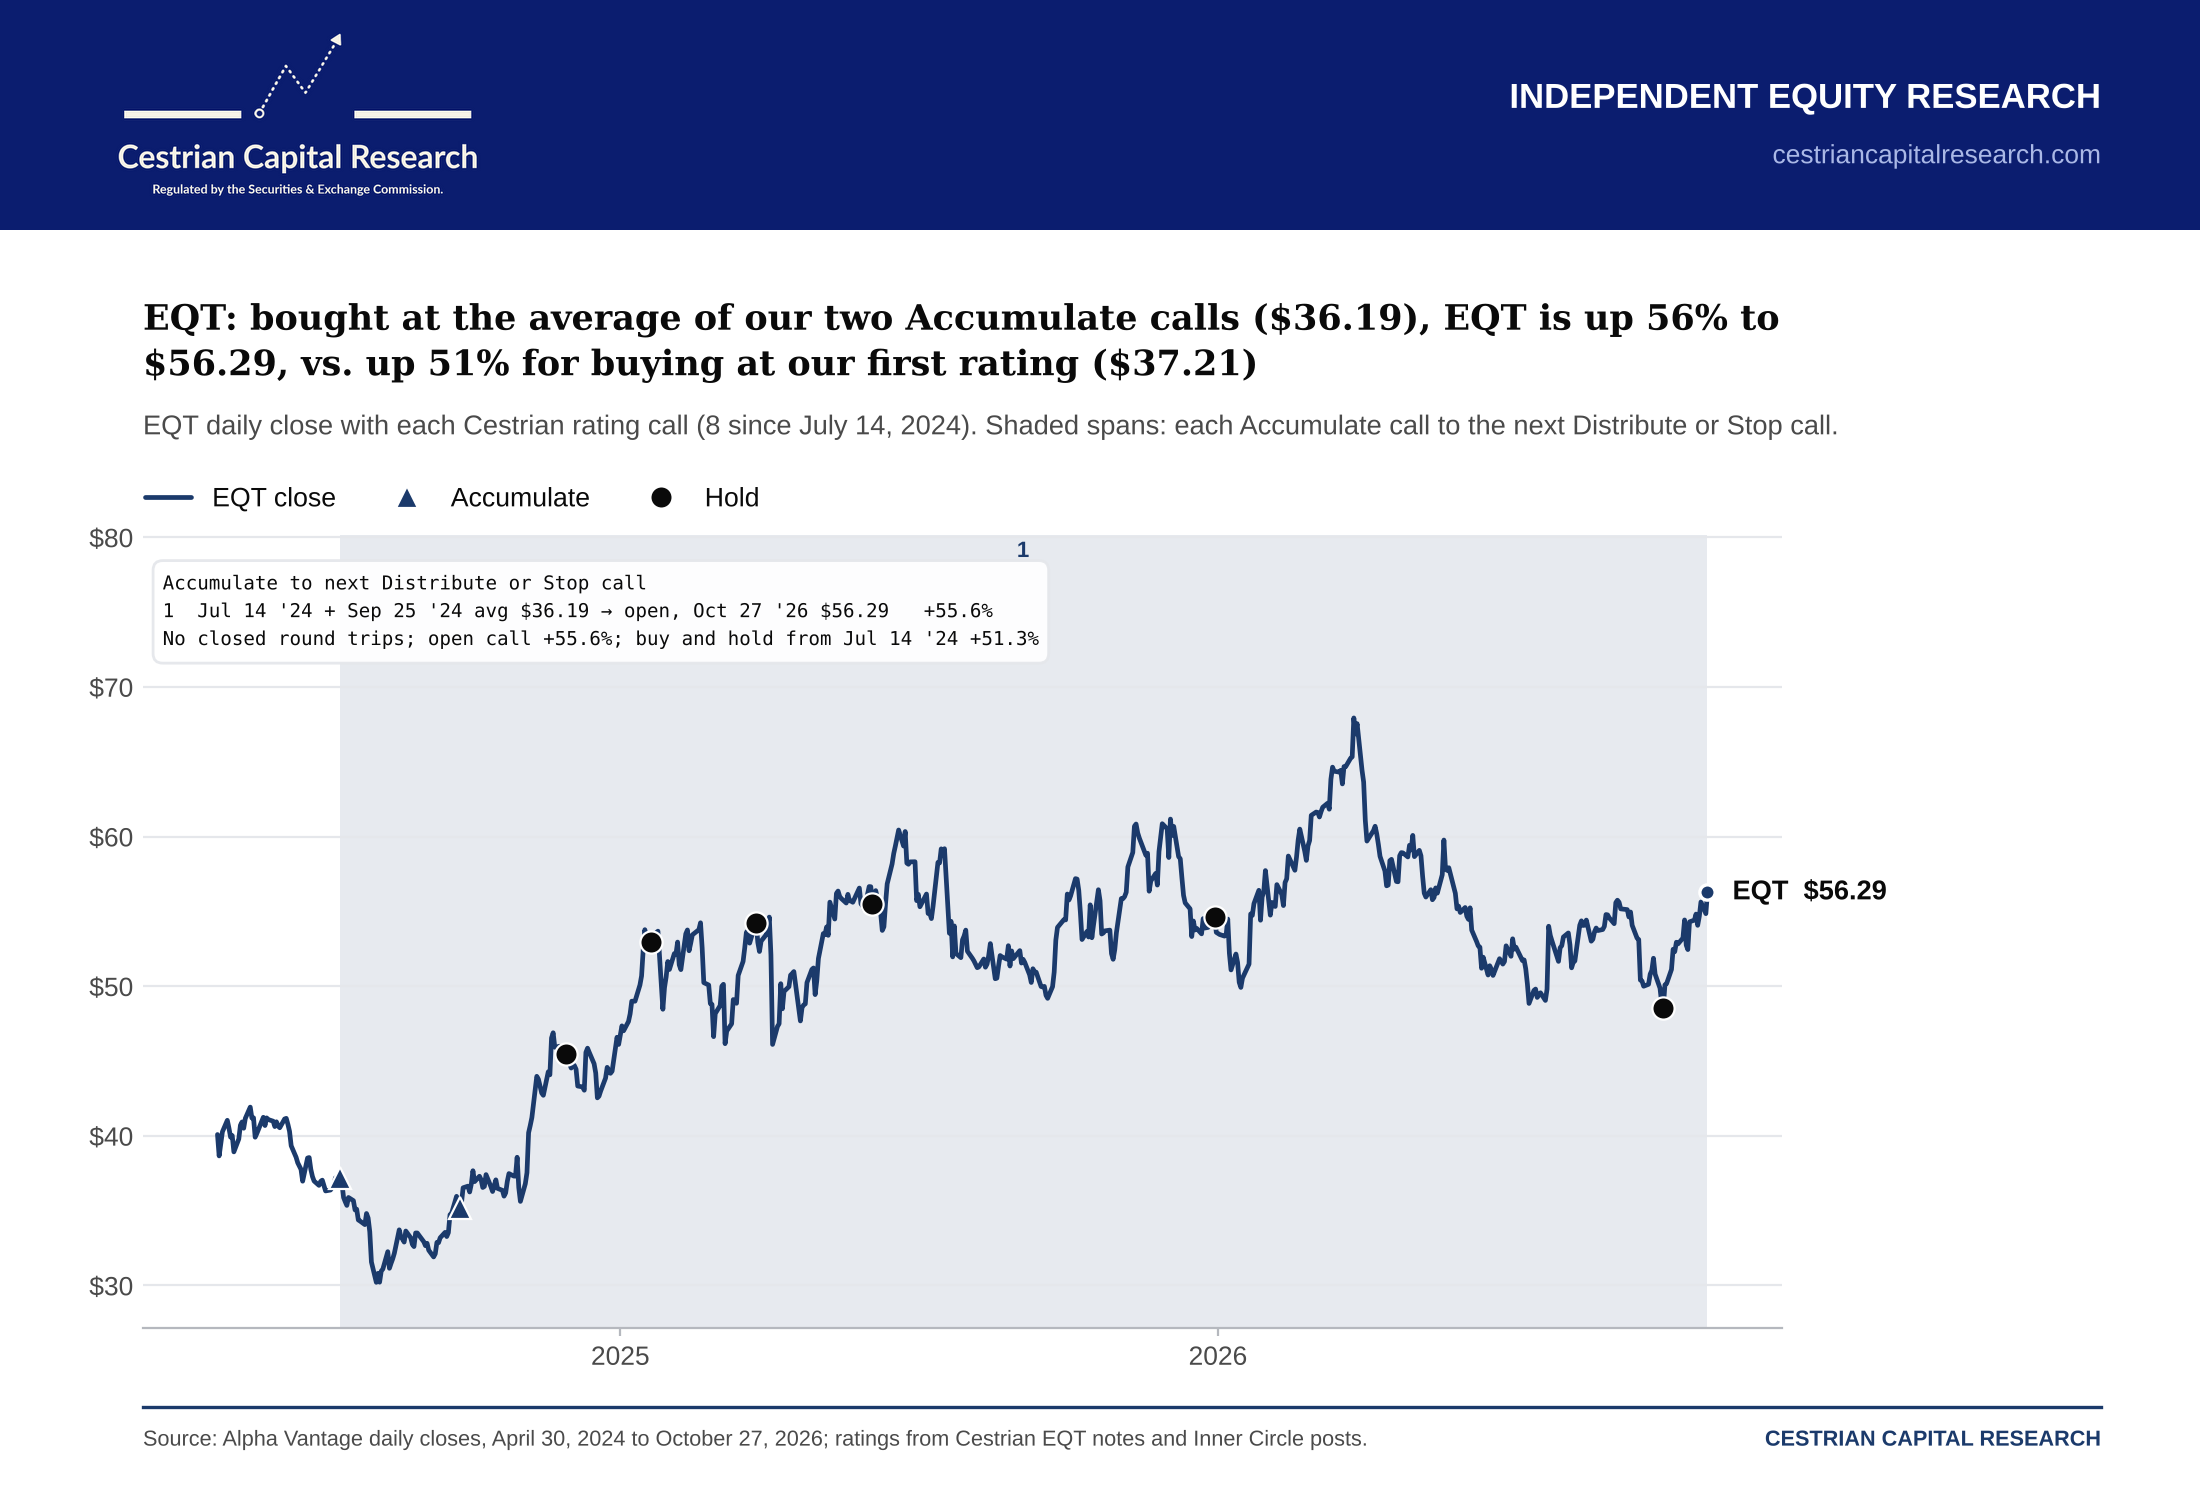
EQT moved to Distribute at $56.29 after Q3 revenue fell 9.6%; a 44% trailing free-cash-flow margin signals cycle risk despite lower debt…
@nisanyanviskisi $EOSE was added to this meme port just by looking at the chart...
The 10x case for $UUUU mostly rides on Phase 2, which the feasibility study has at ~$311M of avg annual EBITDA but still has no final investment decision. Nearer term I'd watch the mine. Only 740K lbs were mined in H1 vs a 2.0-2.5M guide, and Pinyon Plain grade fell to 0.71% in Q2 from ~1.62% in 2025.
Here's the ~6,600-word deep dive on $TOYO that answers everything:
A solar manufacturer that grew revenue 141.5% in 2025 now trades at 2.0x TTM earnings, after falling 77.5% from its June peak. U.S. customs (CBP) has been detaining its Ethiopian cells since May, and Commerce is deciding whether they should pay the duties on Chinese cells, with a first ruling due around December 14. That company is TOYO Co., Ltd $TOYO, now at $3.83/share. $TOYO’s closest comps are four other listed solar manufacturers selling into the U.S., and all four are down from their 2026 highs too, as of the October 26 close: → First Solar $FSLR: Down 47.2% to $168.15/share. → Canadian Solar $CSIQ: Down 65.2% to $8.85/share. → JinkoSolar $JKS: Down 72.7% to $8.17/share. → T1 Energy $TE: Down 82.4% to $2.12/share. Only $TE has fallen further from its 2026 high. Besides CBP’s detentions and the Ethiopia inquiry, four more overhangs landed after the June peak: 1) Discounted stock sale: $TOYO sold $50M of stock and warrants at $11.00 on June 24, a 14.9% discount to the prior close, and the stock fell 38.8% that day to $7.91. 2) New tariff: An August 6 proclamation set a 15% U.S. tariff on imported solar cells and panels, including $TOYO’s cells from Ethiopia, starting December 4. 3) Guidance dropped: $TOYO didn’t reaffirm its 2026 targets with its H1 results on August 19, when the stock fell 24.2%, and on September 28 only said it expects positive EBITDA for H2 2026. 4) Parent delisted: The Tokyo Stock Exchange delisted Abalance, the Japanese group that controls $TOYO, on September 26. Still, $TOYO is profitable and has net cash: → Earnings: $156.4M of TTM EBITDA and $80.5M of TTM net income. → Cash flow: $61.4M from operations in H1 2026, less $27.8M of capex, for $33.7M of FCF. → Balance sheet: Went from a going-concern warning to positive working capital in six months, with $26.4M of net cash as of June 30. → Texas: Doubled its Texas module capacity to 2 GW and signed ~$240M of binding module contracts since mid-June. → Tax credits: Management expects $140M/year of U.S. manufacturing tax credits at full Texas output, 85.6% of $TOYO’s market cap, and leaves those credits out of its forecasts. $TOYO’s EV of $137.2M is just 0.9x its TTM EBITDA. So is $TOYO a profitable non-Chinese cell maker on sale, or is the market right that Ethiopia’s U.S. sales won’t last?
@Bleesed2win Thanks $FLNC added to the “It’s All Over” portfolio, tracking it at ~$5.8. FYI this is not a recommendation of any of these stocks (or their fundamentals)
For the full Excel model and whether I’m adding to $BRUN at/below $8.89/share:
Monte Investments updates Carpenter Technology after a 25% sell-off, tracks EQT’s $12.83 billion Range Resources acquisition and assesses…
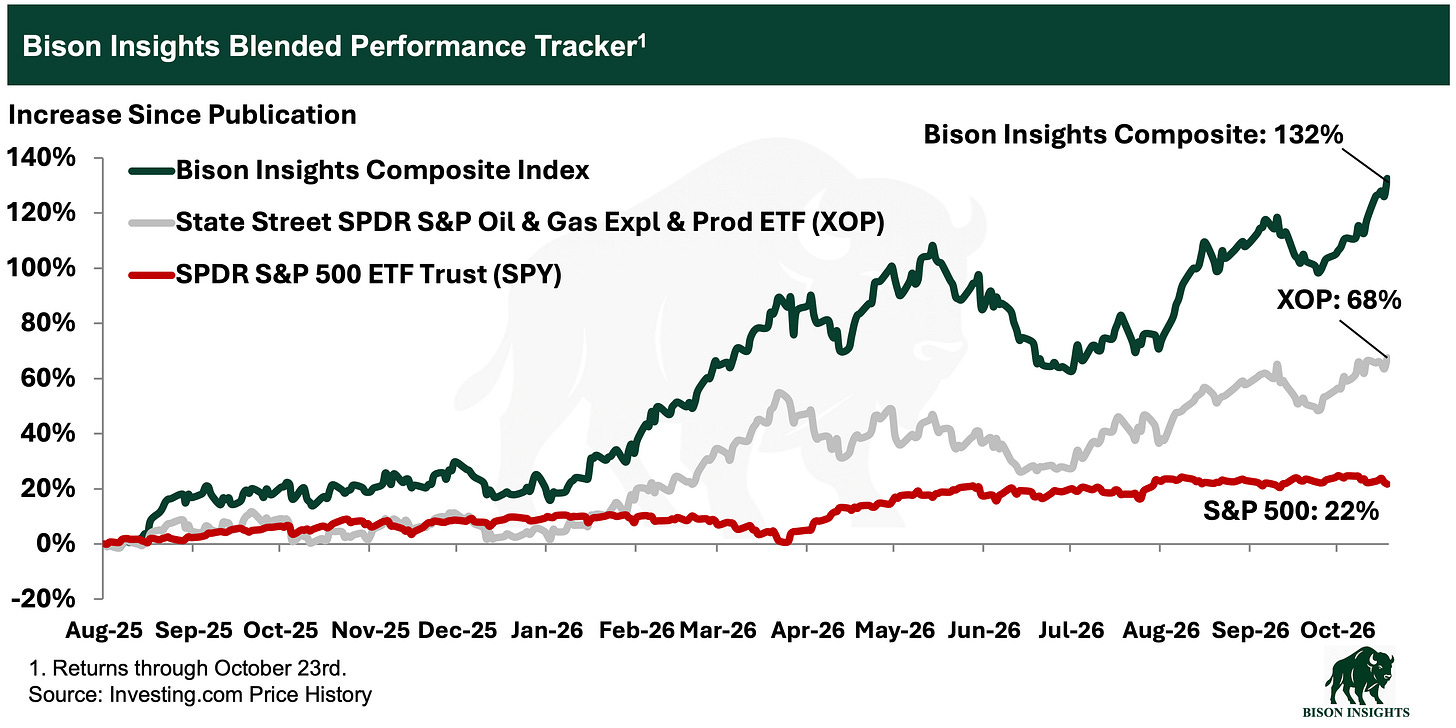
EQT’s $50 billion merger with Range Resources and Ovintiv’s $1.26 billion acquisition of Logan Energy reshape North American oil and gas…
New number one nat gas producer EQT to buy Range Resources in natural gas megadeal $EQT
JetBlue Shares in Tailspin as High Fuel Prices Threaten Turnaround $JBLU
added to $BE and $AMZN

Oil spiking higher or lower from here and hence how gold and smid cyclicals do from here is now increasingly dependent on Israel election. Bibi loss likely results in Trump folding to Iran in some fashion which should push oil premium significantly down. The ultimate 🌮 could be served. Bibi wins should push oil higher. Doubt even Trump knows what happens. Don't yolo yet. $gld, $iwm
Bimergen Energy filed for a Texas retail-power license to supply data centers directly and gained eligibility for federal contracts through…
Peabody expects rising thermal coal demand, LNG shortfalls and AI power needs to offset higher costs and Centurion ramp-up losses, while…
 Zoltan Ban 6 clicks

@Daniel___Gordon $BWEN hasn’t proven they can execute on the bottom line yet. Maybe they’ll grow revenue, but they need to show they can actually make money doing it. They didn’t do it with the previous business - for the last 10 years or so. Let’s see if they can do it with the new focus.

$RNGR: $14.71, ~$345M mkt cap, ~$395M EV after the STEP deal. Q2 adj EBITDA $28.6M, so ~3.5x run-rate EBITDA. Ranger runs well-service rigs, wireline and coiled tubing in the Permian and Bakken: the crews that keep old oil wells producing. Unsexy, but maintenance work holds up better than drilling. Capital allocation is the pitch. They've bought back ~4.6M shares since 2023 at ~$11 avg, pay a dividend, and just bought STEP's US coiled tubing assets for $27.5M, ~2.5x expected 2027 EBITDA. Chevron gave them 3 more hybrid ECHO rigs in July. Mgmt is targeting $100M+ of EBITDA against a ~$395M EV. Risk: H1 FCF was negative because customers paid slow (receivables went from $78M to $124M). When that cash comes home, FCF jumps.
SLB’s Q3 beats, sequential margin gains and roughly $10 billion Q4 revenue guide support an earnings recovery despite flat Middle East…
 Steven Fiorillo 3 clicks
Petrobras’s Morpho-1 well revived hopes that Brazil’s Equatorial Margin can become a major new oil frontier after hydrocarbons were…
Here’s where BWX Technologies’ $BWXT stock could be by the end of 2027, 15 months from now, in my bear, base, and bull cases. I value each case on 2028 adjusted EBITDA, since the market will be pricing 2028 numbers by then. For net debt, I use today’s $1.65B minus the $750M from its medical isotope sale, or $0.9B. To stay conservative, I don’t credit the FCF $BWXT earns between now and the end of 2027. Management plans to spend the cash, including on acquisitions, but hasn’t said how much or on what, so I leave out both the cash and any EBITDA acquisitions could potentially add. Therefore, each case’s value is 2028 adjusted EBITDA times the multiple, minus the $0.9B of net debt, over 92.0M diluted shares (its convertible notes only dilute above $262.51). Bear case ($118, -19%) The bear case assumes budgets slip (the government is running on a continuing resolution through December 11), the terms of its Janus contract (the Army’s microreactor program for military bases) disappoint, and new-build orders arrive later than John MacQuarrie, president of Commercial Operations, expects. That implies only 5%/year adjusted EBITDA growth to $735M in 2028, and a multiple of 16x, slightly below $BWXT’s 16.6x at the end of 2023, for a value of $118/share. Base case ($162, +11%, most likely) The base case assumes $BWXT delivers its 2027 framework (high-single-digit growth to $720M of adjusted EBITDA) and grows 10% in 2028 to $790M as new-build revenue starts. That implies the multiple holds at 20x, near today’s, for a value of $162/share. $BWXT’s own 2030 plan goes further. Today’s $15.0B EV is 13.0x the $1.15B midpoint of its 2030 adjusted EBITDA target. If $BWXT hits that midpoint, trades at 18x instead of the base case’s 20x, and runs at 2.5x net leverage (~$2.9B of net debt) after deploying its capital, the stock would be worth $194/share at the end of 2029. With ~$4/share of total dividends through 2029, that’s a 9.9%/year return from $145.70. But getting from the base case’s $790M in 2028 to $1.15B in 2030 takes ~21%/year growth, more than double the 2028 pace, so the new orders and acquisitions outside $BWXT’s predictable core (the programs backed by backlog and long-term contracts) have to show up. Bull case ($204, +40%) The bull case assumes a new-build order lands by early 2027, $BWXT signs a Janus contract on par with microreactor startup Radiant’s (up to $750M), and margins rise toward 20%. That implies adjusted EBITDA of $820M in 2028 and a re-rating to 24x, just under the 24.8x of Curtiss-Wright $CW today, for a value of $204/share. Notably, none of the three cases considers a commercial BANR (microreactor) sale, a Wyoming TRISO fuel plant, a battleship reactor, or a data center customer, so at $145.70/share, you’re getting commercial microreactors and data centers as a free option.
small at first... the initial trades are feelers. The real opportunity comes if the initial trades get run over. If that happens I take the L, but reinitiate at much higher strikes, in larger size (and even at the same size and further otm the option premium the trade takes in is much higher due to higher IV). At peak they may be 10+% of my portfolio as measured by either margin or risk. Once (when NG was sub-1.80 and people were talking about sub-1) it was ~35%. For $KOLD, timing impacts size too. I hesitate to get large going into the winter, but give me a March with commentators talking about running out of storage capacity over the summer and its game on.
I will likely be a seller of $KOLD calls soon (long-dated, otm)
Franco-Nevada, Wheaton and Texas Pacific Land built royalty and streaming businesses by buying fixed shares of mines and wells, tracing the…
Western Digital and Bloom Energy fell after strong quarterly results, extending the selloff in AI-linked stocks.

HFI Portfolio bought 94,214 shares of Transocean, RIG, for $570,000 at $6.05 per share.
@credealjunkie Weird days in my portfolio Calls in $USO up Puts in $IWM and $SPY up Event driven name up REITs up Puts in Coreweave up + 4.3% vs Nasdaq today Some pod long/short factor favoring my positioning I'm not smart like this, I'm not sure if I'm smart at all
$NTWO 👀

$KSS Kohl's is up 50% in a month as oil reclaims highest levels since May.....hard to imagine how this happens. Up another 8% today as the market pukes ai today, which perversely will put more pressure on spending if markets stay pressured so what is the "next level thinking" purchase of Kohls today
@Jefffeldman I own calls in $USO As a human, I would hate to make a windfall from it if oil goes to $150-200/bbl But it's my job to protect my investors
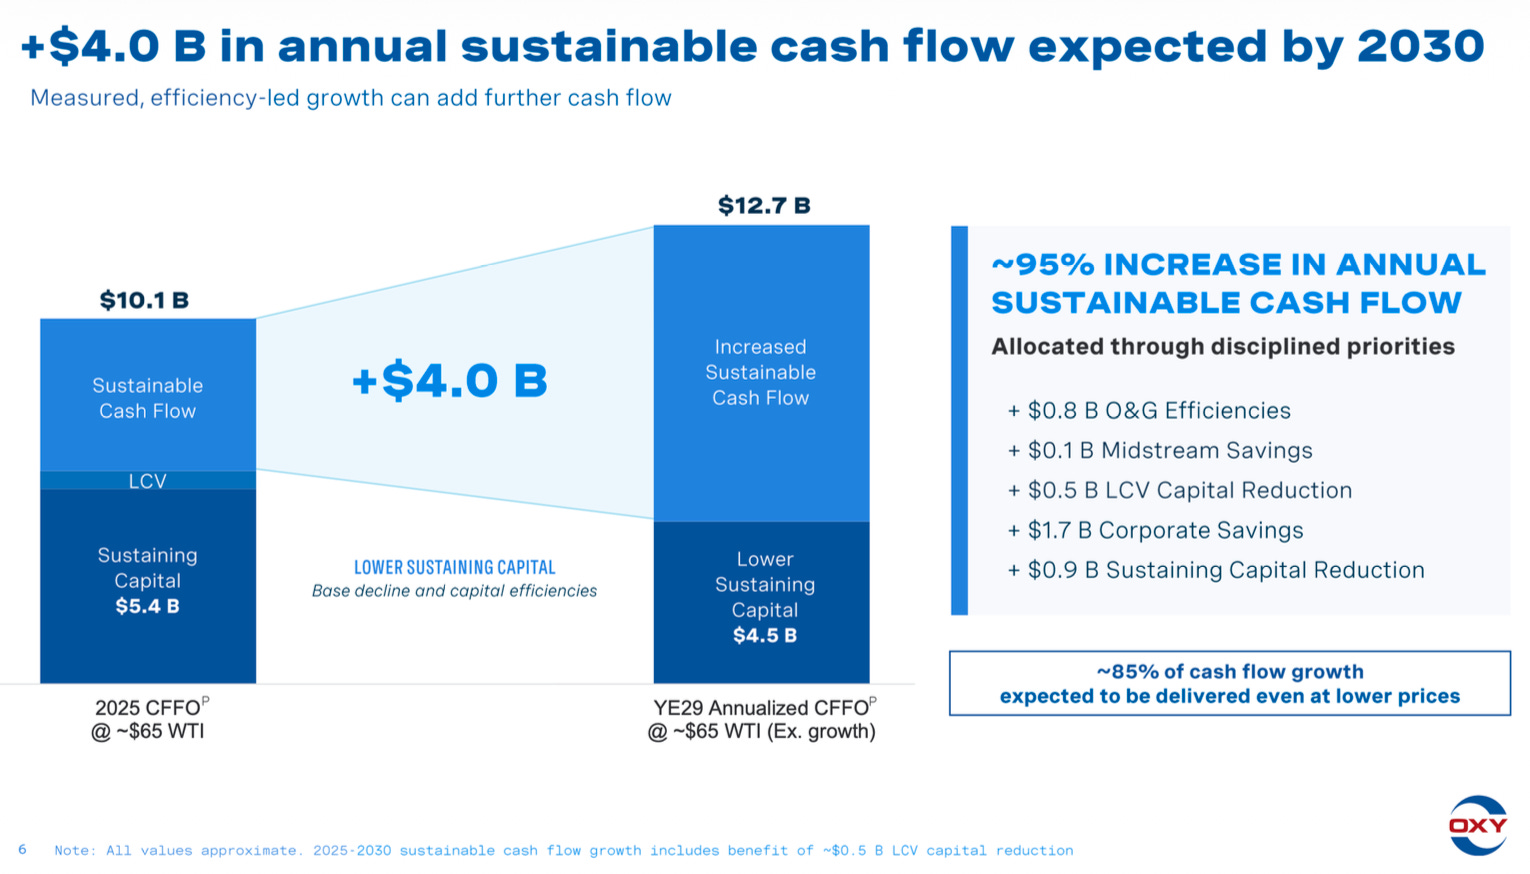
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
Hess Midstream, Iovance Biotherapeutics, Netlist and nine other lesser-covered stocks make this week’s Undercovered Dozen.
 The Undercovered Dozen 16 clicks
Dorchester Minerals’ next two distributions are projected at $0.95 to $1.00 per unit, supported by its Williston Basin acquisition and oil…
 Elephant Analytics 3 clicks
Devon Energy’s $4.2 billion Eagle Ford sale concentrates its portfolio in the Permian, lifting capital efficiency and margins despite lower…
 Elliott Gue
Our least-favoured bet on next-generation nuclear: light-water SMRs. Smaller does not automatically mean cheaper. A 50–300 MW small modular reactor produces far less power than a 1 GW plant, but containment, site infrastructure and other costs may not shrink proportionately. Factory production and simpler safety systems can help, but those savings must outweigh the loss of scale. The result could be a higher cost per installed kilowatt, not a lower one. Advanced alternatives offer higher temperatures and more industrial uses. But we think many face a bigger obstacle than licensing: securing enough fuel. To understand the investment trade-offs, separate two questions: what cools the reactor, and what fuels it? Light water → Proven technology, established fuel supply. Uses ordinary water and fuel typically enriched below 5% uranium-235. Runs at around 300°C under pressure, producing electricity and lower-temperature heat. Its advantage is maturity; its limitation is that it cannot directly supply the hottest industrial processes. Shrinking it does not necessarily improve its economics. Sodium → Higher temperatures without high pressure. Transfers heat efficiently and operates near atmospheric pressure, reducing the need for heavy pressure-containing equipment. The catch: sodium burns in air and reacts violently with water, requiring strict separation and additional safeguards. Helium → High-temperature heat without a chemically reactive coolant. Can reach roughly 750°C or more, supporting more efficient electricity generation and industrial heat. Helium does not burn or react chemically, but the system operates under pressure and must stay leak-tight. Leading designs also require specialised TRISO fuel. Fluoride salts → High-temperature heat at low pressure, without sodium’s fire risk. The challenges are corrosion, suitable materials and preventing the salt from freezing. Some designs, such as Kairos Power’s, use salt to cool solid TRISO fuel. Others dissolve the fuel in the salt itself. These are different designs with different fuel requirements. Then come two separate fuel bottlenecks: HALEU is about uranium enrichment. It contains more than 5% but less than 20% uranium-235. Many leading sodium-, helium- and fluoride-salt-cooled designs need it, although not every advanced reactor does. Western production remains limited. Centrus Energy ($LEU) has produced small quantities with demonstration equipment and targets new enrichment capacity in 2029. We do not expect sufficient supply for broad deployment before the late 2020s at the earliest. TRISO is about fuel manufacturing — not a type of coolant. Tiny uranium-bearing particles are wrapped in carbon and ceramic layers designed to retain radioactive fission products even at roughly 1,600°C. That is a major safety advantage, but manufacturing and quality control are demanding. US production already exists, but capacity needs to expand substantially. X-energy’s ( $XE) larger TX-1 facility is still under construction. Helium-cooled and some salt-cooled designs therefore face both bottlenecks: getting HALEU, then turning it into finished TRISO fuel. For investors, a reactor licence is not a fuel supply chain. And a smaller reactor is not automatically a better investment.
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
Atlas Diary 3 clicks
NGL Energy Partners' capex more than quadrupled year over year as ABL borrowings and long-term debt rose, worsening its cash-generation…
 Long Player
$BORR Troim keeps buying. I'm long.
Energy Fuels $UUUU, the largest U.S. uranium producer, fell 10% to $8.34 on October 14, a new 52-week low, the day after it filed to sell another $500M of stock through its at-the-market offering (ATM). Energy Fuels had already sold ~$300M of stock through the program, and at $8.34, another $500M would be ~60M more shares, or ~22.6% of the 264.8M outstanding. On October 13, Energy Fuels also amended its deal for VAC, the German magnet maker it agreed to buy in June, over a dispute at VAC's U.S. plant. VAC's Sumter, South Carolina plant "was constructed in connection with an offtake agreement," and that customer sent a termination notice on July 1, eight days after Energy Fuels signed the deal. VAC started arbitration on July 7, arguing the termination was wrongful and seeking the payments left on the contract. Energy Fuels says it knew about the dispute during negotiations and built in a purchase price adjustment. VAC itself lost €87.9M (~$99M) in 2025 and €57.4M (~$67M) in H1 2026, even as H1 revenue rose 34.8%. In June, my bear case was $8-10/share: The ATM keeps diluting and the rare earth premium drains out. At $8.34, the stock already sits in that range, while Energy Fuels still plans to pay $718M of cash, 65.9M shares, and up to $135M of preferred stock for a magnet maker in arbitration with the customer its U.S. plant was built for.
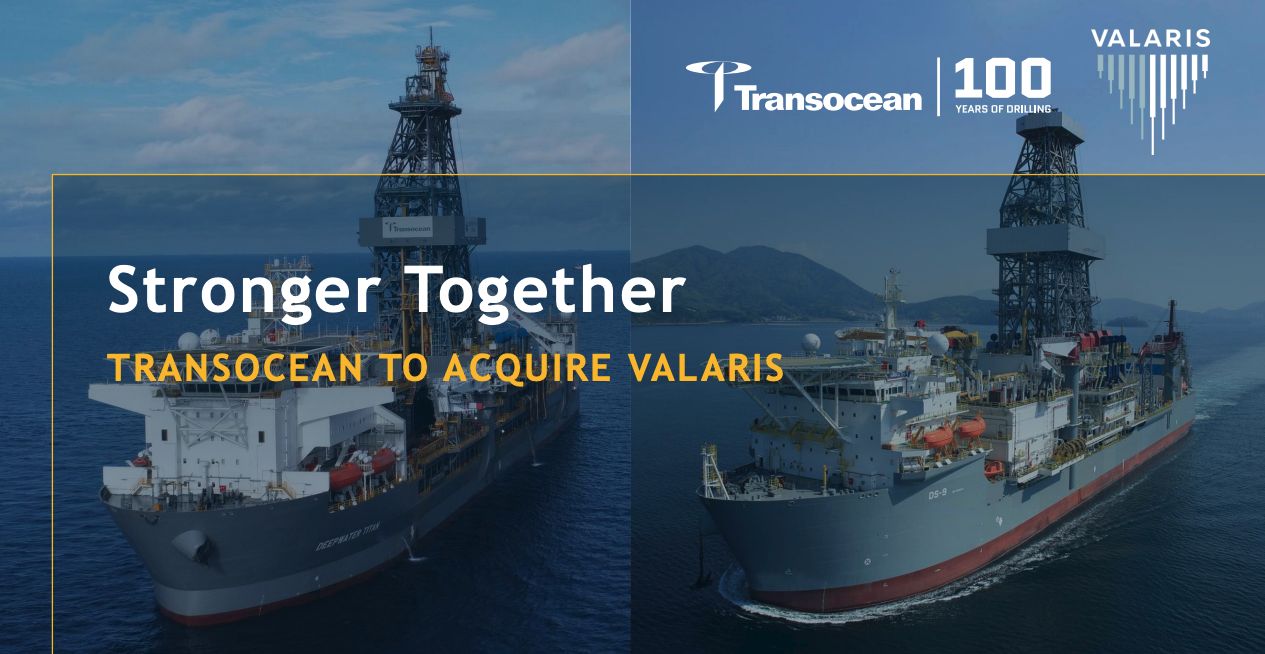
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.

Been tough this year when you refuse to mindlessly speculate on the AI Mania… Those trade schools ($LINC and $UTI) have really hurt. However, I have added real size the whole way down, and they’re now one of our largest exposures. This was offset by solid performance in refiners ($MPC and $VLO) which I have now harvested. The rest of the book was mostly a wash…
Peabody Energy’s recovery case hinges on Centurion, coal-market leverage, capital allocation and balance-sheet strength amid commodity…
 CAN Analyst 1 click
BP to set out new strategy after windfall year $BP
The CEO was also buying shares last month but we prefer buying by directors and that is why Tor Olav Troim's purchases were more interesting. From our Insider Weekends article about $BORR:
Another large insider purchase by a director of Borr Drilling $BORR filed today (yesterday was a holiday for the SEC and so no Form 4 filings). This is his largest single day insider purchase coming in at $11.84 million. We had been watching him buy consistently for several weeks and decided to dive into the company in an Insider Weekends article last Sunday. As we did our research, we realized that he was the founder of the company. A couple of screenshots from that article in the next tweet.
Definitely some insider trading yesterday prior to the news today as ethanol prices rocketed higher (Nov jumped nearly 6 cents). October crush margin for the 2nd half jumped to $0.42 yesterday... we'll see if ethanol rallies again now that the news is actually public. $ALTO $GPRE
Huge news for $ALTO and $GPRE
SED Energy's proposed Ventura merger projects a 22% to 40% dividend yield, but idle tender barges, debt and repayments materially reduce…
See the 10-Q’s explanation of the cash flow increase here: Continue reading here for how $BWXT’s $1.25B convertible note affects dilution:
How much of the $8.4B backlog at BWX Technologies $BWXT turns into revenue by the end of 2027? $BWXT expects to recognize 55% of the $8.4B backlog, or ~$4.6B, by the end of 2027. Another $1.4B of unexercised contract options sit outside the backlog, with $900M expected to be awarded in 2030 and $500M in 2035. Three items drive $BWXT’s quarterly FCF swings: 1) Payables: Higher accounts payable added $71.4M to H1 2026’s $249.0M of operating cash flow, vs. $6.9M a year earlier. The 10-Q credits the cash flow increase mainly to the timing of vendor payments, customer billings, and project cash flows, which can reverse in later quarters. 2) Seasonality: Retainages (payments withheld on the government segment’s fixed-price incentive contracts until set conditions are met) build in Q1 and Q3, with larger payments in Q2 and Q4. 3) Equity income: $BWXT’s share of the profit from the joint ventures that manage 14 government nuclear sites, including Savannah River and Pantex, comes in as equity income, now $80M/year. It counts toward adjusted EBITDA (15.7% of Q2’s $155.5M), but $BWXT only gets the cash when the joint ventures pay dividends. That’s why I’d judge $BWXT’s FCF on the full year, not the quarter.
In November 2025, BWX Technologies $BWXT sold $1.25B of 0% convertible notes due November 2030 and used $830.8M of the proceeds to repay its old credit facility. The conversion price is $262.51/share, 80.2% above $145.70, and $131.9M of capped calls offset dilution up to $396.24/share. Dilution has been minimal so far. Diluted shares have held at ~92M since 2023, helped by small buybacks ($30M in 2025). But stock comp rose to $20.1M in H1 2026 from $13.7M a year earlier, although it’s still only 1.1% of revenue, up from 0.9%. Management also said on the Q2 call it doesn’t plan buybacks in 2026, despite $347.6M left on the authorization, so nothing will offset the new shares. Even after paying ~$200M for Precision Components Group (PCG) on July 1, $BWXT’s leverage is within its 2-3x target: → Debt: $2.05B ($400M of 4.125% notes due June 2028, $400M of 4.125% notes due April 2029, and the $1.25B convert). → Cash and liquidity: $400M of cash and $1.7B of total liquidity, including an undrawn $1.25B revolver running to November 2030. → Leverage: 2.7x net debt to TTM adjusted EBITDA, or $1.65B of net debt on $602.1M of EBITDA. The $750M from selling its medical isotope business would cut leverage to 1.5x. → Ratings: Fitch BBB (investment grade) since September 2026; S&P BB+ and Moody’s Ba1, one notch below. → Other obligations: $152.0M of underfunded pension and retiree benefit plans. Net debt has hovered between $1.0B and $1.5B since 2023. $BWXT pays a dividend of $0.27/quarter ($1.08/year, a 0.7% yield), raised from $0.25 in February 2026. The company expects $5.5B of capital to deploy through 2030 at 2-3x leverage, with $3.5B left after capex and dividends. That’s what CFO Mike Fitzgerald said at $BWXT’s Investor Day on September 29, 2026, and he also put organic growth first for the $3.5B. But he said $BWXT is “not anchored to the same size of transactions” it has done before, and the deck lists “Disciplined Acquisitions” among the revenue drivers behind the 2030 targets. In other words, $BWXT has the track record and, once the medical sale closes, the balance sheet to go after its 2030 targets.
$FSLR
Continue reading here for the U.S. AP1000 push and the new plant $BWXT is weighing:
Excluding medical isotopes, commercial power revenue at BWX Technologies $BWXT nearly tripled, from ~$400M in 2023 to ~$1.1B expected in 2026. $BWXT’s commercial segment is growing much faster than its government segment, driven by (1) Ontario rebuilding its reactors, (2) Canada’s plan for new ones, and (3) the U.S. push for new AP1000 reactors. Its commercial backlog more than doubled to $1.6B. Kinectrics, a Toronto-based nuclear engineering and testing firm acquired in May 2025, explains part of the jump. Commercial revenue grew 72% in Q2 2026, or 33% excluding the acquisition. In Ontario, utilities are rebuilding reactors to run for decades longer. $BWXT is building 48 steam generators for Ontario Power Generation’s (OPG) Pickering refurbishment, part of more than CAD$1B (~$700M) of contracts. The same contracts cover the reactor pressure vessel for the first BWRX-300 at OPG’s Darlington station, a 300 MWe small modular reactor (SMR) designed by GE Vernova Hitachi. The 10-K calls $BWXT “the only commercial heavy nuclear component manufacturer in North America.” Notably, its Cambridge, Ontario plant is turning out more than 1.5 steam generators/month vs. the 1/month its schedule requires, per $BWXT’s Investor Day on September 29, 2026. Beyond refurbishments, Canada’s June 2026 nuclear strategy calls for “up to ten new large-scale reactors,” with two under construction by 2035 and five more planned or under development by 2040. $BWXT already has licensing and early engineering contracts for the large reactors planned by OPG and Bruce Power, the private operator of Ontario’s Bruce nuclear station. John MacQuarrie, president of Commercial Operations, estimated Canada’s new-build market at CAD$120-150B (~$84-105B) at Investor Day. Slide 31 shows $BWXT’s potential revenue per new reactor: → CANDU (Canada’s heavy-water reactor design): $350-700M per reactor. → AP1000 (Westinghouse’s large U.S. design): Low hundreds of millions of dollars. → SMRs: $50-100M.
The Department of Energy conditionally committed $17.5B in loans in June 2026 for long-lead equipment for up to 10 AP1000 reactors (Westinghouse’s large U.S. design), and only “a limited number of heavy engineering plants” can make the components, per World Nuclear News. BWX Technologies $BWXT bought Precision Components Group (PCG) in July 2026 to get a U.S. foothold. PCG makes heat exchangers and other heavy components at plants in York, Pennsylvania, and Florence, New Jersey, but it can’t make the largest parts, like an AP1000 reactor pressure vessel, CEO Rex Geveden said on the Q2 call. So $BWXT is weighing New Jersey, Indiana, and one other location for a new U.S. large-component plant, and Geveden expects “a final investment decision in the coming months.” He also expected at least one new-build equipment order by the end of 2026, from the three additional small modular reactors (SMRs) planned at Darlington in Ontario, the AP1000 projects, or BWRX-300 SMR projects in the U.S. John MacQuarrie, president of Commercial Operations, widened that window at $BWXT’s Investor Day on September 29, 2026, saying awards should start “either later this year or early in 2027.” $BWXT’s Investor Day targets call for high-teens annual revenue growth in the commercial segment through 2030, with adjusted EBITDA margins rising to the high teens from 13% in 2026. Reading “high teens” as 16-19%, commercial revenue would grow from ~$1.1B in 2026 to ~$2.0-2.2B by 2030, and adjusted EBITDA from ~$140M to ~$320-420M. That would make commercial about a third of $BWXT’s adjusted EBITDA, up from about a fifth.
Neither of the two commercial prospects BWX Technologies $BWXT has named for its BANR microreactor is a data center. 1) Prodigy Clean Energy, a Montreal-based developer of factory-built nuclear plants: Two BANRs for a transportable pilot plant in Belledune, New Brunswick, built mainly at $BWXT’s Ontario plants and running in the early 2030s. New Brunswick’s government signed a letter of intent (LOI) to buy the power. $BWXT and Prodigy are still negotiating a definitive agreement, and the release provides no dollar value. 2) Tata Chemicals Soda Ash: A Wyoming soda ash producer that signed an LOI to explore deploying up to eight BANRs. $BWXT also markets BANR to data centers. However, I found no data center contract, customer, LOI, or revenue in any $BWXT press release from January 2025 through October 2026, in the FY2025 10-K, or in the 2026 10-Qs. $BWXT’s own mentions stop at a product page saying BANR can provide “clean electricity for municipalities, data centers and campuses,” and slides 11 and 25 from its Investor Day on September 29, 2026, which list “AI/data center demand” as a driver of nuclear demand in general. I didn’t hear the phrase “data center” mentioned once during Investor Day, and slide 49 lists data centers in the third phase of $BWXT’s microreactor plan. CEO Rex Geveden said at Investor Day that “the incremental demand from AI right now is 60 GW” and “winning at AI means winning at power, and winning at power probably means having a nuclear solution.” If he’s right, $BWXT benefits by supplying components, fuel, and services to more reactors, not by selling microreactors to data centers. Advanced Reactor Design and Engineering, the product line that includes Project Pele (its prototype microreactor for the Pentagon) and $BWXT’s other microreactor programs, brought in $203.8M in 2024 and $147.1M in 2025, then $52.6M in H1 2026, down from $69.8M a year earlier. At 3.0% of $BWXT’s $1,761.8M of H1 2026 revenue, microreactors are still a small, early business.
$CHRD: 6.5x FCF, Good CEO, buying back lots of stock, low-cost pure play EP. 8% FCF yield at $60 WTI. No meaningful leverage CHRD trades at ~$142, market cap ~$7.74B, enterprise value ~$8.63B. Dividend yield ~3.7% ($5.20 annual base). Buyback/total shareholder yield is higher: policy returns ≥75% of adjusted free cash flow (mostly buybacks after the base dividend) at current low leverage (<0.5x). On 2026 guidance of ~$1.3B Adj. FCF, this implies a potential total cash return yield in the low-to-mid teens. Valuation is low: ~9.5x TTM P/E, ~7.6x forward P/E, EV/EBITDA ~3.2-3.6x, P/FCF ~6.5x. Analyst consensus PT ~$166-174 (~20%+ upside); highs to $193. Marcellus non-op sale (to POSCO, expected Q4 2026 close) provides ~$550M gross proceeds, sharpening pure-play Williston focus, boosting cash/flexibility for returns or balance-sheet strength, and removing a non-core asset. Reasons for future growth: Flat-to-low absolute oil volumes (maintenance program ~161 MBopd oil) but rising per-share metrics via efficiency and buybacks. Longer laterals (majority of program, including 4-mile) cut costs/breakevens and improve recovery; base production enhancements and lower declines support volumes with less capital. Pure-play focus post-sale plus disciplined consolidator role in the Bakken. Efficiency gains already drove material FCF improvements. LTM Owner’s Earnings (Buffett-style): Roughly Net Income + DD&A + other non-cash charges − maintenance CapEx (and normalized for WC/one-time items). For this E&P, nearly all CapEx is maintenance to offset natural declines, so Owner’s Earnings approximates free cash flow. TTM (to ~Jun 30, 2026): Operating cash flow ~$2.59B, CapEx ~$1.40B → FCF ~$1.19B. DD&A ~$1.54B; Net Income ~$841M. Company-reported adjusted FCF (preferred operational proxy) was strong in 1H26 (~$738M combined Q1+Q2) and has been running at an elevated rate. This is a rigorous, cash-based measure after the capital required to sustain the business. Expected next-12-months Owner’s Earnings: ~$1.3B adjusted free cash flow (company 2026 guidance, including derivatives, at $75 WTI / $3 HH for 2H). Why higher than LTM: stronger realized oil prices vs. prior periods, operational efficiencies (longer laterals, cost controls, base enhancements), volumes at/above high-end of prior guidance, and capital discipline (CapEx held ~$1.4B midpoint). The $550M Marcellus proceeds is one-time cash (not recurring earnings) that further supports returns and balance-sheet optionality. At ≥75% payout, this supports substantial shareholder distributions while maintaining a strong BS. Business simply: Pure-play Williston Basin (Bakken) E&P—largest operator there. Drills oil-focused horizontal wells, produces/sells crude, NGLs, and gas. High-quality inventory; shift to longer laterals improves economics. Management: Danny Brown (CEO; prior Oasis/Anadarko). Track record of efficiency, synergies, disciplined capital allocation, and per-share value creation. Capital allocation: Base dividend + aggressive buybacks under the 75%+ Adj. FCF framework (leverage-dependent). Share count reduced meaningfully; cumulative returns large relative to market cap. Maintenance production focus. Risks: Oil price sensitivity/volatility (primary driver), basin decline/inventory longevity, execution on laterals or M&A, regulatory factors in ND/MT, energy transition headwinds. Margin of safety & upside: Low leverage, high cash generation even at moderate oil prices ($60-70 WTI still supports solid FCF/returns), conservative CapEx, and efficiency gains provide protection. Upside from multiple expansion toward peers/history, continued buyback accretion to per-share metrics, operational outperformance, oil strength, and pure-play clarity. Consensus implies ~20%+ near-term upside; higher in stronger commodity scenarios. Attractive FCF yield + value profile in E&P. Figures based on company results/guidance, market data, and analyst notes as of early October 2026. Oil prices and execution remain key variables.
$FF: $195m EV, 30-40m current EBITDA est at RIN prices. 30m in hidden Arkansas land value (1.7k A out of 2.2k not being used) Thesis: Future Fuel's economics are primarily a bet on biodiesel margins. FF owns a relatively high-cost 59-million-gallon-per-year biodiesel plant, so it generally needs stronger industry margins than larger competitors to justify running at high utilization. The reason a high-cost producer like FF can still matter is the Renewable Fuel Standard (RFS): refiners must satisfy EPA-mandated renewable-fuel volumes, either by blending fuel or acquiring RIN credits. When mandated demand approaches or exceeds economical industry supply, the D4 RIN price rises until the marginal/high-cost producers have enough incentive to restart. FF is one of those marginal producers. That is the core thesis today. D4 RINs have risen sharply from roughly $0.50 in the depressed period to around $1.50, reflecting tighter expected supply/demand, while the EPA's much higher 2026–27 requirements should require substantially more biomass-based diesel production. If the industry remains short of required supply and the RIN bank is drawn down, RINs and therefore biodiesel margins should remain high enough to keep FF operating profitably; roughly speaking, every $0.10/gallon of sustainable margin on ~50 million gallons equals ~$5 million of annual operating profit. A return toward $0.30–$0.50/gallon margins could mean ~$15–25 million of biodiesel operating profit, versus very little or losses when margins collapse. The catalysts are higher plant utilization, continued tight D4 RIN supply/2027 RIN-bank depletion, and stronger chemicals earnings; the major risk is the opposite—RIN prices fall because supply increases, EPA policy weakens demand, exemptions expand, or renewable-diesel capacity overwhelms the market. In simple terms: FF is the expensive factory that the market may now need to run, and the RIN price is effectively what determines whether it gets paid enough to do so.
BWX Technologies $BWXT is in military base power three ways, through (1) Project Pele, a prototype reactor it’s building for the Pentagon, (2) the TRISO fuel its microreactors run on, and (3) Janus, the Army program that chose $BWXT’s commercial reactor for Fort Campbell, Kentucky. Pele is a 1.5-megawatt (MW) transportable, gas-cooled microreactor built for the Pentagon’s Strategic Capabilities Office under a 2022 award. $BWXT delivered its full TRISO fuel core to Idaho National Laboratory (INL) in December 2025, received the Department of Energy’s (DOE) preliminary safety approval in September 2026, and targets delivering the reactor to INL in 2027. TRISO (tri-structural isotropic) fuel, which the Department of Energy calls “the most robust nuclear fuel on earth,” packs uranium into particles coated in carbon and ceramic layers. $BWXT produces TRISO at Lynchburg “in the hundreds of kilograms quantities,” Joe Miller, president of Government Operations, said at its Investor Day on September 29, 2026. It also supplied the fuel for Antares, a microreactor startup whose reactor was the first new reactor to reach criticality (a self-sustaining chain reaction) under DOE’s reactor pilot program in June 2026. POWER magazine, a power-industry trade publication, reports $BWXT is “the only Janus vendor that self-supplies its TRISO fuel.” $BWXT is also negotiating a commercial TRISO plant in Wyoming with Kairos Power, an advanced reactor developer, at up to $500M of capex. CFO Mike Fitzgerald said at Investor Day that $BWXT needs to see high-assay low-enriched uranium (HALEU, the 5-20% enriched uranium most advanced reactors need) become available before committing to the plant, and “probably will not make a decision on that for a little while.” The Army chose BANR (the BWXT Advanced Nuclear Reactor), a 20 MWe (megawatts of electricity) gas-cooled design scaled up from Pele, for Fort Campbell. $BWXT plans to start construction at the site in late 2028 and have the reactor running in the early 2030s. Three details matter here: 1) No contract value: $BWXT’s release describes “a phased contracting approach.” For comparison, the Janus agreement for Radiant, a microreactor startup, is worth up to $750M. 2) $BWXT will own the reactor: The Army chose vendors “to own, construct and operate nuclear microreactors” ($BWXT’s release), under fixed-price, milestone-based agreements in which the Army pays at milestones rather than buying power. 3) Not first in line: With operation in the early 2030s, $BWXT’s reactor won’t meet the September 30, 2028 deadline a May 2025 executive order set for an Army-regulated reactor running on a U.S. military base. Radiant and Antares, two of the other Janus vendors, both target 2028 for their first reactors. After Radiant’s agreement, $1.45B of the program’s $2.2B is left, and an even split among the other four vendors would give $BWXT ~$360M over fiscal 2027-2031, or $72M/year, under 2% of 2026 revenue guidance.
Permian Resources uses discounted small-acreage acquisitions to supply up to 25% of drilling opportunities and build long-term growth.
Long Player  EPM · long
Evolution Petroleum (EPM) is presented as a long position.
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
The S&P 500 lost 18% in 2022, and the Bloomberg U.S. Aggregate, the main U.S. bond index, lost 13%, its worst year since it began in 1976. Over the same year, $XLE, the S&P 500 energy sector ETF, returned 64%, gold was flat, and cash earned ~1.5%. Now what if I told you there's a framework that would've said to own cash and energy in 2022, not stocks and bonds? That framework is called Gave's Four Quadrants, after Charles Gave, co-founder of Gavekal, a macro research firm. It uses two ratios built from market prices, the S&P 500 vs. Oil and Gold vs. Treasuries, to place the economy in one of four environments, and it describes what to own and what to avoid in each. Here's how stocks, bonds, gold, and cash tend to perform in each environment: → Deflationary boom: Stocks, bonds, and cash rise, and gold underperforms. → Inflationary boom: Stocks and gold rise, cash does very little, and bonds fall. → Deflationary bust: Bonds and cash rise, gold stays fairly stable, and stocks fall. → Inflationary bust: Gold and cash rise, while stocks and bonds fall. In my backtest of Gave's rules from 1970 to September 2026, a portfolio split equally between cash, the S&P 500, and either 10-year Treasuries or gold, whichever the framework favored, would have returned 5.7% per year after inflation. Its max drawdown was 28%, vs. 54% for the S&P 500. As of the end of September 2026, the two ratios place the U.S. in an inflationary boom phase. But since January 2025, the S&P 500 to gold ratio has been below its 7-year average, which has often come a few months before the S&P 500 to oil ratio drops below its own 7-year average. If that happens, the U.S. is back in an inflationary bust phase, like 2022. So how do you read the two ratios yourself, and what do they say to own today? That's what I walk through in my new ~20-minute video!
Continue reading here for what a budget slip would do to $BWXT’s stock in my bear case:
Wow! $ALTO $GPRE
@RealAssetsValue @hybridvigorish @thecontracap @barowsharo What just happened with $SNDA / $BKD?
Continue reading here for why lower HPDU costs mean less revenue but more profit for $BWXT:
@odeliaenergy Shipyard nuclear is $BWXT's home turf, it already builds two to three reactors a year for Navy subs and carriers. And this isn't the only transportable deal, on October 5 Prodigy picked its 20MW microreactor for a transportable plant in New Brunswick.
Devon Energy Sells Eagle Ford Assets to Crescent Energy for $4.2 Billion $DVN
Continue reading here for how $BWXT plans to deploy $5.5B of capital through 2030:
How did a boiler maker founded in 1867 become the Navy’s reactor supplier? BWX Technologies’ $BWXT history runs through two spin-offs and a decade of acquisitions: → 1867: George Babcock and Stephen Wilcox found Babcock & Wilcox (B&W) to make steam boilers. → 1953-1955: B&W builds components for the USS Nautilus, the first nuclear-powered submarine. → 1978: J. Ray McDermott, an offshore engineering firm, buys B&W. → 2008: B&W buys Nuclear Fuel Services, the Erwin, Tennessee plant behind the Navy’s fuel. → 2010: B&W spins off from McDermott as a standalone public company. → 2015: B&W spins off its boiler business as Babcock & Wilcox Enterprises $BW and renames itself BWX Technologies, keeping the naval and other nuclear businesses. → 2016-2020: Buys GE Hitachi Nuclear Energy Canada (fuel for CANDU, Canada’s heavy-water reactor design, 2016), Nordion’s medical isotope business (2018), and nuclear parts maker Laker Energy (2020), building out the Canadian commercial business. → 2022: Wins Project Pele, the Pentagon’s prototype transportable microreactor. → 2025: Buys the Aerojet Ordnance Tennessee (A.O.T.) unit of L3Harris $LHX for ~$100M in January and closes the Kinectrics deal (a Toronto-based nuclear engineering and testing firm, ~US$525M including assumed liabilities) in May. → 2026: Closes its purchase of Precision Components Group (PCG), a U.S. maker of heat exchangers and other heavy components, for ~$200M on July 1. Most recently, on August 3, Nordic Capital, a private equity firm, agreed to buy just over 80% of $BWXT’s medical isotope business for $750M plus up to $50M more. $BWXT wasn’t looking to sell until Nordic reached out, CEO Rex Geveden said on the Q2 call the same day. CFO Mike Fitzgerald said on the same call that the medical business should bring in $130M of 2026 revenue, at a margin “modestly accretive” to the 13% $BWXT expects from its commercial segment. Nordic’s $750M for just over 80% implies ~$0.9B for 100%, or ~7x revenue. At a ~14% margin, that’s ~50x EBITDA, more than double the 22.5x EBITDA $BWXT trades at. So $BWXT is selling a small side business at a premium to focus on what it calls its core businesses, nuclear national security and nuclear power.
Yellow Cake and Cameco say U.S. utilities have contracted only 40% of 2030 uranium needs, setting up a new contracting cycle as…

