
You can’t sell the picks and doubt the miners
Amazon’s AWS grew 37% year over year, with $496 billion of backlog and plans to double power capacity by 2027, challenging doubts about…
Monday, August 3
Everything we published on this day.
12 stories — the front page that day →
Amazon’s AWS grew 37% year over year, with $496 billion of backlog and plans to double power capacity by 2027, challenging doubts about…
Himax and the parallel optical bet $HIMX sits in two places in the optical stack: micro-lens arrays that route light into fiber, and a more speculative but potentially transformative position in microLED-based CPO. The microLED idea inverts the industry’s core assumption. Instead of fewer, ever-faster InP laser channels, it uses hundreds or thousands of simple low-speed lanes (4–10G each). High-speed SerDes and DSP largely disappear, energy drops below 1 pJ/bit, and the continuous-wave InP laser is eliminated entirely — replaced by GaN microLEDs from the display supply chain. Reliability improves and failures become graceful rather than catastrophic. Reach is limited to a few meters and the fiber-bundle ecosystem is still immature, so the technology is confined to short-reach scale-up. It remains pre-revenue and more debated than it was a few months ago. Yet the process know-how from Himax’s high-density display drivers maps unusually well onto this architecture. The stock is up ~55% YTD but down ~18% QTD, and currently trades around 31x EV/FCF and 10x EV/GP. For anyone who still sees a meaningful path for CPO — and views the microLED route as high-upside optionality rather than pure speculation — the current levels look like a reasonable place to build or add. We go deeper on the microLED architecture and its place in the broader optical stack in Part 4 of our Photonics series at Convequity.
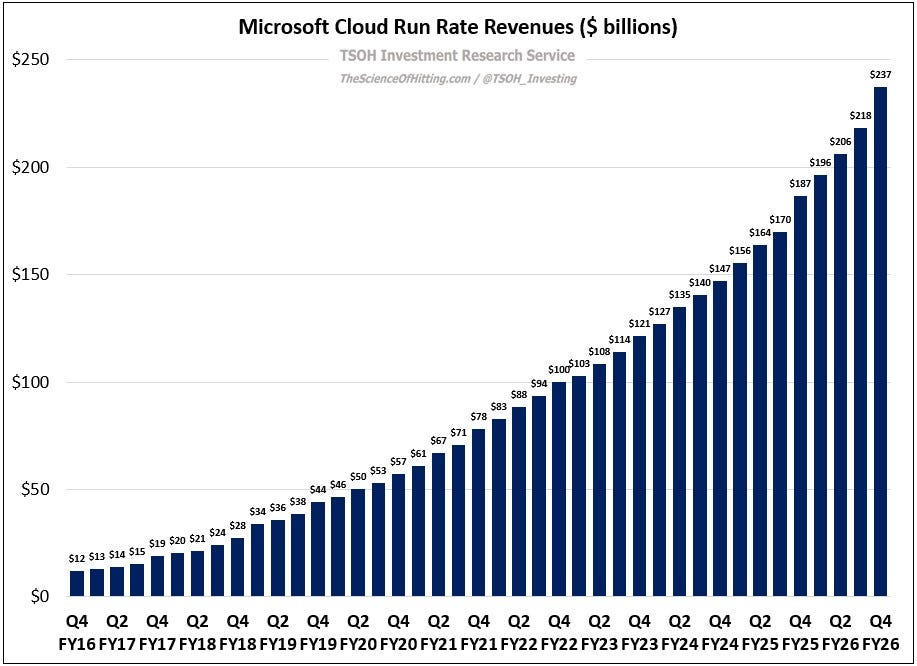
Microsoft’s cloud business grew from a $12 billion FY16 run rate to about $237 billion by FY26, while AI-era CapEx may exceed $200 billion…
Finally got a chance to go through the $UMG earnings... Obviously, a disappointment on revenue growth and margins, which saw the stock drop like 20%. Subscription revenue was 6.7% organically, and the street was looking for >9%. So, a big miss. Still, I think things should improve. Apple, Spotify, Amazon, and YouTube music have all raised prices this year, and a portion of that will go to UMG. CFO Matt Ellis said on the call that these prices and "better market share to start the third quarter" make them "cautiously optimistic" (really sticking his neck out there!!) that growth will improve in H2 of 2026. Interestingly, Warner Music $WMG managed to grow revenue 12% in CC and adjusted OIBDA by 24%, so clearly this is a UMG-only problem, at least for this quarter. $UMG trades at 14x earnings on a NTM basis now... this seems pretty reasonable if not downright cheap for a company that has grown EBIT from EUR 1b in 2019 to around 2b today (11% organic EBITDA CAGR). We own this through Bollore, which currently has an NAV of just above 11 EUR by my calculation vs a last price of under 4 EUR. Notably, JPM thinks new AI tiers in Spotify and Apple Music will drive ARPU growth of 300 bps per year. Their price target was 48 EUR prior to the recent earnings release...
Brazilian election. Who wins, and what's your view on $EWZ?
Very constructive development here w/ $STIM. We have both the largest shareholder and a major activist investor demonstrating full confidence in the balance sheet and new management. We think the new CFO has helped here and credit to Dan Reuvers for taking the CEO role at a tricky time but demonstrating a solid turnaround plan that has obviously has the backing of shareholders. For too long this business has under-punched its weight which is why activism became a reality in the first place. Clearly the new management has things pointed in a more exciting direction. At the same time, shareholder board nominations will ensure that the new direction remains one intent on maximizing equity value.
@Biohazard3737 I was leaning way more great bet for Citadel before today's $SOXX action. Opinion will change again fast from here... if $SOXX randomly nukes 10% in a few days though, yikes.
It's not THAT clear Citadel made a good bet. Probably good. But it could be losing. Three buckets: 1. Citadel brand buying the block creates a lot of buyers short term, letting them get out. A counter to this is: how many other funds/players blew up at the same time, with how much more stock still needing to be sold at any price by brokers? And redemptions. 2. The $SOXX drop was mostly just technical and will keep going up again after this. In which case Citadel will kill it. 3. The $SOXX drop was on real fundamentals, like the market knows the trade is over. In that case, Citadel stands to get slaughtered if the move continues down. Nobody really knows. Memory seems very questionable, though. I follow $TSM well and that seems merely fairly priced here, not a screamin' buy. $NVDA seems hard today, with all this chatter of competing chips / AI getting so powerful the software moat seems like probable junk in a few years.
@pradeeepk $AMD + ASICs will eat $NVDA margins
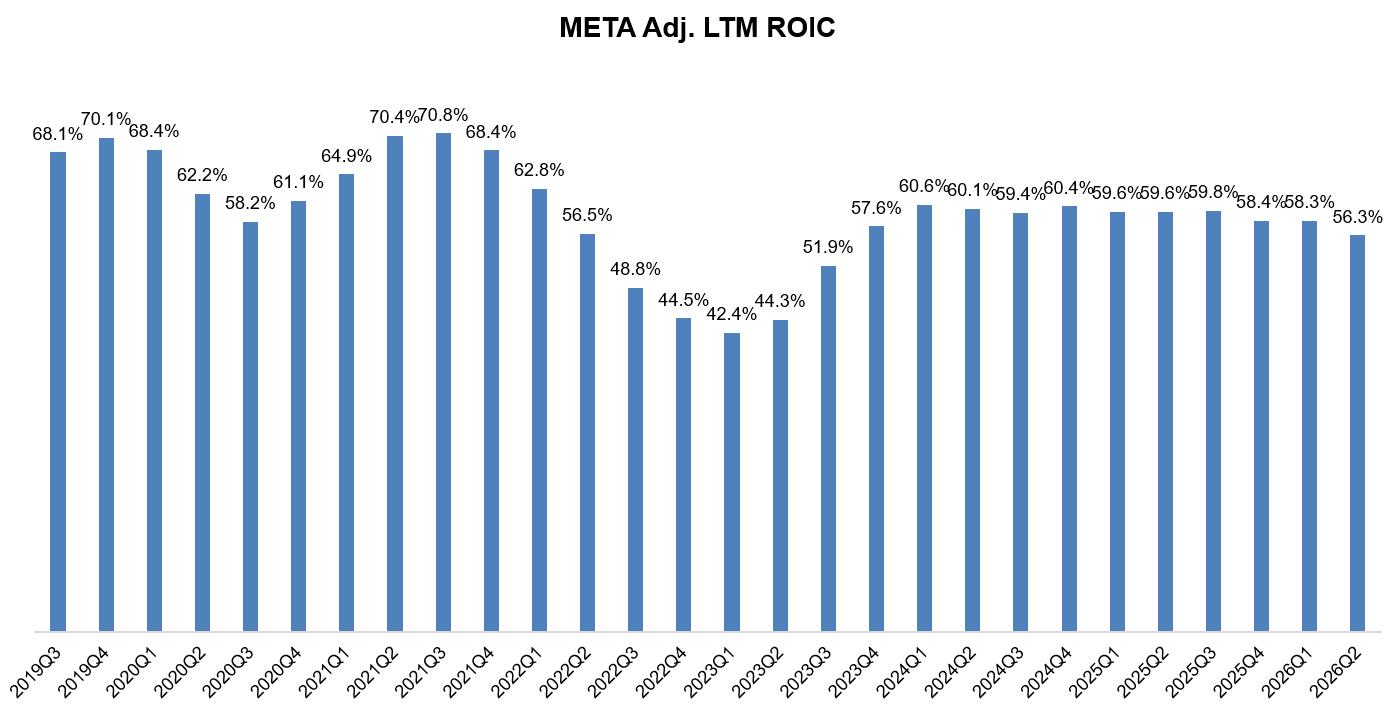
Meta’s adjusted LTM ROIC is in the mid-50s after excluding $80 billion of construction in progress; that capacity will lower returns as AI…

Lionheart Holdings’ 41-cent CUBWW warrants hinge on a SPAC merger valuing KEO Energy’s Venezuelan PetroUrdaneta stake at $1 billion, versus…
Builders FirstSource reported Q2 2026 sales down 9% to $3.9 billion as weak housing demand and aggressive competitor pricing cut EBITDA…
