
Sharp Tech on Video: Netflix Angst, the End of the Internet, and Meta’s VR Glasses
Sharp Tech launches on video, covering Netflix, the internet’s future and Meta’s VR glasses.
NASDAQ
META
218 stories
$1.6T Market cap · 2026-10-28
Sharp Tech launches on video, covering Netflix, the internet’s future and Meta’s VR glasses.
By the end of 2026 $META will have spent $390 billion on AI and they have this to show for it. LMAOOOO https://t.co/DD2bkZKltR
Absent the very odd 8k, $META results were strong. - 26% revenue growth - Guided to ~150bp acceleration in 4Q at the midpoint - 10M muse accounts, 15M Meta One, and both are in infancy and mostly just rolled to North America. 92% of META users are outside NA - Committed to bring down FRL losses and trend towards profitability over time Stock is trading at a low-mid teens multiple of ex-Muse/FRL earnings and ~19x EPS fully capitalizing those investments. Without the cap raise 8k, the stock would be up. If we assume they might raise $100B, with 0 ROIC on the invested proceeds, maybe the equity raise has a max negative value of -6% in the most punitive scenario. Think the underlying results were strong enough to offset and stock has overreacted.
It is so hilarious how $META is raising equity to not only pump more money into failing Muse but also so Zuckerberg can pay his tax bill in California. Socializing Zuck's tax bill from common shareholders is so funny. I have never even seen this kind of move from some of the worst shitcos in microcap land. What a hilarious thing. Growth investors are so funny.
We have no exposure to AI stocks and honestly don’t see much difference between the AI models we are currently subscribed to, let alone tracking new, emerging models. But Minotaur @MinotaurFund did a deep dive into Meta Platform $META’s recently introduced AI agent, Muse, and bought the stock back last Sep, on the premise that consumer agents are a new frontier that Meta could be a leader in.
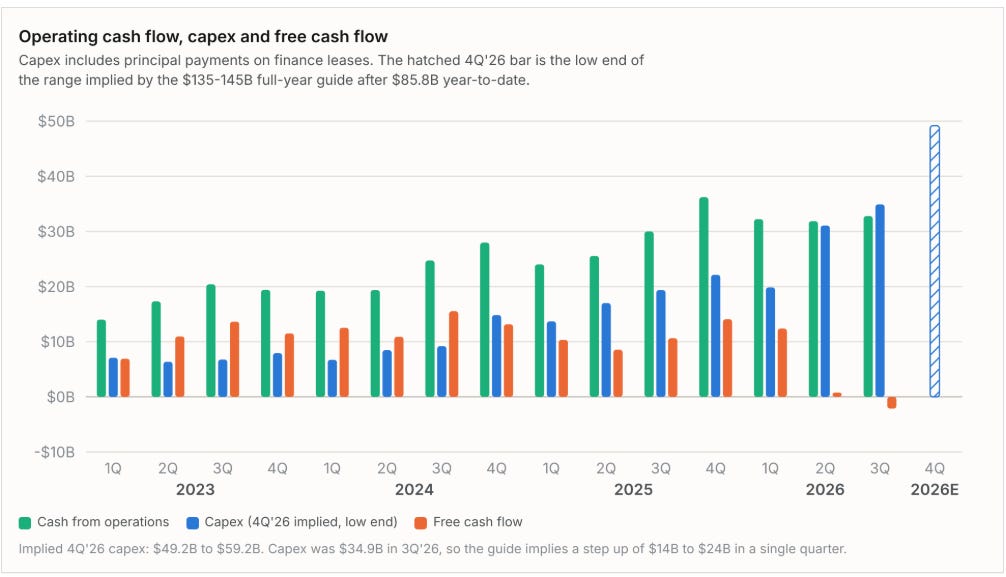
Meta’s ad revenue grew 26% to $63.1 billion, but negative free cash flow and $135-145 billion of capex raise concerns over AI funding and a…
Whoops. Investors beginning to realize that $META issuing equity for capex is a shitco move. https://t.co/JZaCvO2fOC https://t.co/i7TIcEVCyk
$META said ARPU on Muse will eventually be higher than existing ARPU on family of apps. That's triple digit. Incredibly bullish for META if it happens - would 2x revenue at least, using low end of Zuck comments. But where does the share come from? Agentic shopping is not nearly enough GMV to take unless they take a substantial chunk of the TAM and fully disrupt companies like $AMZN. You start killing retail then you also kill your ad customers. Just seems like there are real problems with the napkin math playing out.
@alexandr_wang @finkd FYI, the market is speaking and saying they don’t want you guys to issue “hundreds of billions” of stock for Muse $META business results were fantastic. Just overshadowed by fear of dilution.
Thanks for the free compute, Zuck! $ORR $META https://t.co/RXRI1xjRbL
Meta’s Q3 revenue rose 26% to $64.6 billion, but $34.9 billion in AI infrastructure spending drove free cash flow negative as it created…
Meta’s Family of Apps revenue grew 26% as Muse reached 10 million users, testing AI-agent commerce while Amazon restricts access and…
Meta reported Q3 revenue of $64.6 billion, up 26%, while $34.9 billion of capex drove negative free cash flow and a $9.89 billion legal…
One mantra rules everything right now in the AI space: BE FIRST! $SPCX pulled forward its earnings release date, $META rushes to form a new class of shares, and we'll see what the other hyperscalers have to say in the next 7-10 days. The Anthropic bankers cannot be happy with this disclosure from $META's new share class filing tonight (so many jewels in this document, it's a must read): "The Special Committee also recognized that timing is important to secure capital before competitors saturate various funding options. Recent significant capital raises at other notable companies, and others soon anticipated to take place, to fund the same AI growth—for example, Alphabet, SpaceX, Anthropic, and OpenAI—have resulted in an increasingly challenging environment for raising capital. The Special Committee considered that, while the Company presently has sufficient capital resources for its current needs, in order to finance its funding needs going forward it would be prudent for the Company to do so before even more companies have absorbed available capital in the market." https://t.co/yVUhuq7dLb

Meta’s 3Q26 Family of Apps revenue rose 26% as Muse reached 10 million users, testing AI-agent shopping that Walmart permits while Amazon…
$META financing capex through an equity raise that keeps the super voting shares in tact has me still on the ground rolling and laughing like an idiot. This is shit you would see out of a microcap crapco. Not a high flying “tech” company. Getting a lot of hate for talking shit. Because apparently Meta has to do this or they will “die”. I fail to see how an addictive social media platform that’s worse than smoking cigarettes is going to die by skipping out on this massive capex AI cycle. My god.
Unfortunately I don’t think $META trades well in the near term and probably goes back to being a funding short Everyone has known Zuck has sorta been flying blind when it comes to AI (he even said so with Wang when he tried to chew that pint down like it was vodka) and tonight didn’t really help. Muse monetization feels very uncertain, at least with respect to timing. I also still think people enjoy shopping and buying things themselves (especially people who typically buy things off Instagram and Facebook) but that’s up for debate and will take time to prove out. Anecdotally, myself and everyone I’ve talked to about Muse now struggle to find reasons to use it regularly I think Muse monetization will probably turn guilty of being a disappointment until it’s proven otherwise, which could take a very long time Not to mention the equity issuance overhang and not providing FY27 revenue guidance leaves even more uncertainty. It’s been a great rally for Meta recently but I fear it could be headed back to the doghouse
If you're buying $META here after hours and you're not sure if you're exit liquidity, take a look at this from the share class filing: " Representatives of Moelis also noted that the Company had not yet provided its long-range plan for the Moelis and Special Committee Counsel teams to review, but that the Company’s management had orally conveyed to Special Committee Counsel and Moelis that management had previously presented three forecast cases to the Board during a regularly scheduled Board meeting in May, and that, in each case, these long-term forecasts showed the Company’s need to raise hundreds of billions of dollars over a period of several years beginning as early as fall 2026." https://t.co/Mvc3znfrtS
Muse is cool. But the most talked about consumer use case seems to be agentic commerce which I struggle to see as solving a real problem for people. Consumers don't mind shopping. Whether I tell Muse what I want to buy or whether I tell Amazon, I still have to think about it and decide. And I doubt most people will be OK with Muse proactively buying stuff for them. To be fair, researching travel and price comparing on big ticket things is definitely helpful, but not sure why Muse more uniquely qualified for that use case than any other LLM. Most important metric for $META over next 12-18 months will be Muse users.
Zuck on Muse monetization: "My guess I think that we are going to work on monetization somewhat sooner on this than our normal playbook for a couple of reasons." "One is just the size of the numbers that we're talking about in terms of both the costs and the opportunity. I think make it kind of important to make progress on that in order to be able to scale it. The other is just that such a large part of what people are doing is commerce." Ads ads ads x100 $META
How much will $META raise through equity offerings of this new Class of shares over the next 12-months?
Meta Platforms $META is literally, and I mean LITERALLY, named after its last mistake and now they are about to raise equity to fund more AI nonsense. They are spending so much Capex. Capex was more than cash from operations this quarter and will be more in the full year based on their guide. How did a capital lite tech company turn into a Capex pit? Kind of wild. There is no cash flow anymore. And they are raising equity that won't dilute Zuck's supervoting shares. Pretty terrible corporate governance if you ask me.
$META Q3 Earnings: Revenue: $64.60B vs $63.33B 🟢 EPS: $3.83 vs $6.80 🔴 (Negatively impacted by legal expense. They beat EPS ex-legal fees) Q4 Guide Revenue: $73B-$76B vs $73.73B FY Guide Capex: $135B-$145B vs $130B- $145B
$META So rug pull then for earnings? https://t.co/bMZvdnIu3W
Letters that discuss META.
Companies the stories above are also about, besides META.


