
The Fed Is Going to Lose the Bond Market and I Found the Asset That Gets Paid When It Does
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
Sector
Everything our editor has picked under this sector, best first.
239 stories
Rayonier’s 4.0 million acres are valued at $393 an acre after other assets, versus $1,200 to $1,800 cutover-land sales, framing the timber…
The bottleneck play on this is $COMP? 🧭 https://t.co/1ClFMI3z4d
It's Tecnoglass time $tgls. https://t.co/5gjN6emyo1
This man is probably an activist investor in $RYN trying to create his own catalyst by removing timber supply from the market. Heard he has an MBA from Wharton too and his wife hates him. https://t.co/sAp2HUFNaO
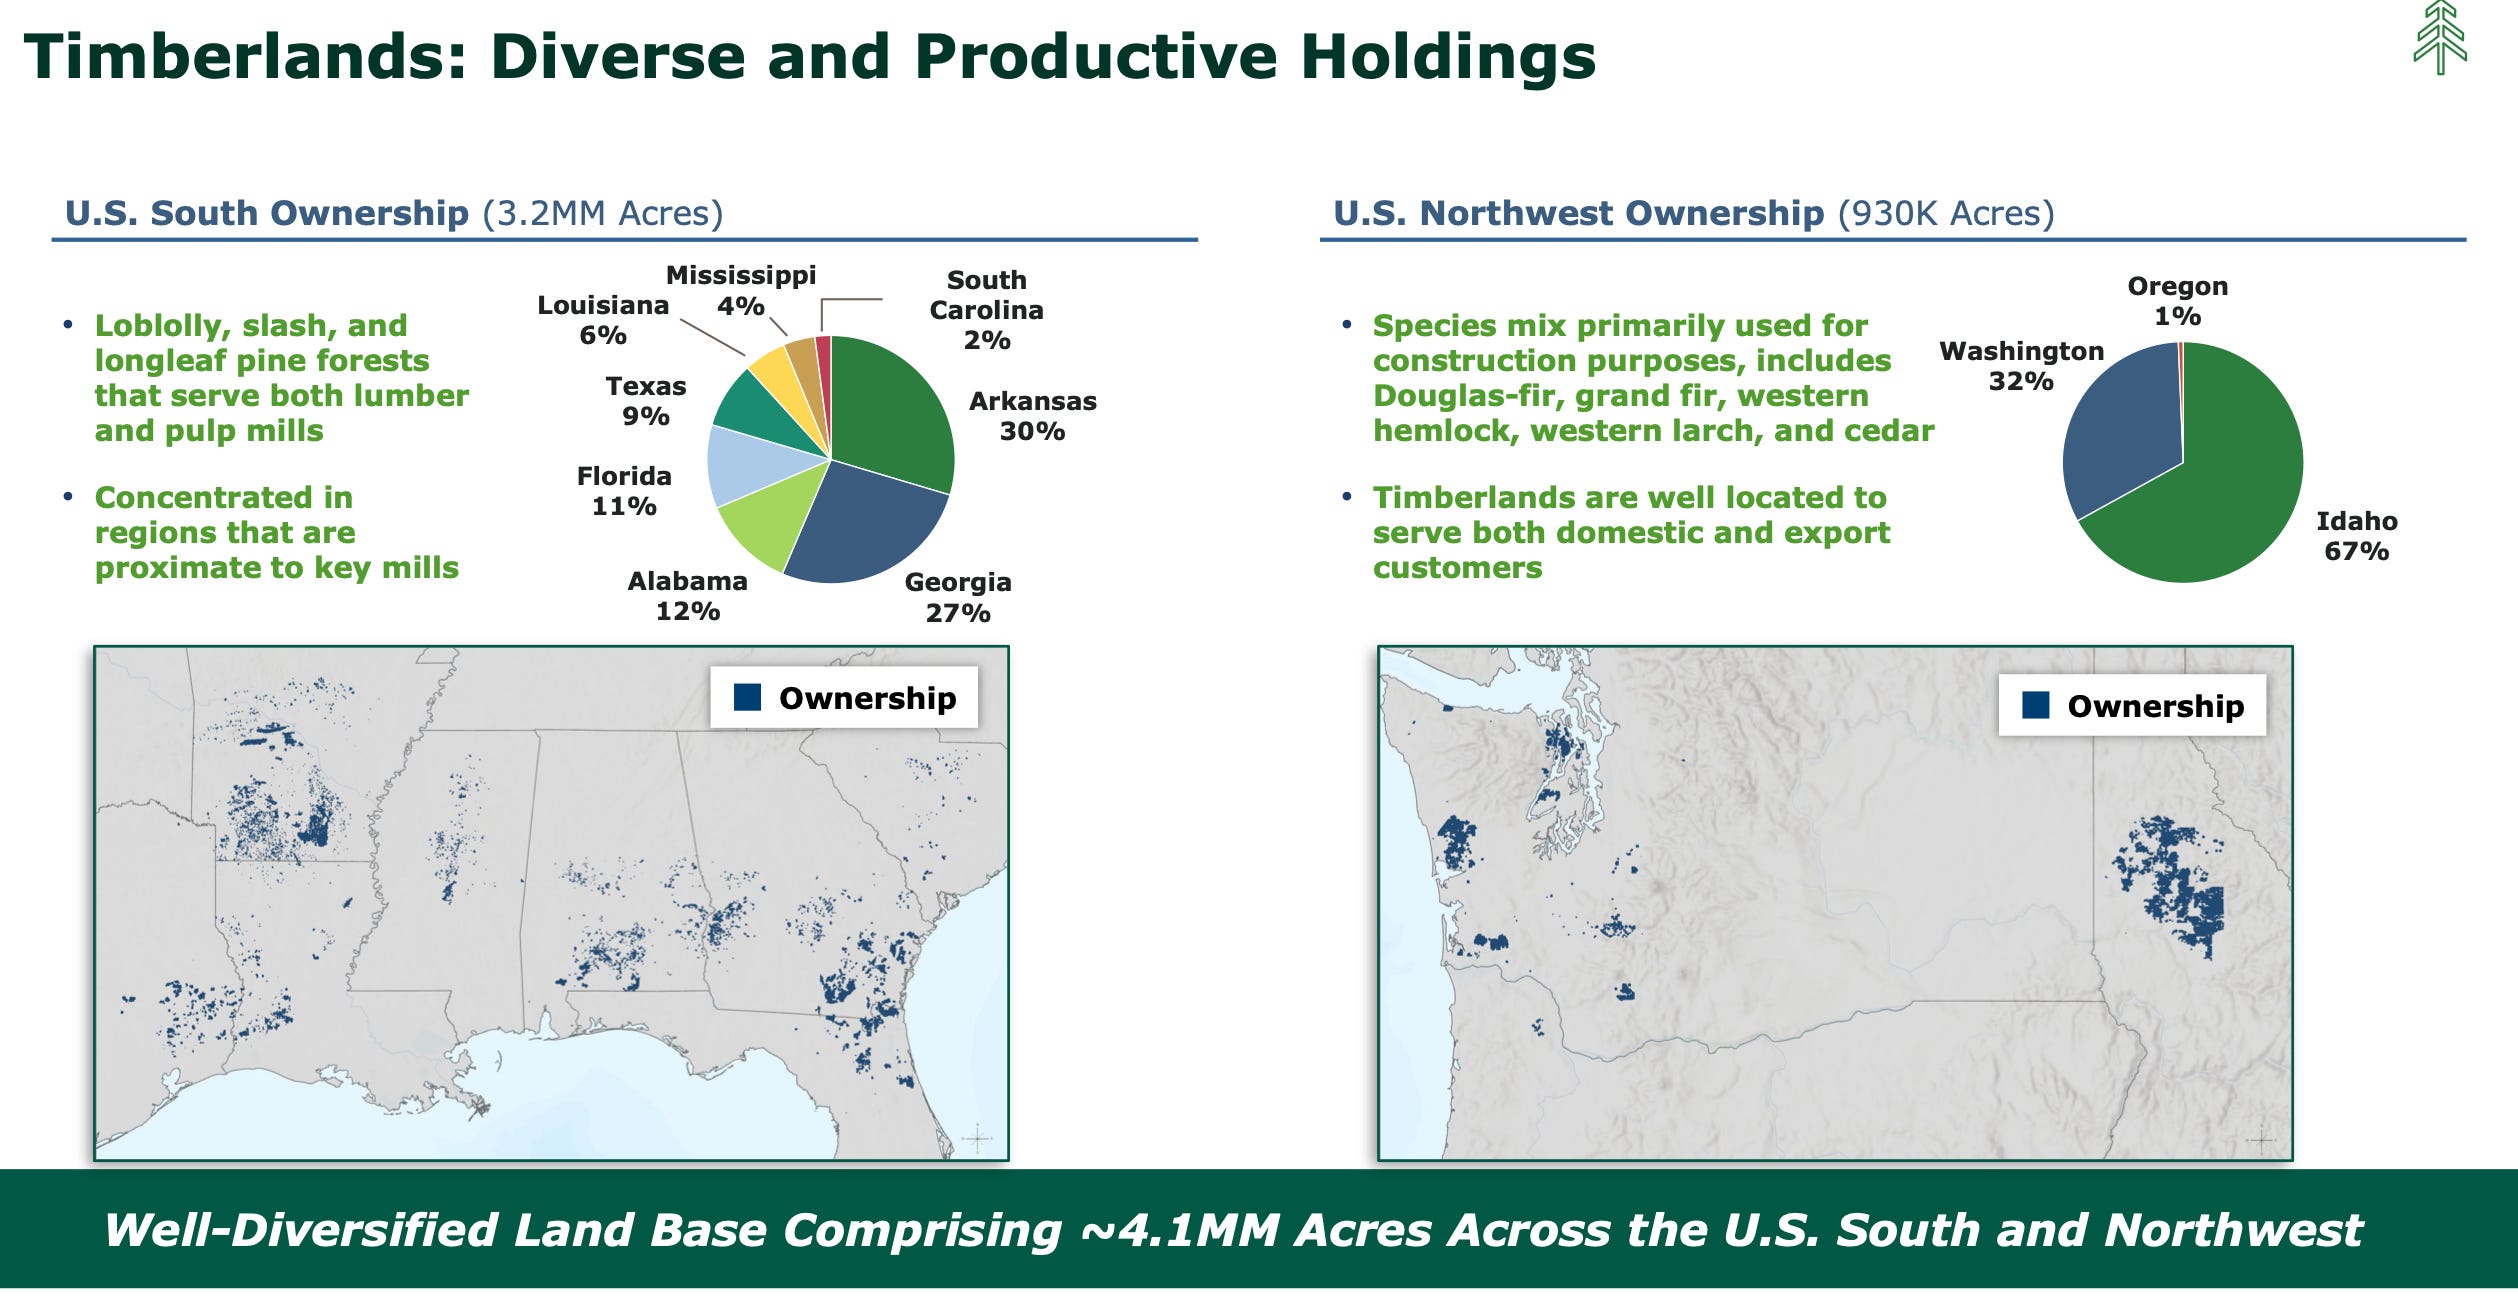
Rayonier $RYN owns 4,003,000 acres across eleven states. Here's what happens when you value everything else on the balance sheet and subtract it. Enterprise value is $7.64B. Market cap $6.19B plus $1.45B of net debt. Now take out the pieces that aren't dirt: Six sawmills and a plywood mill, $1.0B. Cross-checked two ways. Replacement cost runs ~$700/MBF on 1,155 MMBF of capacity. Mid-cycle EBITDA of $175M at 6x gets you the same place. Three master-planned communities, $482M. Wildlight north of Jacksonville, Heartwood next to Hyundai's $7.59B plant in Georgia, Chenal Valley in Little Rock at 70% sold out. DCF'd at 12%. The rural land program, $650M. They sold 7,490 acres at $5,439 last quarter against a portfolio the market marks at $1,447. That 3.7x spread on ~30,000 acres a year, decayed and discounted over a 13-year runway. Solar options on 77,000 acres, $125M at a 25% conversion assumption. Carbon storage across 154,000 acres, $80M. Smackover lithium, $30M. Real geology, ten cents a share. The below-market debt mark, $130M, audited on the balance sheet. That leaves $5.14B for the timberland. Now subtract the trees. 188M tons of standing merchantable inventory at current TimberMart-South stumpage, with pine sawtimber at $23.34/ton and pulpwood at $5.40, is $3.57B. Residual: $1.57B of bare land across 4,003,000 acres. $393 an acre. Cutover land in the South, meaning ground that was just harvested with zero merchantable timber on it, transacts between $1,200 and $1,800. Three marks you can check yourself: In August the company sold 36,000 Washington acres at $4,028 and bought 57,000 Texas and Alabama acres at $2,561. Same month, same management. They paid 77% more than the market credits them for what they already own. Morgan Stanley's fairness opinion produced $47.55 to $55.80 on a DCF and $20.85 to $25.20 on trading comps in the same document. The stock is at $20.81. That gap is institutional cost of capital at 7% versus public equity demanding 9 to 10%, applied to an asset with thirty-year cash flows. Management bought back 4.9M shares for $103.5M in H1 and repaid a $200M term loan with cash rather than refinance it. I built the whole thing a second way, from transaction comps by state instead of tons and dirt. $31.80 versus $31.66. Bear case marks the entire South at $1,700/acre, puts the mills at a trough multiple, converts solar at 15%, and still lands at $24.74. Every case sits above the current price. One caveat I'll state myself: the $393 assumes rural HBU is a separate asset. Treat it as embedded in land value instead and you get $555. Still under cutover. The conclusion holds either way. Full work, every input shown, plus the part about the debt structure that I think almost nobody is modeling, linked below.
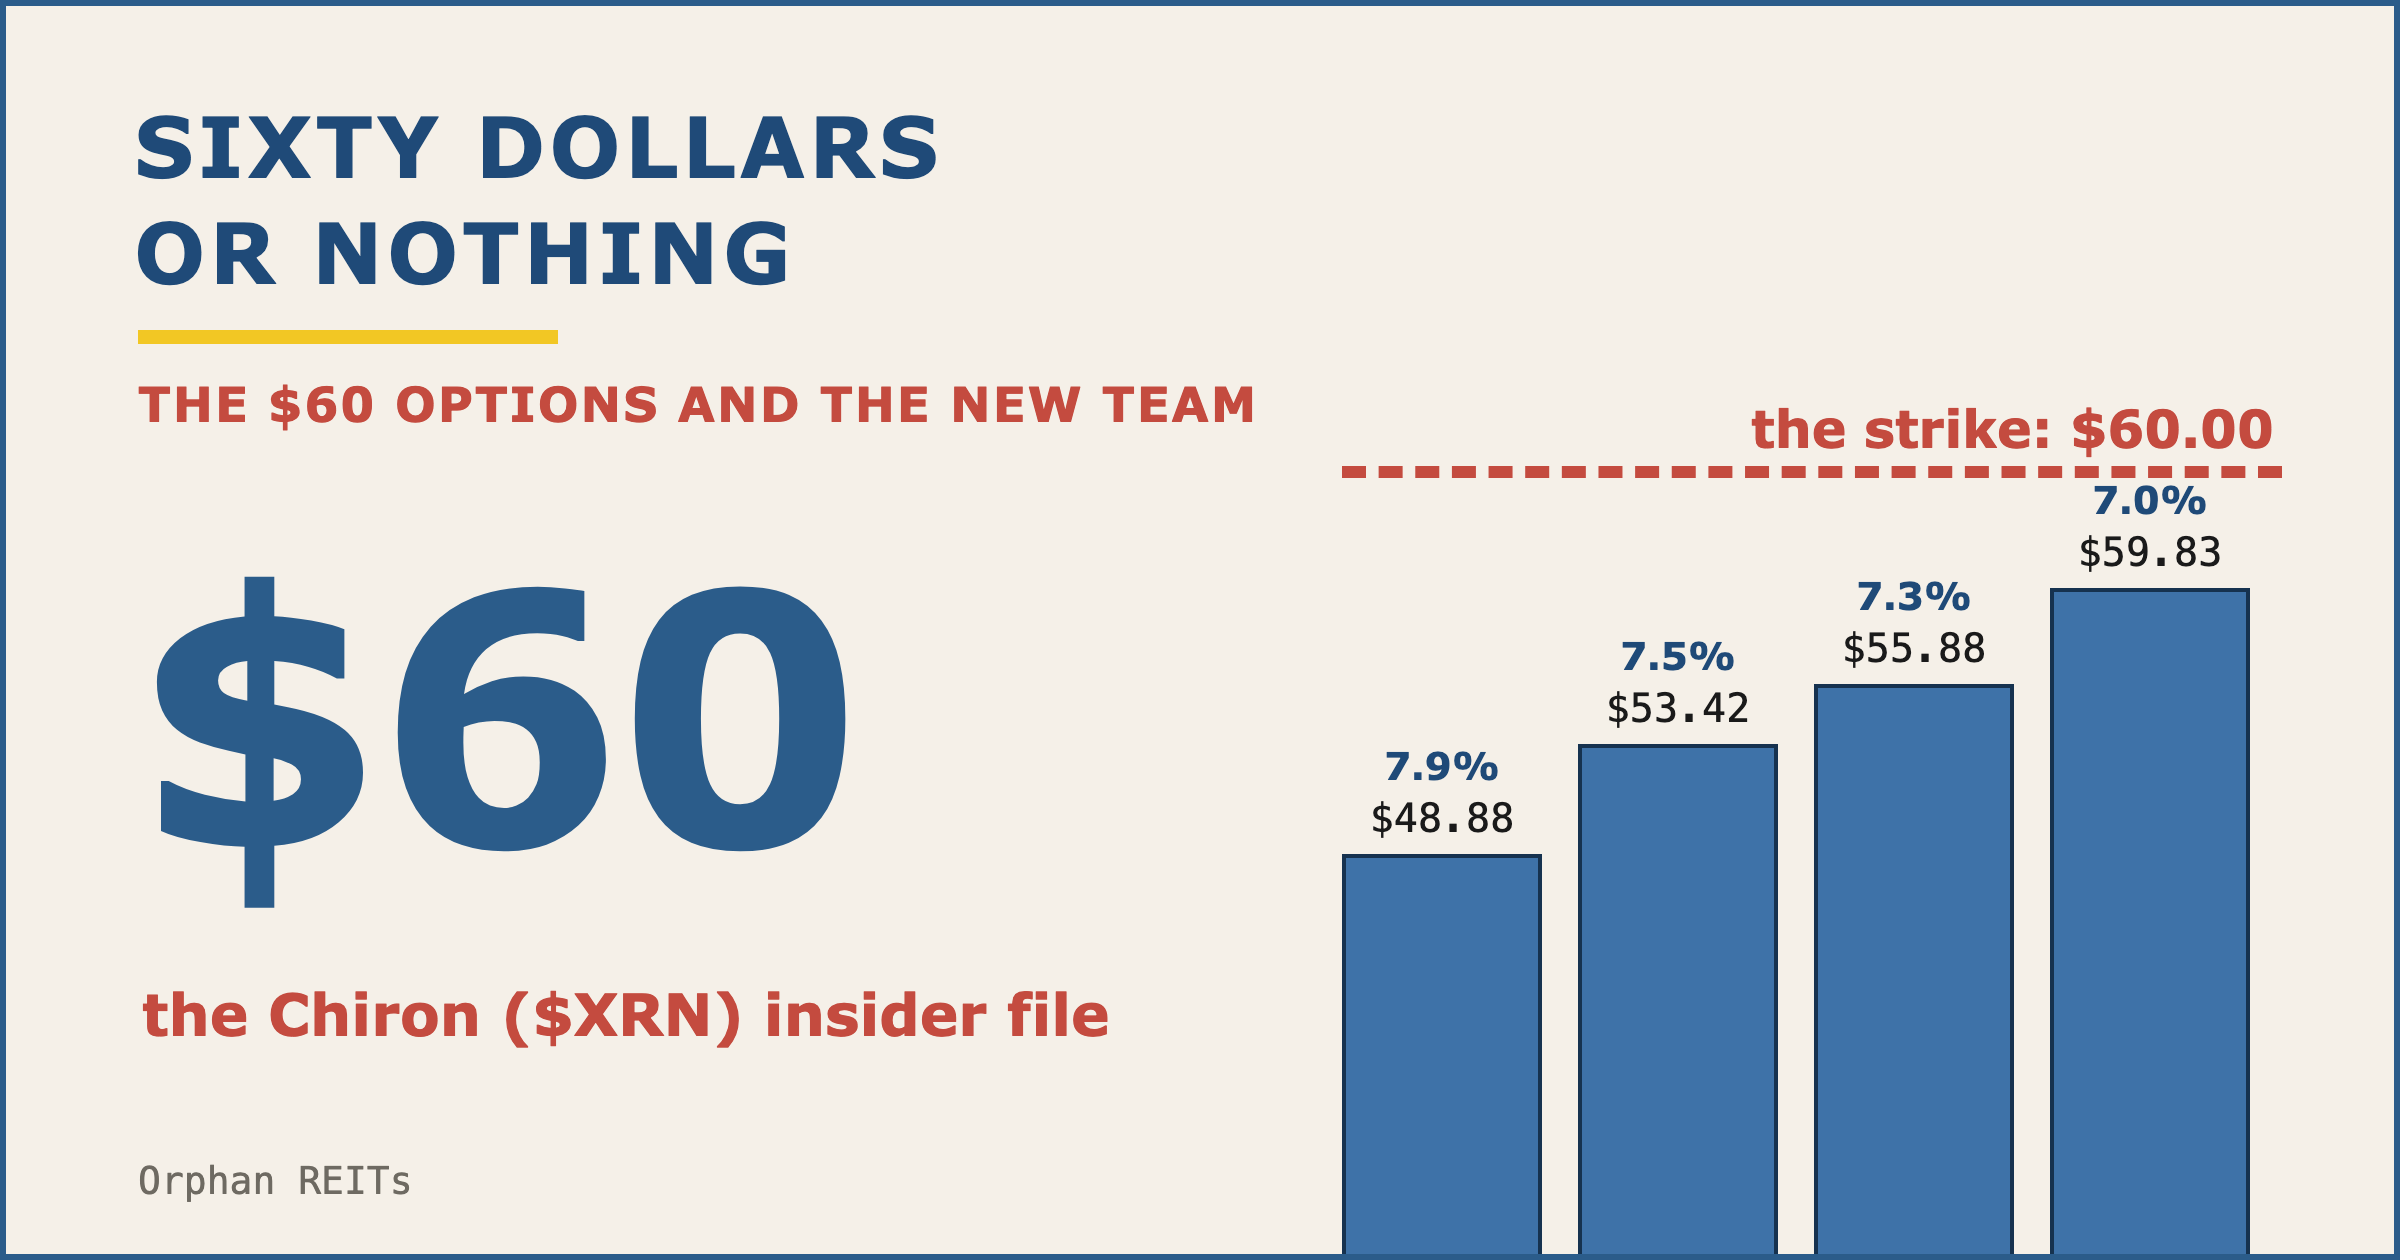
Chiron granted seven executives 195,610 options at a $60 strike, 63% above the market price and above its published valuation range.
IF YOU ALLOCATE CAPITAL PROCYCLICALLY, YOU SHOULDN'T RUN A YUUUUGELY CYCLICAL BUSINESS $BLDR - Can anyone name a good (counter-cyclical) mngmt team that isn't named Lundin? https://t.co/yHn2kFBkuP
@pradeeepk I think you wait until it shows up (even more!) in $BLDR's numbers and markets suddenly start worrying about leverage. Investores don't care about balance sheets until it's suddenly the only thing they care about, and that's when stuff really crash.
@sophieanalytics Sweet thanks. Haven't dug much in $WY yet. Just been doing $RYN. So WY doesn't do much HBU?
Timber companies are a hard asset and low risk way to play the datacenter boom. $RYN $WY https://t.co/YElT0VT8R9
$QXO finally in my valuation zone, acquired shares this afternoon. Rates present a challenge, soft commodities surging and geopolitical could further stress inflation/yields but you usually do not get deal when everything is firing on all cylinders
Rayonier’s $1.86B debt costs 2.29% after swaps and Farm Credit patronage refunds, giving its four million timber acres a cheap fixed-rate funding edge through 2028-29.
@SovietInvestor ok well $RYN sells for $1,800 per acre...
This $WY looks like another dirt cheap timber REIT. Been doing a deep dive on the entire sector. Getting slammed from higher yields and home building slowing down. But these are incredible inflation assets and irreplaceable. It’s something I would hold as a cash alternative. Because you can’t trust cash at this point in the credit cycle. Own cheap timber.
@leevalueroach $BWEL
Owning timber REITs here seems like a no brainer. $RYN has an enterprise value of $7.4 billion. They own four million acres. You are buying this for $1,817 per acre. That is dirt cheap. Find me anywhere else you can own a large swath of land for $1,817 per acre. You can’t! The public market will punish RYN for owning a large amount of land. Lower valuation and will call it a value trap. But imagine the optionality of owning this large amount of land. Texas Pacific Land owned a large amount of land and look what happened to their stock price. One of the best performers ever. I’ve done well owning land banks. This one pays a fat dividend. Rare. Market is asleep at the wheel with their pants down and drooling.

Higher rates could compress equity multiples and raise AI data center lease costs, while UWMC and Cogent raise questions about CEO-driven…
Higher rates threaten equity multiples and AI data-center economics, while UWMC and Cogent raise questions about CEO-driven capital…
 TPC 2026-08-27
Tutor Perini’s Q2 revenue rose 19% to $1.64 billion as higher-margin megaprojects lifted construction income 54%, prompting higher 2026 EPS…
 The Curious Analyst
 STRL · short
Sterling Infrastructure short pairs STRL against EME and FIX, arguing data-center sitework contractors lack the margin upside available to…
Atlas Engineered Products reported Q2 revenue up 19% to $16.2 million, but ended cashless on its credit line as inventory rose 47% and…
Yes, you're touching on some of the issues that $Z/$ZG faces in the residential real estate landscape. There are reasons that the stock trades at 8-9x FY27 consensus EBITDA even though the company continues to grow revenues at a mid-teens clip YOY organically while generating huge FCF. We've written HUNDREDS of pages on these issues so this is not the right forum to litigate the relative merits of any of these concerns. Zillow has a lot of organic initiatives that should sustain growth for the next few years. From all my work, the commission structure of the industry is not changing much right now, but of course that seems inevitable at some point. If you really drill down to what $Z/$ZG is doing strategically it's all about becoming more deeply integrated into the transaction. Follow-up Boss was the most important acquisition the company ever made IMO. You don't need to see around corners here, but you have to look through the noise to see what the company's doing.
The bigger issue I think is if changes in commission structures ongoing in real estate changes Zillows position in the industry and if they need to overhaul their model on the housing side? ZG running straight into https://t.co/xkzar3nuEl with success to increase supply and they'll both likely end up sharing that market (more a negative against csgp as they have the larger share in the rental space currently) but I think they end up shrinking that pie with their competitive attacks against each other. The compass and regional MLS provider lawsuit on exclusives, supply I think is the bigger case hanging over $ZG currently because thats one of the few threats to their dominance in mindhare in shopping/looking at homes online and their ad revenues there
$Z/$ZG announces it reached a resolution with the FTC on the commission's anti-trust allegations related to the #zillow/#redfin rentals syndication deal. The partnership will continue going forward but $RKT/Redfin will be required to buildout its own rentals listings syndication platform and Zillow will waive any non-competes. My sense is that $RKT/#Redfin are not hugely interested in the rentals space at this time and Zillow's market share gains will continue at a robust clip. This is a positive for $Z/$ZG and eliminates another litigation overhang. We estimate the size of the rental property advertising landscape at $9-$10B annually. One has to wonder where this lawsuit came from given that it involved a $100MM deal in a massive marketplace. $CSGP?
