
Lee Roach on X
Timberland companies looking pretty decent here. $RYN. https://t.co/tlr3d7MiCs
Sector
Everything our editor has picked under this sector, best first.
239 stories
Timberland companies looking pretty decent here. $RYN. https://t.co/tlr3d7MiCs
$HHH perhaps this line from the recent proxy filing is what is causing market to move: "Discussions will include ... efforts to significantly reduce the capital intensity of Howard Hughes Communities" https://t.co/8sBEkb8X5A
A contrarian pick, for AI-like return in real estate. $STWD (Starwood Property Trust) has an asymmetric setup for a possible ~50% total return over the next 12 months If Treasury yields peaks and then declines back within the next year, then a combination of the current 13.3% div yield + rerating back to above its undepreciated book value ($19/share) results in close to 50% return for this best of breed lender. True Multi-Cylinder Engine: Unlike pure-play lenders exposed to a single-sector, $STWD operates across commercial lending, infrastructure, and owned real estate. Built-in Counter-Cyclical Hedge: Its Special Servicing and Investing arm actually benefits when market volatility rises, collecting servicing fees that insulate cash flows when traditional credit tightens. Office Risk Is Overblown: U.S. office makes up less than 8% of its total asset base, with the balance anchored in residential, industrial, and essential infrastructure. Unmatched Dividend Track Record: Management has maintained its quarterly dividend for over 17 yrs without a single cut through multiple rate cycles. Collecting a 13.3% cash yield while waiting for a yield-driven rerating could deliver an equity-like upside with institutional downside protection.
A contrarian pick, for AI-like return in real estate. $STWD (Starwood Property Trust) has an asymmetric setup for a possible ~50% total return over the next 12 months If Treasury yields peaks and then declines back with the next year, then a combination of its current 13.3% div yield + rerating back to above its undepreciated book value ($19/share) results in close to 50% return for this best of breed lender. True Multi-Cylinder Engine: Unlike pure-play lenders exposed to a single-sector, $STWD operates across commercial lending, infrastructure, and owned real estate. Built-in Counter-Cyclical Hedge: Its Special Servicing and Investing arm actually benefits when market volatility rises, collecting servicing fees that insulate cash flows when traditional credit tightens. Office Risk Is Overblown: U.S. office makes up less than 8% of its total asset base, with the balance anchored in residential, industrial, and essential infrastructure. Unmatched Dividend Track Record: Management has maintained its quarterly dividend for over 17 yrs without a single cut through multiple rate cycles. Collecting a 13.3% cash yield while waiting for a yield-driven rerating could deliver an equity-like upside with institutional downside protection.
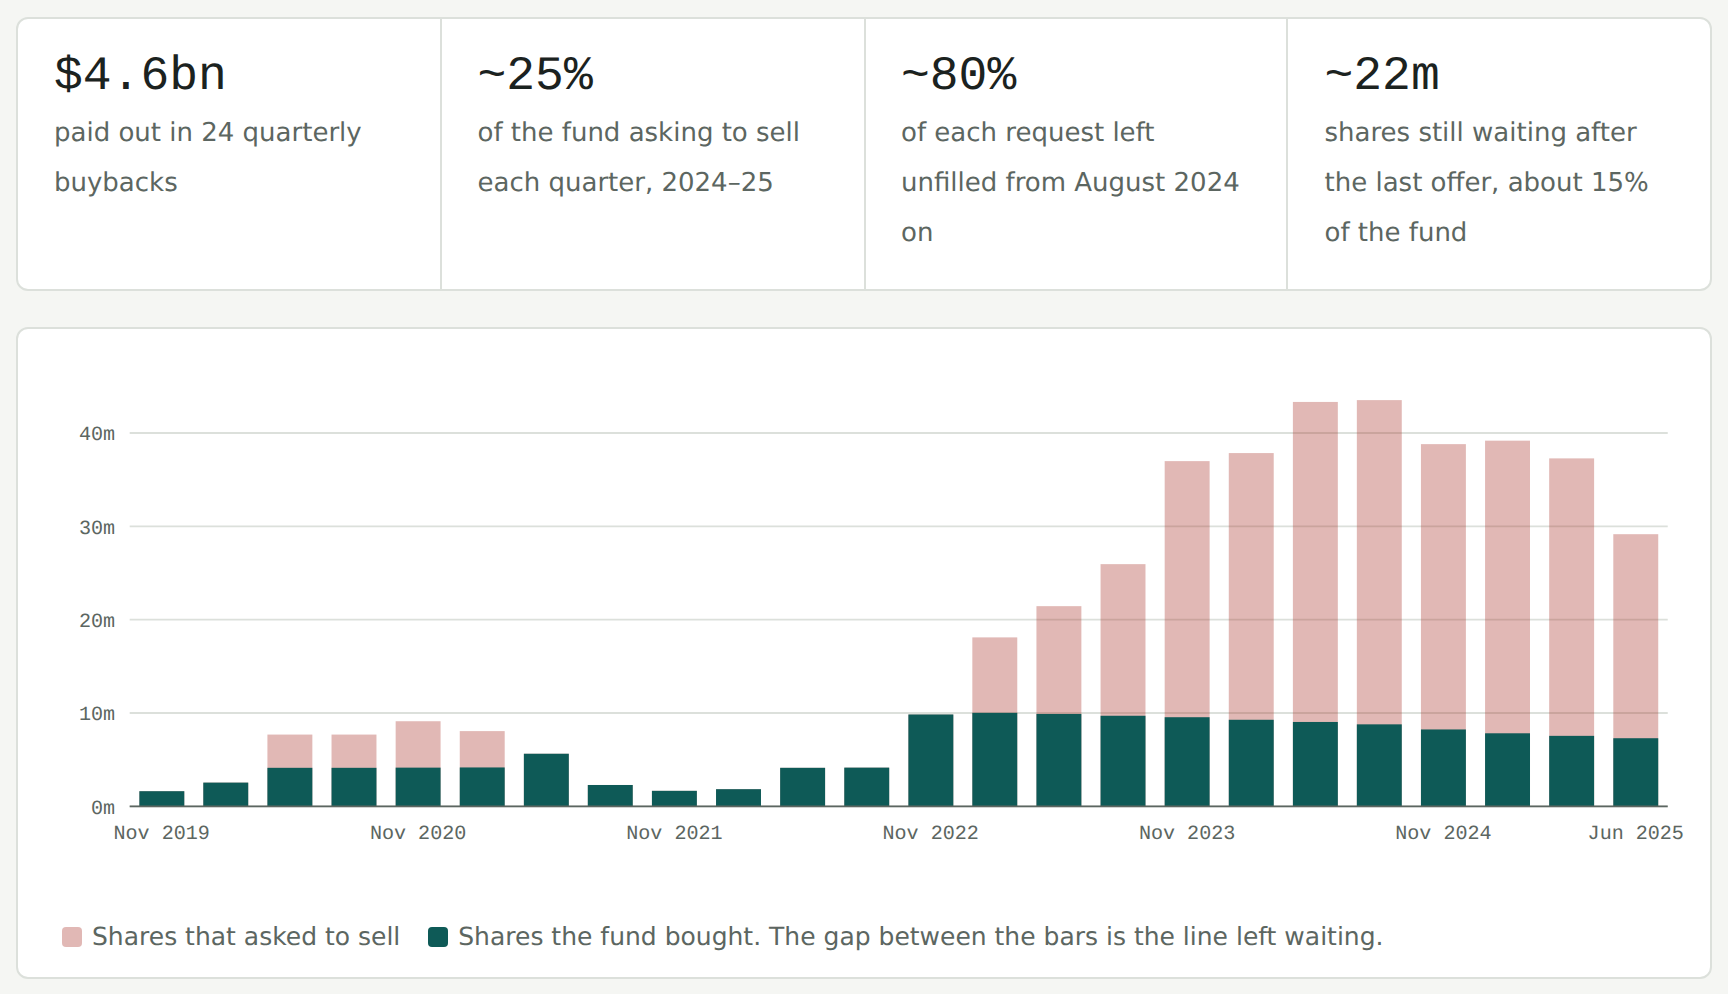
BPRE trades 45% below NAV as Saba and Bulldog press for buybacks or a manager change, challenging Bluerock’s incentive to preserve…
Neighborhood Intelligence, NXH, faces a cash shortfall after failed and restructured acquisitions, as losses and limited financing options…
 Vince Martin 1 click
@_Housing_Guy_ Structural deficit in houses will need to balance eventually. Cycle will cycle eventually (rates, inflation economy ect). Company won’t go bankrupt and will chug along until then. Transition to capital light $NVR model not fully priced in.
$CXW got a new President/CEO today. https://t.co/7WpulDuHkg
Turtle Creek tripled its shares in Colliers $CIGI, its largest detractor of 2026, taking it from a below-average weight to a top-five holding after a near-50% fall. It blames multiple compression rather than earnings, and the AI-disruption trade rather than the business: brokers still meet clients about office space, and human engineers still visit buildings and construction sites. Founder-CEO Jay Hennick, already a 12%+ owner, bought over $55m of stock on the open market during the decline.
The Howard Hughes Holdings Inc. ($HHH) 2026 Shareholder Meeting will take place next Wednesday September 30th at The Auditorium at 787 Seventh Ave in New York City. At the meeting, among other topics, we will discuss how we intend to accelerate the transformation of HHH to an insurance holding company by dramatically reducing the capital intensity of our Howard Hughes Communities real estate subsidiary, freeing up capital to be invested in Vantage, our insurance subsidiary. HHH CEO David O'Reilly, Ryan Israel CIO, Marc Grandisson Executive Chairman of Vantage, and I will make a presentation and address audience Q&A. Advanced registration for the meeting is required with priority given to HHH stockholders. To register, visit: https://t.co/mPPE8xiQd2
Rocket Companies combines Redfin, Rocket Mortgage and Mr. Cooper into an end-to-end homeownership platform, adding mortgage servicing fees…
Realty Income trades at 12.7 times forward AFFO with a 5.8% yield, supported by high occupancy, a 73% payout ratio and raised 2026 guidance.
 Sharon McArd 2 clicks
KB Home Cuts Margin Outlook as Housing Conditions Worsen $KBH https://t.co/OA4utledZC
I've been flat out wrong on $NEN and no longer own it, so it probably works now. ICYMI, the Brown family filed a 13D as a group in June for the first time since Harold passed. I found this sentence interesting. From what I can tell, this language wasn't in any historical family ownership filings.
 INVH · long
Invitation Homes owns more than 85,000 homes valued at $43 to $48 per share, versus a roughly $30 share price, with occupancy above 96%.
What's going down faster, $OPEN's stock price or Rabois' credibility as a geopolitical analyst? https://t.co/ThqR7rsRsO
@valuedrift I was watching this and $GEO rally for months and finally put the short on myself... absolutely silly up here.
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
Fundamental issue with $HHH is there is no return of capital to shareholders and no consistent base of earnings either. I strongly preferred the company as a real estate only situation. He massively overpaid for Vantage too. Will trade cheap to NAV until it’s truly shareholder friendly.
An excellent and insightful report on $HHH. https://t.co/cvFpfHoAkP
 CPT · long
Camden Property Trust owns multifamily properties across the U.S. Southeast and Southwest.
Nobert Lou crushed it on $NVR in the late 90s, his writeups under Charlie479 on VIC are mandatory reading. You will be a better investor after reading this and gain valuable mental models to overlay on interesting real life examples. Norbert invested in Burlington Northern before Buffett. Joel Greenblatt gave him money. His investment in Brahma profiled here is legendary and similar to Buffett with Coke. I lastly loved his mental models on TGS Nopec https://t.co/OZorTJIv9W
I see this a lot in the investing business. For example, the young fiery aggressive fund managers of the 1990s, who called out dishonest bad management, are now behaving like the companies they used to vicisouly attack. Stuff like $GLRE or $HHH.
$JELD 12x levered facing insurmountable near-term debt maturities. Engaged advisors to sell assets to stem insolvency. Longshot odds given accelerating deterioration in end-markets and rising input costs. Setting up for a Q4 bankruptcy.
