

The Final Phase of This Bull Market Will Be Massive | Charles Lemonides
Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
Sector
Everything our editor has picked under this sector, best first.
197 stories
Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
Bristlemoon Global Fund lost 8.4% in the September quarter and added shorts in Campbell’s, REA Group, MasterBrand and Polaris amid narrow…
Jevons Paradox Is Not a Business Model: We Might Be Building Too Much Compute and Four Other Reasons Why the AI CAPEX Cycle Could Come Crashing Down https://t.co/EFTszhT3kH $ALAB $APLD $BE $CAT $CLS $CRWV $ETN $FN $GEV $HUT $LITE $MOD $NBIS $NVT $ORCL $POWL $STRL $TLN $VRT
@compound248 $SPY 🔥🔥🔥
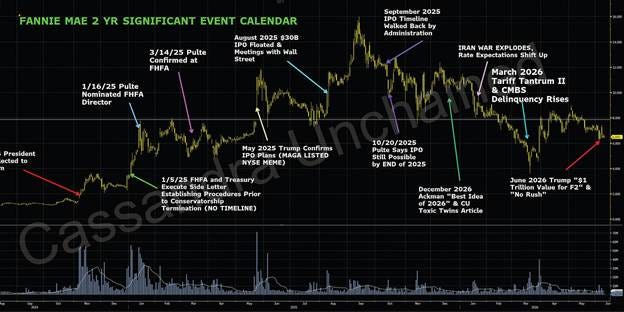
Fannie Mae and Freddie Mac common shareholders face at least 90% dilution if Treasury converts its growing senior preferred stakes into…
@ptuomov doesn't make many macro-y calls but he's 2 for 2 in the ones I've seen him make. Will be hedging my $LPRE position tomorrow. https://t.co/UPoDemQbXW
"The Russell 2000 index, which tracks shares of smaller companies, fell for a fifth-straight week, its longest weekly losing streak since May 2022." $IWM As Yields Surged, Small-Cap Stocks Were Hit Hard https://t.co/71BUJrMnXb
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
The S&P 500 lost 18% in 2022, and the Bloomberg U.S. Aggregate, the main U.S. bond index, lost 13%, its worst year since it began in 1976. Over the same year, $XLE, the S&P 500 energy sector ETF, returned 64%, gold was flat, and cash earned ~1.5%. Now what if I told you there's a framework that would've said to own cash and energy in 2022, not stocks and bonds? That framework is called Gave's Four Quadrants, after Charles Gave, co-founder of Gavekal, a macro research firm. It uses two ratios built from market prices, the S&P 500 vs. Oil and Gold vs. Treasuries, to place the economy in one of four environments, and it describes what to own and what to avoid in each. Here's how stocks, bonds, gold, and cash tend to perform in each environment: → Deflationary boom: Stocks, bonds, and cash rise, and gold underperforms. → Inflationary boom: Stocks and gold rise, cash does very little, and bonds fall. → Deflationary bust: Bonds and cash rise, gold stays fairly stable, and stocks fall. → Inflationary bust: Gold and cash rise, while stocks and bonds fall. In my backtest of Gave's rules from 1970 to September 2026, a portfolio split equally between cash, the S&P 500, and either 10-year Treasuries or gold, whichever the framework favored, would have returned 5.7% per year after inflation. Its max drawdown was 28%, vs. 54% for the S&P 500. As of the end of September 2026, the two ratios place the U.S. in an inflationary boom phase. But since January 2025, the S&P 500 to gold ratio has been below its 7-year average, which has often come a few months before the S&P 500 to oil ratio drops below its own 7-year average. If that happens, the U.S. is back in an inflationary bust phase, like 2022. So how do you read the two ratios yourself, and what do they say to own today? That's what I walk through in my new ~20-minute video!
I wonder if Russia/Ukraine will come to some sort of agreement soon? 🤷♂️ $KYIV https://t.co/kkm1TDJbPf
Apple trades near $4.9 trillion and more than 38 times trailing earnings, versus 14 times a decade ago, leaving it exposed to multiple…
 Prakhar Agarwal, CFA 3 clicks
Probably nothing $2 trillion budget deficit for the FY Up 12% YoY During a “strong economy” (I am told) $GLD $IBIT https://t.co/mpwq2nmPOY
@Danstringer74 @TgMacro Same idea. Which is scary as an inflationista… Oddly, it’s probably somehow bullish $NVDA, but it’s always bullish $NVDA
$TLT to the entire AI complex today https://t.co/5Dt0Kg4Y3T
One of those months where $QQQ is outperforming $IWM massively (again) https://t.co/G7XXqhR41M
@ptuomov I believe it's something like the residual of the $WOOD ETF after removing standard factors.
Geoffrey Williams explains CMBS underwriting, post-GFC securitized-credit risk transfer and why credit markets reprice in step functions.
I bought the dip in the RV parts company $PATK in 2022. Back then everyone was sure we'd have a recession even though we had super negative real rates. Today $PATK is once again down 50%+, a spot I usually contemplate buying. However, today nobody is talking about a recession (except the perma doomers who don't count) and we have super positive real rates. The housing market is also weak, vs very strong back then. IE Home owners (a big group) suddenly had a lot more cash than they had a few years prior. That setup is gone today, too. I don't think I'll buy $PATK this time. It'll be the first time since I started that I pass on the opportunity. The whole setup here is very concerning for the general market, something I try not to think about too much.
@GrumpierBTDay @humblebillionz Here's what $INFL holds: https://t.co/UBtdHLRgc8
When rates jerk higher and everything rate-sensitive gets smoked together, that’s when you want to swoop in on the names where you actually have conviction. Rates spike. $FTAI, $CORZ, $CIFR, $OWL all gap down 5%. Did anything change in the catalyst? No? Buy the dislocation.
Maybe I'm being too simplistic, but it seems like it's going to be hard for the market to have a sustained move higher if $GS doesn't start acting better.
$FOUR trading on ME headlines is one of the dumbest things in this dumbass mkt
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
Latticework’s briefing questions AI capex returns while featuring Close Brothers, Green Landscaping and OMS Energy Technologies.
