
Negligible Capital on X
@PumpCapitalLLC Yeah $CASY rocks. About the closest you can get to a public Bucky’s
Sector
Everything our editor has picked under this sector, best first.
182 stories
@PumpCapitalLLC Yeah $CASY rocks. About the closest you can get to a public Bucky’s
Cal-Maine, the largest U.S. egg producer, trades at 1.6x book versus a 2.1x 20-year median, with net cash and investments equal to 23% of…
 OFRM · long
Once Upon a Farm (OFRM) makes organic baby food, smoothies and kid snacks using high-pressure processing instead of heat pasteurization.
Yeah it’s pretty hard to predict, I think with good data tracking and social sentiment you might be able to gain an edge. If you can predict only a handful a year your returns could be outstanding. I successfully predicted $BYND last year for a sizeable return. You could also subscribe to https://t.co/7R7A2Nonkw
$celh https://t.co/apPT4ADdcm https://t.co/kGhsFi95q7
Someone just sent me a brief slide deck on $MCD and it made me realize that I never, I mean never hear anyone talk about it on this platform. Not even @jeffmacke mentions $MCD at his 3:45AM Denny's sessions and he likes to keep everyone on their toes about monster consumer franchises that receive little investor attention in this tech driven era. It did remind me that Ron Dottin called the bottom in this stock in late 2002 after $MCD went through 3-CEOs in a few years (one of which who died) and the company was seemingly in shambles. The stock went up 5x in 5-years. That was back when that meant something. On paper, $MCD looks like the least interesting setup (long or short) I've seen in a really long time.
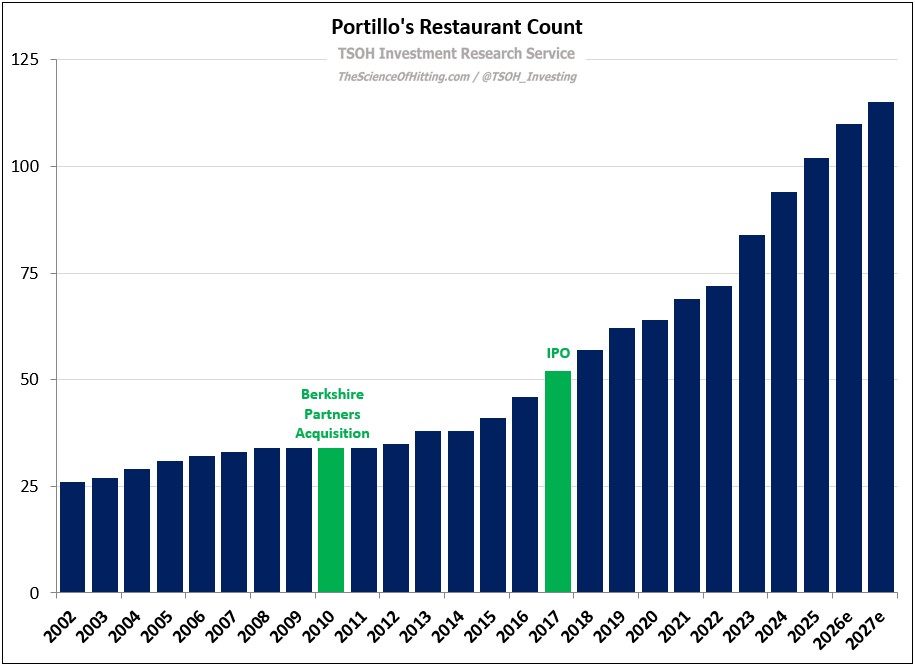
Portillo’s reset follows weak Texas unit economics, cutting next year’s openings to five from roughly 10 annually and shrinking store…
$suja dug in on a recent ipo that has collapsed, weirdly saw a bunch of people commenting on it and got curious. On the service it seems cheap, but EBITDA is not FCF. And I struggle to understand how the business scales the way the bulls and the sell side want you to believe it will. Cumulative fcf has been negative for years, and of course they cleaned the books for an ipo year, so numbers elevated td, but still nothing to get excited about and forward numbers already look disappointing right of the gate versus S1 guidance (a very bad look, and terrible way to establish trust with investors and sell side coverage) New mgmt background is uninspiring Debt load is quite high even post ipo, the recently lowered interest rate is nice for delta in income statement benefits next few quarters but still have a cash flow problem but this was a nice development. No idea what the slice business is or how it fits - it would be massively cash consuming if they actually try to compete in that space saturated with deep pocketed players like poppi and many other players with national advertising campaigns and distribution/shelf agreements with players like $KO and $PEP (slice is never going to get any meaningful mind awareness or share without massive marketing investment, and Suja does not have the capital or FCF to pull that off. The 90s nosteliga approach already worn off from the early 2025 launch as its not a relaunch of that heritage brand, it's just the ip wrapped as a prebiotic soda. ---it seems more like a story to dangle to get the ipo out that they can sell a huge TAM in their s1, which is a further strike against the board, the PE sponsor and mgmt (likely it just sits at the range its at and gets slowly unwound in a year or two to stop further cash bleed) PE sponsored and +60% owner -- can be your friend on locking float, but also your enemy when they need liquidity, the lock up period ends, or decide to move on. --- one of their other exits through IPO went a similar way, massively collapsed in value after the ipo, wallowed for a number of years and ultimately the PE firm bought out the remaining shares at pennies on the dollar to the IPO price (agrofresh) --Structure of ownership and tax agreements is highly unfriendly to passive long common equity shareholders (good for sponsor) Ultimately its an uninspired story, that is more expensive than it appears with fully diluted shares, a very difficult consumer space that relies on trends, shelf space staying in front of KO and PEP and BUD in addition to many many others on distribution and shelf space - a concentrated number of distribution points that gives power to their buyers (highly concentrated customer base on their sales (grocery channel) Stock probably bounces along the way especially in fronton or right after the coming lockup and the market loves to squeeze things one last time before their final resting space, and the tighter float here (assuming pe stays in) likely makes that more likely an outcome than not. So a swing trader after a brutal IPO? sure I would likely bet up before it's back in time out likely for good. But as an actual investment? let alone long term investment? I find that argument deeply flawed on both financial and fundamental basis
 JBTM · long
JBT Marel is an enduring food-equipment business with low AI risk, automation upside and favorable GLP-1 exposure.
@FrenchV33921 Those are the ones that hurt. Mine was $MNST when it was HANS. I owned it during their early energy drink launch days. I sold it after a quick 2x after the CEO told me, “we got this new energy drink, but we don’t know where it’s going - or if it’ll even be successful.”😂😂
@PythiaR @BillBrewsterTBB You know it’s Joe Burnett! $MAMA ceo Adam Michaels is impressive
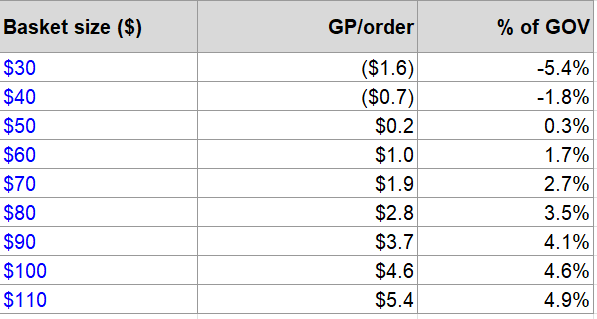
Instacart’s larger grocery baskets create disproportionately better delivery economics than DoorDash’s, making half the basket size worth…
$SUJA just under $9m in purchases from Paine Schwartz, telegraphed beforehand with a press release.👀 https://t.co/nwmFTEx0kE https://t.co/wUTLfBKL2p
Good news for $ALTO and $GPRE! U.S. to end summer blend gasoline requirement early in bid to help curb pump prices https://t.co/K0dqx0sSpV
And over the last week we saw insider buying both by the COO and more importantly the firm that was a key pre-IPO investor in $SUJA Reminds me an opportunity I missed with $COCO a few years ago. https://t.co/EkfKdOYRSG https://t.co/DbSGfl1Slo
 PRGLY · long
PureGold Price Club, the Philippines’ largest food retailer, operates hypermarkets, supermarkets, minimarts and S&R membership warehouses.
@PaulAndreola $RAVE. For anyone interested in learning more, check my pinned tweet.
@InfoArbMonitor @BlackScholesMan @Mike10947310 @Diego_La_Torre_ @SimeonResearch_ @NickCortellucci I’ll kick this off… I think you all know mine … $SIF :) The Big misinterpretation👉 the non-cash LIFO charge, masking the record quarter the company reported.
I’ve always felt that shares outstanding in microcaps tells you about the soul of Mgmt. So I instantly connected with @bmb21 when he made a similar comment pitching $AMNF at @MSmicrocaps summer virtual: “Share count tells you how Mgmt. feels about the sanctity of the shares.” https://t.co/88XsqxHLKB
$ALTO Chairman buys 50,000 shares. Open market. Incredibly bullish! Stock should be over $6 after most recent earnings report. https://t.co/1f5KSxl5NQ
Hain Celestial is under scrutiny amid food-sector situations drawing attention.
$SB #sugar what a day! https://t.co/kWAiFObTRd https://t.co/zeODI0xbe5
Very bullish $ALTO here!
$CELH ugly report https://t.co/ONzrMeYjwF https://t.co/rZCEQKjPk5
